
Firm guide · reviewed October 2026
MyFundedFutures challenge passing
MyFundedFutures offers more structural choice than most futures firms — including plans where the threshold trails only on closed profit rather than intraday. That single difference changes the entire pacing of an evaluation, and it is the first thing to confirm before buying.
Key takeaways
- End-of-day trailing is materially easier than intraday trailing: the floor moves on closed profit, so a retracement from an unrealised peak does not tighten the account.
- Plan type matters more than account size — the same nominal account can behave very differently across plans.
- Consistency is applied at payout, so capping daily profit at about a third of the target removes the most common reason a withdrawal is refused.
- Typical pass time with proper pacing is nine to fourteen trading days.
Contents
Structures and what each one means
Futures evaluations from this firm are dollar-based, with the target and the failure threshold scaling by account size. The distinguishing feature is the range of plan structures rather than any single headline number.
| Plan characteristic | What it means | Effect on difficulty |
|---|---|---|
| Evaluation phases | One or two, depending on the plan selected | Single-phase structures finish sooner but front-load the risk |
| Drawdown behaviour | Intraday trailing on some plans, end-of-day trailing on others | End-of-day is substantially easier on the same equity curve |
| Daily loss limit | Present on most plans, plan-dependent in structure | An explicit daily limit creates a second, tighter constraint on some days |
| Consistency | Applied at payout | Passing is unaffected; the first withdrawal can be delayed by one dominant day |
| Account range | Mid-tier sizes, scaling by plan | Difficulty is roughly constant across sizes at equal discipline |
The practical advice that follows is short: read the plan you are buying, not the firm's advertising. Firms in this market frequently run several products under one brand, and a comparison table that lists a firm under one structure can be quietly wrong for the plan a trader selects at checkout. Screenshot the rules shown at the point of purchase and keep them with the trading plan — several traders have discovered after a reset that the plan they assumed they had bought was a different product with a different threshold.
If you are choosing between plans, the ordering that usually makes sense for a rules-based approach is: end-of-day trailing with no consistency requirement during the evaluation, then end-of-day trailing with payout-stage consistency, then intraday trailing. The first is the most forgiving assignment available in futures; the last is the one that punishes both losing and giving back.
Why end-of-day trailing is easier
An intraday trailing threshold follows your peak unrealised equity. An end-of-day trailing threshold follows only profit that has been closed at the end of a session. On the same equity curve, the second produces a materially different account.
Consider a session that reaches $3,400 of unrealised profit before retracing to $1,100, which is then closed. On an intraday trailing account, the floor has already risen by $3,400, so the trader is $1,100 better off in realised terms and $2,300 closer to failure than they were that morning. On an end-of-day trailing account, the floor rises by $1,100 — the amount actually banked — leaving the cushion exactly where the profit says it should be.
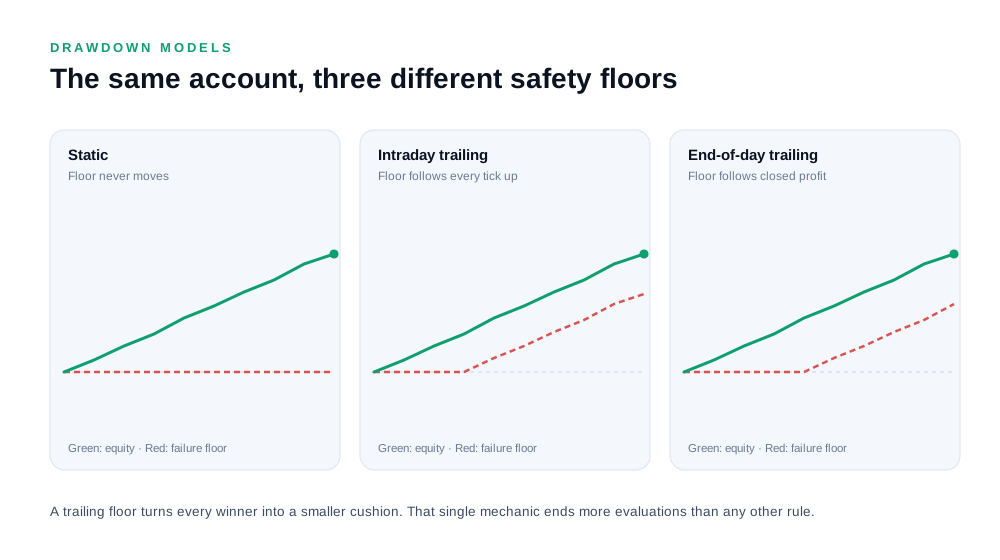
Three practical consequences follow, and they are the reason this distinction deserves more attention than the profit target.
Holding a runner is no longer penalised. On an intraday trailing account, letting a winning position run and giving part of it back permanently reduces the buffer. On an end-of-day structure, the same behaviour costs nothing beyond the profit that was not taken — the floor only reflects what was banked.
Risk per trade can stay more stable. Intraday trailing forces size reduction as progress accumulates, because the floor chases the peak. End-of-day trailing reduces that pressure, so a plan can keep risk closer to constant and still finish with a healthy buffer.
Session timing becomes less punishing. A strong morning followed by a quiet afternoon is neutral on an end-of-day account and expensive on an intraday one. Traders whose edge is concentrated in the first hours of the session find the end-of-day structure considerably more forgiving for exactly that reason.
Where to check this: confirm which behaviour applies to the plan you are buying, in writing, before paying. It is the difference between an evaluation that rewards patience and one that punishes giving anything back, and it is invisible in a headline comparison.
The risk plan
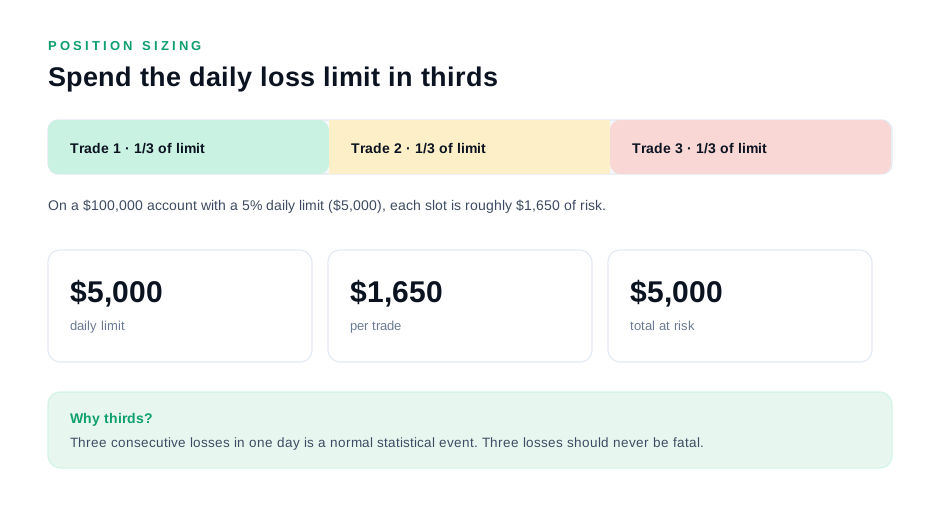
Five numbers define a workable plan, and on an end-of-day trailing structure they are slightly more generous than on an intraday one.
- Maximum risk per trade: a third of the daily loss limit, or a third of the practical buffer to the threshold on plans without an explicit daily limit.
- Daily stop: stop opening positions once 80% of the day's budget is realised. The remaining 20% absorbs slippage on the closing trade.
- Daily profit cap: about a third of the total target, which keeps a payout-stage consistency rule satisfied by construction.
- Size ladder: full planned size to 50% of target, three quarters from 50% to 80%, half beyond 80%. On an end-of-day structure the reduction is gentler than intraday trailing requires, but it is still worth applying.
- Floor check: recalculate the threshold each morning — on an end-of-day structure it changes once a day, which makes the check simpler rather than less important.
The difference from an intraday trailing plan is the fourth item. Because the floor only moves on banked profit, the pressure to cut size aggressively as an evaluation progresses is lower, and the plan can hold risk closer to constant. What it cannot do is ignore the floor: a series of closed winning sessions still raises the threshold, and the buffer still narrows in absolute terms relative to the peak — just predictably, once per day, on numbers the trader has already banked.
Pacing an evaluation
A realistic pace is nine to fourteen trading days for a single-phase structure, and slightly longer where two phases apply.
Sessions 1–3 — prove the plan. Full planned size from the start is reasonable on an end-of-day structure, because the floor does not chase unrealised peaks. One or two setups per session, closed with a cap of roughly a third of the target, and no extension of a good day beyond the cap.
Sessions 4–8 — the working middle. Sessions produce 0.4% to 0.8% of account balance each, which on a mid-tier account accumulates to the target over two to three weeks. Daily profit stays under the cap, so the best day never becomes a payout problem.
Sessions 9–14 — close it out. Size reduced to three quarters and then half as completion passes 80%. The remaining ground is covered in small increments. Because the floor updates only on closed profit, the plan can bank gains deliberately rather than holding for a larger number, which is the more predictable way to finish.
Completion. Trading stops when the target and the minimum day count are both satisfied. Where the minimum count is the later of the two, the plan trades the smallest possible closed position on the remaining required days rather than maintaining normal exposure on an account that is already at target.
Consistency at payout
Consistency is enforced when a withdrawal is requested, not during the evaluation, which means a dominant day does not invalidate a pass — it delays a payout.
The arithmetic is fixed: under a 30% best-day rule, total profit must reach at least 3.33 times the largest day. A $2,500 best day requires $8,334 in total; a $5,000 best day requires $16,667. The full mechanics, including how to repair a ratio that fails, are in the consistency rule guide.
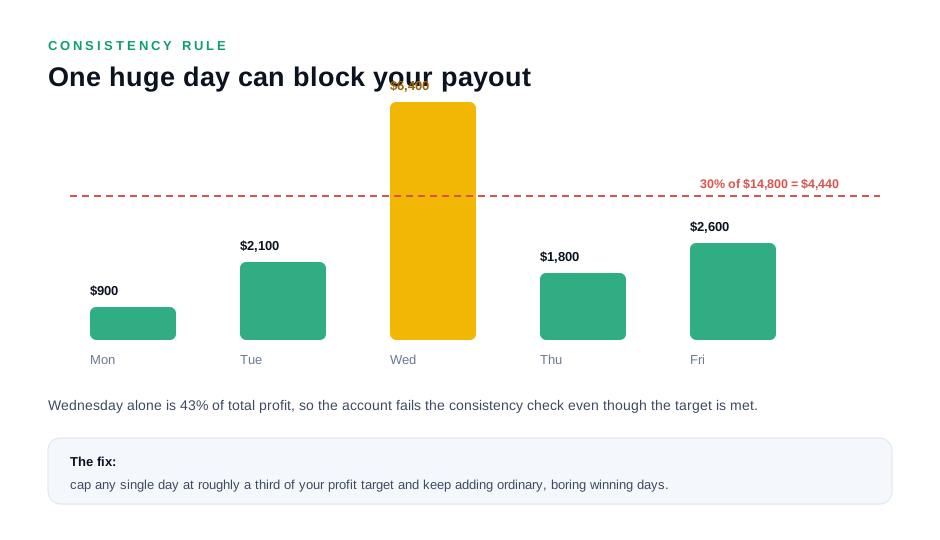
The practical response is the same as at every other futures firm: cap daily profit at about a third of the eventual total. On a $6,000 target that means $2,000 per session, which leaves the ratio comfortably below 30% whenever the target is reached. Repairing a ratio after the fact is possible — additional ordinary winning days, sized small — but it takes weeks that were avoidable.
A worked evaluation, session by session
A mid-tier futures account with a $6,000 target on an end-of-day trailing plan with a consistency requirement at payout.
Session 1 — +$640. Full planned size, one setup, closed at $640 rather than held. The floor rises by $640 at the close, which is exactly the amount banked — the property that makes end-of-day trailing predictable.
Session 2 — +$1,410. A stronger session that reaches $2,300 unrealised before being closed at $1,410. On an intraday trailing account that retracement would have permanently reduced the buffer; here the floor rises by $1,410 and the cushion matches the profit.
Session 3 — −$380. One loss at planned size, then closed. A losing day does not move the threshold on either trailing structure, so the cost is confined to the daily budget.
Sessions 4–7 — +$2,780 combined. Completion reaches 80%, so size drops to three quarters and then to half. No session exceeds the $2,000 daily cap, which keeps the best day at $1,410 — about 23% of the target and inside a 30% payout rule by construction.
Sessions 8–11 — +$1,550 combined. The final increment, delivered in four small sessions at half size. The target is reached on session 11 with the minimum day count satisfied.
Completion. Trading stops. The consistency ratio stands at roughly 19%, so the payout request can be made as soon as the funded-phase conditions allow rather than after a repair period — which is the entire practical benefit of having capped daily profit during the evaluation.
What the sequence demonstrates: one losing session, one session that gave back $890 of unrealised profit, and a finished evaluation with a payout-ready distribution. On an intraday trailing plan, that same sequence would have ended with a thinner cushion.
Where attempts fail
- Buying the wrong plan. The most expensive mistake at a firm with multiple structures. An intraday trailing plan traded with an end-of-day plan's sizing is a recipe for a reset.
- Assuming the threshold never moves. End-of-day trailing still trails. Traders who calculated their room once in week one and never recalculated it are consistently surprised in week three.
- One dominant session. Reaching the target quickly leaves a distribution problem at payout, which is a delay rather than a failure — but a delay of weeks.
- Trading through a daily cap to "stay active". Minimum day requirements are satisfied by a single small closed trade, not by maintaining exposure.
- Ignoring news windows. Futures firms restrict trading around scheduled releases and enforce it consistently. A position opened before the window can still breach if it must be closed.
- Exceeding position caps. Maximum contract counts are usually in the terms rather than on the evaluation page, and breaching one voids an attempt regardless of the outcome.
- Treating a funded account as permission to change approach. The funded rules are stricter at payout than the evaluation rules are during the assessment, and traders who loosen up after funding lose the account during the wait to a first withdrawal.
From pass to payout
A passed evaluation produces a funded account governed by its own conditions, and at futures firms those conditions are usually stricter than the evaluation itself.
| Condition | During the evaluation | On the funded account |
|---|---|---|
| Profit target | One-time, to pass | Recurring threshold before each payout |
| Drawdown behaviour | Trailing, per the plan purchased | Usually static at the starting balance |
| Consistency | Applied at payout | Applied firmly at payout |
| Minimum days | To complete the evaluation | Five to ten before each withdrawal |
| KYC | At registration | Again before the first payout |
The good news is that the trailing mechanic normally disappears at funding, replaced by a static failure level — which removes the rule that made the evaluation hardest. The constraint that remains, and binds hardest, is consistency, because it is measured against a payout request rather than against a pass.
Three habits make the funded phase straightforward. Complete KYC in the first week rather than when the threshold is reached. Plan the profit threshold and the minimum day count to complete on the same day, so there is no idle period at target. And keep daily profit capped at about a third of the eventual total, so a distribution problem cannot develop in the first place. The payout process guide covers each step and the delays that block first withdrawals.
How this fits with a passing service
Everything in this guide describes a plan that a disciplined trader can execute personally. What a passing service adds is not a better market view — it is the rulebook translation, the daily floor check and the discipline to cap a winning session, sustained over two to three weeks without the emotional drift that comes from trading one's own money against a deadline.
ElitePropX trades MyFundedFutures evaluations for a flat $220, with retries covered on rule breaches and no profit split on the funded account. The one check that belongs on your side before buying: confirm your firm's current terms on third-party trading, because some firms prohibit it and enforcement can arrive after funding. That risk is the account holder's, and it is worth resolving before any payment rather than after a payout is requested.
How this firm compares with other futures evaluations
The futures market is differentiated almost entirely by how failure thresholds behave, so that is the axis worth comparing on.
| Firm | Threshold behaviour | Daily limit | Consistency | Distinguishing feature |
|---|---|---|---|---|
| MyFundedFutures | End-of-day trailing on some plans, intraday on others | Plan dependent | At payout | Genuine structural choice between trailing models |
| Apex Trader Funding | Intraday trailing | Via trailing floor | 30% best day at payout | Largest account range in the market |
| Topstep | Intraday trailing | Explicit | Best-day expectation | Stated failure conditions, two loss rules at once |
| Take Profit Trader | Trailing | Explicit | At payout | Smaller entry tiers |
| TradeDay | End-of-day trailing | Explicit | Yes | Simpler structure, narrower account range |
The practical conclusion from that table is that end-of-day trailing is the most valuable single feature available in a futures evaluation, because it removes the mechanic that punishes giving back an unrealised gain. Three of the five firms above offer it on at least some plans, and where a firm offers both structures the end-of-day version should be chosen unless the intraday plan is dramatically less expensive — which it rarely is by enough to justify the difference.
A second observation: consistency at payout is close to universal in futures, unlike in forex, where several large firms apply no consistency requirement at all. Traders whose profit becomes concentrated by style — trend traders who take a small number of large positions — should weigh that structural difference carefully before choosing a futures evaluation at all. For that style, a forex or CFD evaluation with a static drawdown and no consistency rule is frequently the easier route to a funded account, even though the instrument set is different.
Account sizes, scaling and sequencing
Because both the target and the threshold scale with account size, difficulty is roughly constant across tiers at equal discipline. What does not scale is cost: commissions and slippage are fixed in dollars per contract, so they consume a larger share of a smaller target. That makes small accounts marginally harder to pass than large ones, which is worth knowing before buying the cheapest tier and expecting a higher pass rate.
Scaling is usually tied to a payout record rather than to a single strong month. Firms generally increase the split percentage or the account size after a defined number of completed withdrawals, which rewards regularity over size — a trader who withdraws a moderate amount monthly for several months accumulates a stronger record than one who makes a single large withdrawal. The practical sequencing for anyone intending to run multiple accounts is to pass one, trade it into a payout or two, and then add a second rather than running two evaluations simultaneously. Correlated positions across accounts are treated as a single exposure by most futures firms, and splitting attention across two assessments slows both.
What to check before buying a plan
Seven questions resolve almost all of the ambiguity that surrounds a multi-plan futures firm.
- Does this specific plan trail intraday or end-of-day? The single most consequential detail, and the one most often left unstated on comparison pages.
- What is the trailing distance in dollars? Convert it against the target: if the distance to failure is a third of the target, the account is fragile from the first session and the plan should be sized accordingly.
- Is there a separate daily loss limit, and is it tighter than the trailing distance? On some plans both apply, and the tighter one governs each day.
- Does the threshold stop trailing at any point? Some firms stop following once the floor reaches the starting balance, which materially reduces risk in the later part of an evaluation.
- What is the minimum trading day requirement? And what counts as a qualifying day — a closed trade, an order fill, or a held position.
- When is consistency measured, and against what? At payout, against total profit, is the usual answer in futures; the percentage determines the multiple required.
- What are the funded-phase payout conditions? Minimum days before the first withdrawal, the profit threshold, and whether either resets after each payout.
Answering those seven questions takes about twenty minutes with the firm's own documentation, and it prevents the most expensive mistake available in futures prop trading: buying a plan whose rules do not match the way you trade, then treating the resulting failure as evidence about your ability rather than about a structural mismatch.
Two of the seven are worth repeating because they are the ones traders most often skip. The trailing distance in dollars, compared against the target, tells you whether the account is fragile or roomy before you trade a single contract — a plan where the distance to failure is a third of the target demands a completely different approach from one where it is equal to the target. And the question of whether the threshold stops trailing at any point changes the arithmetic of the final third of an evaluation, which is the phase where most trailing accounts are lost. Neither answer appears on a pricing page, and both take one line in an email to the firm's support team.
Frequently asked about MyFundedFutures
What is the difference between end-of-day and intraday trailing?
End-of-day trailing updates the failure threshold once per session, based on profit that has been closed. Intraday trailing follows peak unrealised equity, so a position that reaches a high and retraces has already moved the floor. End-of-day is materially easier on the same equity curve.
How long does it take to pass?
Nine to fourteen trading days with proper pacing on a single-phase structure. Faster passes are possible but usually create a consistency problem that delays the first payout.
Is there a consistency rule?
Consistency is applied when a payout is requested, commonly as a 30% best-day expectation. A $2,500 best day requires about $8,334 of total profit before the withdrawal is approved.
What risk per trade should I use?
A third of the daily loss limit at most, with trading stopped once 80% of the day's budget is spent. On plans without an explicit daily limit, base the figure on a third of the practical buffer to the trailing threshold.
Do I need to reduce size as I approach the target?
The pressure is lower than on an intraday trailing plan, but the threshold still rises with banked profit. A ladder — full size to 50% of target, three quarters to 80%, half beyond — keeps the final phase predictable.
Which plan should I buy?
For most traders, the plan with end-of-day trailing behaviour. Read the terms of the specific plan at checkout rather than relying on the firm's general description, because structures differ between products sold under the same brand.
What is the biggest mistake at this firm?
Buying an intraday trailing plan and trading it with the sizing assumptions of an end-of-day plan. The ruleset determines the plan, not the other way round, and this is the error that produces resets that look inexplicable to the trader.
What happens after the evaluation passes?
A funded account is issued with a minimum day count, a profit threshold, a consistency check and KYC requirements. The trailing behaviour usually becomes static at that point, which is the easier phase of the two.
Choosing between the plan structures
MyFundedFutures sells more than one drawdown model, and the choice between them matters more than the choice of account size. A trader who picks the wrong structure for their style is not making a pricing decision; they are choosing a different challenge and paying for the harder one.
The two models differ in one respect that changes everything: when the failure threshold updates. An intraday model follows peak equity in real time, so an unrealised gain that comes back to the entry still leaves the floor higher than it was. An end-of-day model updates once, at the close, on the realised balance, so a trade that goes into profit and returns to entry leaves the floor exactly where it started.
| Situation | Intraday trailing | End-of-day trailing |
|---|---|---|
| Trade goes +$800 then back to entry | Floor is $800 higher; room is reduced | Floor unchanged |
| Trade closes +$800 | Floor rises by $800 at the close | Floor rises by $800 at the close |
| Overnight gap against you | Counts fully against the raised floor | Counts fully against the raised floor |
| Style it suits | Scalping with tight, fast exits | Anything holding a position through noise |
Which model suits which trader
End-of-day trailing suits most discretionary traders, because most discretionary trades contain a period of unrealised profit that is given back before the exit. On an intraday model, that give-back is charged twice: once in the profit that was not banked, and once in the room that has disappeared. On an end-of-day model it is charged once, which is the same price the market charges everyone else.
Intraday trailing suits a style with genuinely tight exits and a high win rate, where positions rarely see meaningful unrealised profit that is surrendered. A scalper who takes two to four ticks and is out is not exposed to the mechanic in the same way a swing trader is. Even then, the margin for error is narrower than the marketing implies, and the discipline required at the end of a profitable session is higher — the floor has already moved, and the remaining budget is smaller than the account's equity suggests.
Account size, once the model is settled
Size is the easier decision and it should follow the model rather than lead it. The percentage rules scale exactly, so a larger account is the same challenge with a bigger fee and a bigger payout ceiling. The only argument for going larger on a first attempt is a payout ceiling that would otherwise bind; the only argument for going smaller is preserving capital for a second attempt if the first fails.
A useful compromise on a first futures evaluation is the smallest size that permits a meaningful payout after the profit split, traded to a first withdrawal before a second account is considered. That sequence produces a funded trader with a track record; three simultaneous evaluations produce three correlated positions and a single bad week that ends all of them.
The daily routine on an end-of-day model
The routine differs slightly from an intraday account, and the difference is worth internalising before the first session rather than during it.
Morning: two numbers, one decision
Write the current floor and the distance to it. Then subtract the day's planned risk from the distance. If the result is uncomfortable — practically, if two full-risk losses would bring the account within a normal losing streak of the floor — cut size for the session. This single check prevents most failures on trailing accounts, and it takes ninety seconds.
During the session: ignore the unrealised peak
The head start that end-of-day trailing gives is the ability to let a position breathe without the floor moving. Traders who check the running peak every few minutes convert that advantage back into an intraday model by behaving as though the floor had already moved. The number that matters during the session is the realised balance; the running peak is noise until the close.
Close: bank the day, then stop
At the close the floor updates, and this is the moment a profitable day becomes a smaller budget for tomorrow. The discipline is to stop trading once the close is recorded rather than to open one more position in the few minutes before it. A trade opened at 16:55 with the intent of "one last look" is a trade whose loss will be measured against the smallest budget of the week.
Weekly: recalculate the plan, not just the numbers
Once a week, ask whether the remaining distance to the floor still supports the original per-trade risk. If it does not, the answer is smaller size rather than a tighter stop: tightening stops to preserve size changes the trade's expectancy, which is the one variable that should not be touched mid-evaluation.
There is one more number worth tracking on an end-of-day account: the gap between the highest close and the current balance. That gap is the amount of profit already surrendered, and on a trailing model it is the best single measure of whether the plan's exits are too loose for the structure.
On days when the market is quiet, that number barely moves, which is exactly when a trader is most likely to widen a target to make something happen. The record is the antidote: if the surrendered-profit column is growing while the realised column is not, the plan is being changed by boredom rather than by evidence.
The same log answers a question that matters after the pass: on an end-of-day account, the winning approach is usually the one that gave back least, not the one that caught the biggest move.
Two numbers per session are enough to make that visible: realised profit and the highest unrealised profit reached before the exit. The difference between them is what the structure charged for the exit, and a fortnight of that comparison tells a trader more about their plan than any backtest of the same period.
Want the evaluation traded for you?
One flat $220 for any prop firm, any account size. Retries covered, no profit split, funded login in your name. If your firm bans third-party trading we tell you before you pay, and we will not take the job.