
Firm guide · reviewed October 2026
Apex Trader Funding challenge passing
Apex is the best-known futures prop firm, and it now runs two evaluation models rather than one: an end-of-day (EOD) drawdown account and an intraday trailing account. Which model you buy changes the arithmetic completely. This guide covers both, why the 50% payout consistency rule blocks so many withdrawals (30% still applies to legacy accounts), and how to pace an evaluation whose floor moves.
Key takeaways
- The trailing threshold follows your peak unrealised equity, so a strong session reduces your remaining cushion rather than increasing it.
- Risk must fall as the target approaches — the opposite of the instinct to press a winning account.
- The payout consistency rule is 50% on current accounts: a $6,000 best day requires $12,000 of total profit. Legacy accounts still use 30%.
- EOD evaluations have no intraday trailing, a fixed daily loss limit and a 30-day access period; intraday evaluations trail the peak in real time.
- Account sizes extend to $300,000, which is larger than almost any competitor, and the same discipline scales.
Contents
Apex's evaluation structure
Apex Trader Funding runs futures evaluations with dollar-based targets and thresholds rather than percentages, and the account range extends higher than most of the industry.
| Account size | Profit target | Drawdown model | Consistency rule |
|---|---|---|---|
| $50,000 | $3,000 | EOD ($2,000) or intraday trailing | 50% best day at payout (30% legacy) |
| $100,000 | $6,000 | EOD ($3,000) or intraday trailing | 50% best day at payout (30% legacy) |
| $150,000 | $9,000 | EOD ($4,000) or intraday trailing | 50% best day at payout (30% legacy) |
| Up to $300,000 | Scales with size | EOD or intraday trailing, plan-dependent | 50% best day at payout (30% legacy) |
Two features define the assignment. The first is the drawdown model. On the EOD evaluation the threshold is calculated once per day from the closing balance, is fixed for the next session, and does not follow unrealised profit; the account also carries a separate daily loss limit ($500 on a 25K, $1,000 on a 50K, $1,500 on a 100K and $2,000 on a 150K) and a 30-day access period. On the intraday trailing evaluation the threshold follows peak equity in real time, including open profit. The second feature is the payout-stage consistency rule — 50% on current accounts, 30% on legacy accounts — which is covered in detail below and in the consistency rule guide.
Strategic context worth having before choosing an account size: Apex's evaluation pricing is among the most aggressive in futures, and promotional discounts are frequent. Cheap entries are good for testing a plan and bad for encouraging discipline — a trader who has spent $40 on an evaluation is more inclined to gamble than one who spent $400, and the rules do not care which it was.
The intraday trailing threshold, explained
Most traders understand a maximum loss as a fixed line below the starting balance. A trailing threshold is different, and the difference is the single most common reason an intraday Apex evaluation ends unexpectedly. If you buy the EOD model, none of this section applies intraday: the threshold is recalculated once per day and held fixed through the session.
On a trailing structure, the failure level rises with your peak equity. Suppose a $100,000 account starts with a threshold at $96,000 — a $4,000 cushion. If the account reaches $103,000 in unrealised open profit, the threshold rises to roughly $99,000 and the cushion is still $4,000 in absolute terms, but the account now has to fall $4,000 from a higher peak to fail. That sounds neutral until you note what happens next: the cushion is measured from the peak, and a $3,000 retracement from $103,000 puts equity at $100,000 with the threshold at $99,000 — one bad trade from failure, despite being up on the day.
Now add the most important detail. On an intraday trailing structure, the threshold follows unrealised profit. A position that is $5,000 in open profit and then gives back $4,000 has already lifted the floor, and the retracement leaves the account with $1,000 of realised profit and a threshold that has permanently moved. The trader did nothing wrong, took no loss, and is nonetheless far closer to failure than they were that morning.
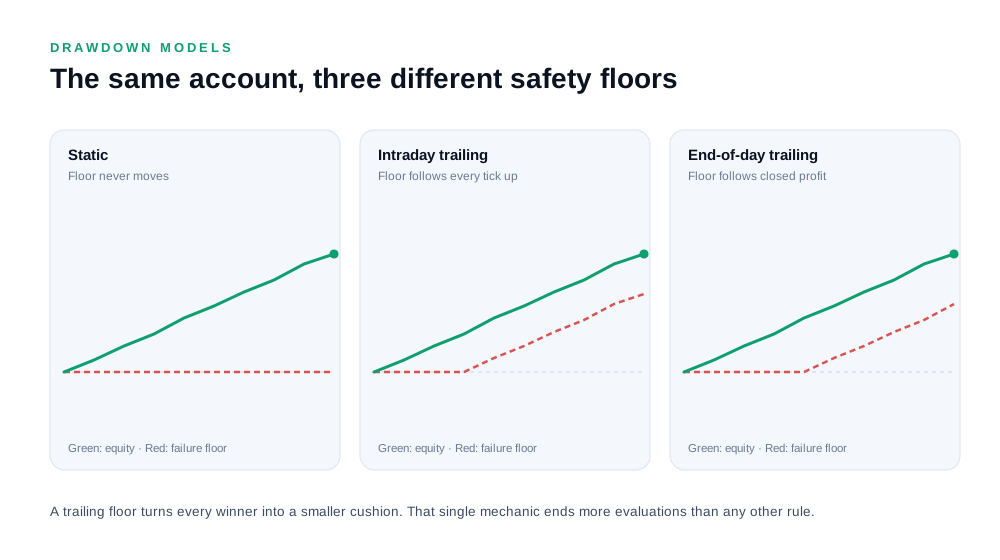
This is why Apex evaluations are harder than their headline targets suggest, and why traders who arrive from static-drawdown forex firms find the structure unforgiving. The rules do not punish losing; they punish giving back, which is a different behaviour and requires a different plan.
The math of a moving floor
On a fixed floor, the calculation of how much room remains is a subtraction from a constant. On a trailing floor, it is a subtraction from a moving number, and the correct response is to treat the peak — not the balance — as the reference point.
| Peak equity reached | Realised profit | Remaining room to failure | Correct risk per trade |
|---|---|---|---|
| $100,000 (start) | $0 | Full threshold | Full planned size |
| $104,000 | $3,200 | Unchanged in absolute terms | Full planned size |
| $108,000 | $6,500 | Unchanged in absolute terms | Reduce by a quarter |
| $112,000 | $9,000 (target) | Unchanged, but the pass is complete | Half size or stop |
The table hides the danger, so it is worth spelling out. The absolute room to failure stays constant because the floor moves with the peak — but the room only stays constant if equity stays at the peak. Every dollar of retracement from the peak is a dollar closer to failure, and retracements are normal. A trader at a $112,000 peak with $9,000 of realised profit who gives back $3,000 is at $109,000 with a floor at roughly $108,000 — one average losing position from a failed evaluation, on an account that has already passed its target.
The practical consequence is that on a trailing structure the last portion of an evaluation is the most dangerous part, not the safest. That is the opposite of a static account and the opposite of most traders' instincts.
A risk plan for a trailing account
Four decisions define a workable Apex plan.
- Size for the implied daily budget, not the headline target. Because the threshold trails, the effective room for a day's adverse movement is smaller than it looks. Treat the trailing distance as the day's practical risk budget and divide it into thirds.
- Scale risk down as progress increases — never up. Full planned size to 40% of target, three quarters of planned size from 40% to 70%, half size from 70% to completion. This is counter-intuitive and it is the difference between passing and failing.
- Close open profit deliberately. On a trailing structure, unrealised profit is dangerous because it lifts the floor without banking anything. Taking profit at planned levels converts a liability into a real gain and stops the floor from chasing a number that never materialised.
- Do not trade the same instrument continuously for hours. Continuous exposure on a trailing account means continuous floor movement. Shorter, planned sessions reduce the total number of ticks that can drag the threshold upward.
The one-line version: on a trailing account, an untouched pass is worth more than extra progress. A trader at 95% of target with the floor far below is in a better position than one at 130% of target with the floor directly beneath current equity.
The consistency rule at payout: 50% now, 30% on legacy
Apex applies a consistency rule when a payout is requested. On current accounts no single day may account for 50% or more of total profit since the last payout; the calculation resets after each approved payout. On legacy Performance Accounts the older 30% rule still applies. The arithmetic is set out fully in the consistency rule guide, but the shape is simple: under the 50% rule a $6,000 best day requires at least $12,000 of total profit, and a $3,000 best day requires $6,000. Under the legacy 30% rule the same $6,000 day requires $20,000.
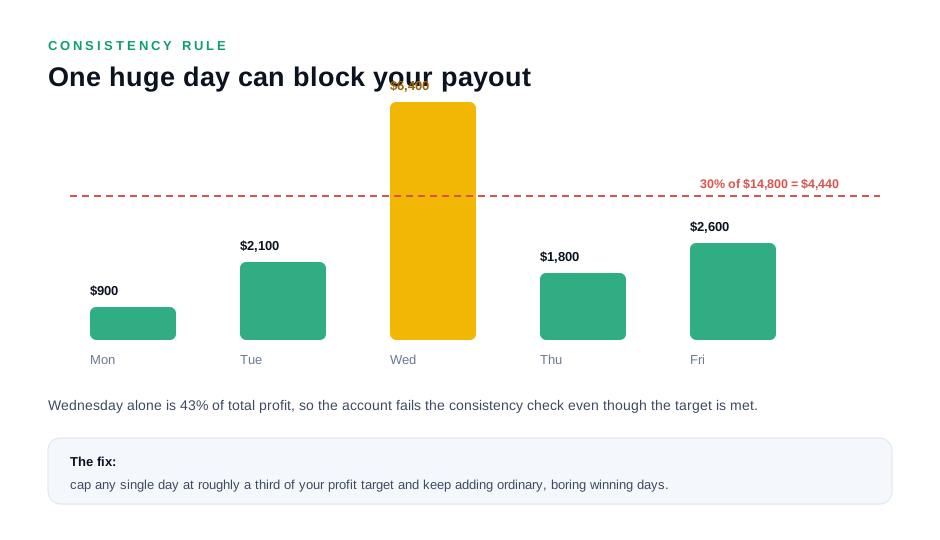
The interaction with a trailing threshold is what makes the combination difficult. A trader on a trailing account is tempted to bank one large day and finish, but a large day is exactly what the consistency rule penalises at payout. The two rules pull in opposite directions: the threshold punishes holding runners, and the consistency rule punishes taking them. The resolution is to cap daily profit at roughly a third of the eventual total — which on a $6,000 target means about $2,000 per session, spread across several sessions rather than concentrated in one. A third is comfortably inside both the 50% and the legacy 30% rule.
A second interaction is less obvious. Because the threshold trails unrealised profit, a large winning day also raises the floor substantially, so a trader with a $5,000 day on a $100,000 account finishes the session with less room than they started despite being significantly up. Combining a large day with a raised floor is the worst of both: the consistency problem and the trailing problem in the same session.
Pacing an Apex evaluation
A realistic pace for a $100,000 account with a $6,000 target is eight to fourteen trading days, structured as follows.
Sessions 1–3: prove the plan works, do not chase the target. Full planned size, one or two setups per session, and an explicit cap of about $1,200 of profit per session. Expected outcome: 20–30% of target with the floor moved modestly.
Sessions 4–7: the working middle. Size reduced by a quarter from here. Daily profit capped at $2,000, which is a third of the target and therefore satisfies the consistency rule by construction. Target completion should reach 60–70% by the end of this phase.
Sessions 8–14: protect the pass. Half size, shorter sessions, and a hard rule that any session ending more than $2,000 up is closed rather than extended. The remaining 30% is collected in small increments, and the floor is recalculated every morning rather than assumed.
Completion. The evaluation is finished when the target is reached and the minimum trading days are satisfied. At that point trading stops entirely — on a trailing structure, continuing to trade after reaching target is the single most expensive habit available.
Where Apex attempts fail
- Holding a runner through a retracement. The floor has already moved; the retracement is measured from the peak, not from the entry. This is the defining Apex failure.
- Increasing size as the target approaches. The instinct that ruins trailing evaluations, because progress simultaneously reduces the room available.
- One dominant day. Efficient for reaching the target and immediately expensive at payout under the 50% rule (30% on legacy accounts).
- Trading beyond the target. Continuing after completion on a trailing account adds risk with no objective.
- Assuming the floor has not moved. Traders who calculated their room once at the start of the evaluation and never recalculated it are consistently surprised.
- Treating a discounted evaluation as low-stakes. Cheap entries encourage over-trading, and the failure mode is identical at any purchase price.
Apex compared with other futures firms
Futures firms differ less on targets and splits than on how their failure thresholds behave, and that is the axis worth comparing on.
| Firm | Drawdown behaviour | Daily limit | Consistency at payout | Account range |
|---|---|---|---|---|
| Apex | EOD or intraday trailing | Yes on EOD; via trailing floor on intraday | 50% best day (30% legacy) | Up to $300k |
| Topstep | Trailing | Yes, explicit | Best-day expectation | $50k–$150k |
| MyFundedFutures | End-of-day trailing option | Plan dependent | At payout | $50k–$150k |
| Take Profit Trader | Trailing | Yes | At payout | $25k–$150k |
| TradeDay | End-of-day trailing | Yes | Yes | $50k–$150k |
The most consequential comparison is between intraday trailing and end-of-day trailing structures. An end-of-day trailing floor updates only on profit closed at the end of a session, so intraday swings — including a large unrealised gain that later retraces — do not move it. On the same equity curve, an end-of-day trailing account finishes the session with more room than an intraday trailing one, purely because of when the floor is recalculated.
For a trader who intends to trade futures seriously, that difference is worth more than a few percentage points of profit split. Where a firm offers both structures across different plans, the end-of-day version is generally the better assignment, and the price difference between the two plans is usually smaller than the cost of a failed attempt.
Account sizes and why bigger is not better
Apex's range extends to $300,000, which is larger than almost any competitor, and the temptation is to buy the biggest evaluation available. Three reasons argue against starting there.
Costs do not scale, targets do. Commission, spreads and slippage are dollars per contract, and on a trailing evaluation the threshold distance is fixed in dollars. A larger account does not proportionally reduce the cost drag; it increases the absolute value of a single mistake while offering the same rules.
The failure mode is behavioural, not financial. A trader who size-mismanages a $50,000 evaluation will size-mismanage a $300,000 one. The ruleset is identical, so the larger account tests nothing new — it simply costs more when the same behaviour recurs.
The funded phase is where size pays. A funded $150,000 account with a 90% split and a satisfied consistency rule produces real income; a failed $300,000 evaluation produces nothing. The efficient path is to prove the plan on a mid-size account, then scale on the firm's own terms once payouts are established.
Traders who run several accounts in parallel face an additional constraint that Apex is explicit about: correlated positions across accounts are treated as a single exposure. Holding four long index positions across four accounts is one position from the firm's perspective, and it can breach a threshold on the aggregate rather than on any single account.
A worked Apex evaluation, session by session
A $100,000 Apex-style intraday evaluation with a $6,000 target, a trailing threshold and the current 50% payout-stage consistency rule, traded at a plan that reduces size as progress increases.
Session 1 — +$480. Half the planned size while the plan is being tested against real conditions. The floor moves up modestly with the peak. Nothing remarkable, which is the intention.
Session 2 — +$1,240. Full planned size. The session caps itself at $1,240 rather than pushing for more, because the daily cap is $2,000 and a session that overshoots it raises the consistency burden later.
Session 3 — −$320. One loss at planned size, then closed. On a trailing account a losing day does not move the floor — the floor only ever rises — so this session costs money and no cushion. That asymmetry is why losing days are cheap on trailing structures and giving back a peak is expensive.
Sessions 4–6 — +$2,730 combined. Target completion reaches 74%, so risk per trade drops to half size from here. The daily cap of $2,000 means no single session is capable of breaching the consistency rule even if the target is reached on its own.
Session 7 — +$360. A small session at reduced size, deliberately short. The floor is now close enough beneath current equity that the value of another dollar of profit is lower than the cost of a retracement.
Sessions 8–10 — +$1,420 combined. The remaining 16% is collected in three small sessions at half size. The target is reached on session 10 with a best day of $1,240 — about 15% of total profit, comfortably inside both the 50% and the legacy 30% rule.
After completion. Trading stops. On a trailing account, continuing after the target is reached offers no benefit and a genuine risk: any retracement from the current peak moves the account closer to failure while the evaluation has already been won.
What the sequence shows: the largest day was 15% of total profit, the floor was never the binding constraint because size fell as progress rose, and the consistency rule was satisfied before the payout was ever requested. None of that required a single exceptional trade.
Working with a passing service on a trailing account
A trailing evaluation is the case where a structured service differs most from a trader working alone, for three reasons.
Floor recalculation is mechanical and relentless. The failure level must be recomputed after every session and intrasession, because unrealised profit moves it. That is bookkeeping, not judgement, and it is the kind of work that gets skipped on a bad day — which is precisely when it matters.
Size reduction contradicts conviction. Reducing position size while an account is winning feels like abandoning a working approach. On a trailing structure it is the correct behaviour, and it is easier to execute when it is a written rule rather than a decision made in the moment.
The consistency rule is a scheduling problem. Capping daily profit at a third of the eventual total requires a plan that has already decided how many sessions the target will take. That decision is cheap before the evaluation starts and expensive in the middle of one.
All three of those are properties of the ruleset rather than of a trader's skill, which is why Apex evaluations pass reliably when they are paced and fail unpredictably when they are traded session by session on instinct. ElitePropX trades them for a flat $220 with retries covered and no profit split, applying the same scaling discipline described in this guide.
When to stop for the day on a trailing account
The daily stop rule on a trailing structure is different from the one that applies on a static account, and the difference is easy to miss. On a static account, the day ends when the loss budget is spent. On a trailing account, it ends at whichever comes first: the loss budget, or a profit level that has lifted the floor close enough to current equity to make further trading imprudent.
That second condition is the one traders never plan for. It has no fixed number, because it depends on where the peak is relative to realised profit — but it can be expressed as a rule: if the buffer between current equity and the trailing threshold falls below the risk of a single planned trade, the session is over regardless of how profitable it has been. On a $100,000 account where a planned trade risks $600, a session ends the moment the remaining buffer to failure drops under $600, whether that day is up $400 or up $2,000.
Expressed that way, the rule is mechanical and can be checked in seconds before each trade. Traders who adopt it stop ending sessions with a raised floor and a thin cushion — which is the precise combination that turns a profitable evaluation into a failed one.
Frequently asked about Apex
How does Apex's trailing threshold work?
It follows your peak equity upward, including unrealised profit, and does not move back down. The absolute distance from peak to threshold stays roughly constant, which means any retracement from the peak moves you closer to failure even if the account is well up on the day.
What is Apex's consistency rule?
On current accounts a 50% best-day rule applies when a payout is requested: no single day may account for 50% or more of total profit since the previous payout. A $6,000 best day therefore requires at least $12,000 of total profit. Legacy Performance Accounts still use the older 30% rule, where the same day would require $20,000.
How long does an Apex evaluation take to pass?
Typically eight to fourteen trading days with proper pacing on a $100,000 account. Faster passes are possible on a favourable rulebook but usually create a consistency problem at payout instead.
Should I reduce size as I approach the target?
Yes, and this is the defining rule on a trailing account — full size to 40% of target, three quarters from 40–70%, half size beyond. Progress makes a trailing account more fragile, not safer.
What happens if I give back profit after a strong day?
The failure threshold has already risen with the peak, so the retracement is measured from that peak. A $5,000 peak followed by a $3,000 retracement leaves $2,000 of realised profit and a much thinner buffer — which is why closing profit deliberately matters so much.
Is Apex harder than forex evaluations?
Structurally yes, for the same headline difficulty. An intraday trailing floor is stricter than the static drawdowns used by most forex firms, and it is the reason traders who pass static-drawdown accounts comfortably can struggle here.
Can ElitePropX pass an Apex evaluation?
Yes, for a flat $220 with retries covered and no profit split. The plan mirrors the sizing reductions described above, and the payout-stage consistency rule is planned for during the evaluation rather than repaired afterwards.
Does the trailing threshold ever stop moving?
It depends on the Apex product and platform. On intraday Performance Accounts the threshold stops once it reaches the starting balance plus $100. On Rithmic and WealthCharts intraday evaluations it stops once it reaches the target profit balance; on Tradovate evaluations it trails the peak indefinitely. The EOD evaluation does not trail intraday at all. Confirm which applies on the account you are buying rather than assuming either behaviour.
Should I trade multiple contracts or a single contract?
Contract count is a sizing decision and should be derived from the trailing distance rather than from conviction. Work out the dollar risk per contract on the instrument being traded, divide the practical daily budget into thirds, and let that number set the contract count. Most Apex failures involve too many contracts held for too long rather than too few opportunities.
What time of day is best for a trailing evaluation?
Sessions are chosen around the permitted hours and the instrument's liquidity rather than around a fixed clock. What matters on a trailing structure is session length: shorter planned sessions produce fewer ticks of floor movement, and the earliest part of the session tends to carry the widest spreads and the most news risk. Deliberate, bounded sessions are easier to manage than open-ended screen time.
What happens after the evaluation passes?
A funded account is issued with its own conditions: minimum trading days before the first payout, a profit threshold, the consistency check and KYC. The payout process guide covers the sequence.
Scaling, multiple accounts and the portfolio question
Apex is unusual among futures firms in making it straightforward to hold several evaluations and several funded accounts at once, and that structural choice changes the strategy more than most traders expect. The question stops being "how do I pass one account" and becomes "how do I run three without turning them into one large position".
The temptation is obvious: three $50,000 accounts traded with the same setup is a $150,000 position with three times the risk and, crucially, three failure thresholds that trip together. Correlated accounts do not diversify anything; they multiply the same decision. A trader who takes the same EURUSD or ES setup across five accounts has not built a portfolio, they have built leverage with extra paperwork.
The three ways traders run multiple accounts
| Approach | What it does to risk | When it makes sense |
|---|---|---|
| Same setup, all accounts | Multiplies risk and correlation | Never, as a deliberate strategy |
| Different instruments per account | Diversifies somewhat, still correlated in a risk-off move | Only with genuinely separate markets |
| Sequenced: pass one, fund it, then add | Keeps each account's risk independent | The default for anyone building a book |
Sequencing is slower and it is the only version that survives a bad week. A trader with one funded account that is 4% up and a second evaluation three days old has two independent problems; a trader with five accounts opened the same Monday has one problem that arrives five times, and the response — cutting all five at once — is the same as cutting one position at five times the size.
Sizing across accounts
If several accounts are running, the sensible approach is to treat the whole book as one risk budget and divide it. A trader who risks 1.5% per trade per account with three accounts is risking 4.5% of the combined equity on a single idea, which is above the daily limit of any individual account. The per-account percentages look compliant while the aggregate does not.
A practical rule is to halve the per-account risk for each additional concurrently traded account: 1.5% on one, 0.75% on two, 0.5% on three. The combined exposure stays near 1.5% and each account's failure threshold remains proportionate to the plan. The cost is that each account progresses slowly; the benefit is that no single trade can end more than one account at a time.
The payout cycle, and why it drives the whole plan
Apex payouts are not on demand in the way a bank withdrawal is. There is a minimum number of trading days before the first request, a profit threshold, a consistency requirement on the best day, and a processing schedule. Those four constraints interact, and the interaction is what most traders fail to plan.
The consistency requirement is the one that surprises people, because it is measured against total profit at the moment of the request rather than across the evaluation. A trader who makes $3,000 on a single strong session and $1,200 across the following fortnight has a best day of roughly 71% of profit — the account is profitable, the evaluation was passed cleanly, and the withdrawal is refused until enough ordinary profit is added to bring that ratio under the threshold.
Planning the threshold and the day count together
The two constraints usually have different deadlines, and the efficient plan lands them on the same date. If the profit threshold is reached on day five but the minimum day count is twenty, the remaining fifteen sessions exist to add ordinary profit without adding a dominant day. That is not a waiting period to be endured; it is the window in which the consistency ratio gets repaired.
The arithmetic is worth doing on paper before the payout request rather than after. Required total profit equals best day divided by the consistency percentage. With a $2,400 best day and the current 50% rule, the account needs $4,800 of total profit before the request; under the legacy 30% rule it would need $8,000. If the account is short, ordinary profit spread across small sessions is the fix, and a second large day is the opposite of a fix.
What to do while waiting
Trade smaller, not bigger. A payout request that is waiting on a day count is a period in which the only objective is not to lose what has already been earned, and the failure mode is a trader who uses the waiting period to "make the payout worth having". The payout is already worth having; the marginal profit from pressing is small compared with the risk of resetting the account to zero.
A useful discipline is to set a hard cap for the waiting period at half the normal daily budget. It feels like wasted time and it is the cheapest insurance available, because the account has already done the thing it was bought for.
When running several accounts is worth it
Multiple accounts make sense when each one is independently funded and independently traded, and when the combined risk stays inside a single account's daily budget. They make no sense as a way to increase exposure to the same idea, and they make no sense for a trader who has not yet traded one funded account through a full payout cycle.
The sequencing that works is unglamorous: pass one, trade it to a payout, then decide whether a second account adds anything. Most traders discover that the second account adds administration rather than profit — the payout ceiling on a single account is usually well above what their strategy generates in a month, so the constraint is not the number of accounts but the size of the edge.
Where a second account does add something, it is usually diversification across rulebooks rather than across positions: one account at a firm with a static drawdown and one at a firm with a trailing floor behave differently in a bad week, and having both spreads the risk of a single rulebook decision going wrong.