Service guide · reviewed October 2026
Best propfirm passing services in 2026 — and how to tell them apart
Every provider in this category sells the same sentence: we will pass your evaluation. Almost nothing else is standardised — not the price, not what happens on a failed attempt, not who owns the account afterwards, and not whether the firm you bought permits the arrangement at all. This guide treats the category as what it is: a purchase with unusual risk, where the difference between a good provider and a bad one is measured in what happens after something goes wrong.
Key takeaways
- The service you are buying is trading labour plus risk transfer, not a guarantee. Any provider describing it as a guarantee is describing something it cannot deliver.
- Pricing falls into four shapes: percentage of account size, per-phase fee, retainer, and flat fee. The shape tells you more about the provider's incentives than the number does.
- The single biggest hidden risk is the prop firm's own terms. Some prohibit third-party trading outright, and the penalty is account removal — after you have paid.
- Proof of past passes is only worth reading if it is timestamped, attributable and shows the firm's own dashboard rather than a screenshot of a balance.
- ElitePropX charges a flat $220 per evaluation at any account size, retries covered, no profit split — and works with any firm, telling you in writing what that firm’s third-party trading clause says before you pay.
Contents
- What a passing service actually sells
- The four pricing models
- What each model incentivises
- The firm-terms problem
- What "retries covered" is worth
- Reading proof properly
- What you should never hand over
- Seven tests that separate real from not
- When a service is the wrong purchase
- What you are not buying
- A checklist before you pay
- Frequently asked questions
What a passing service actually sells
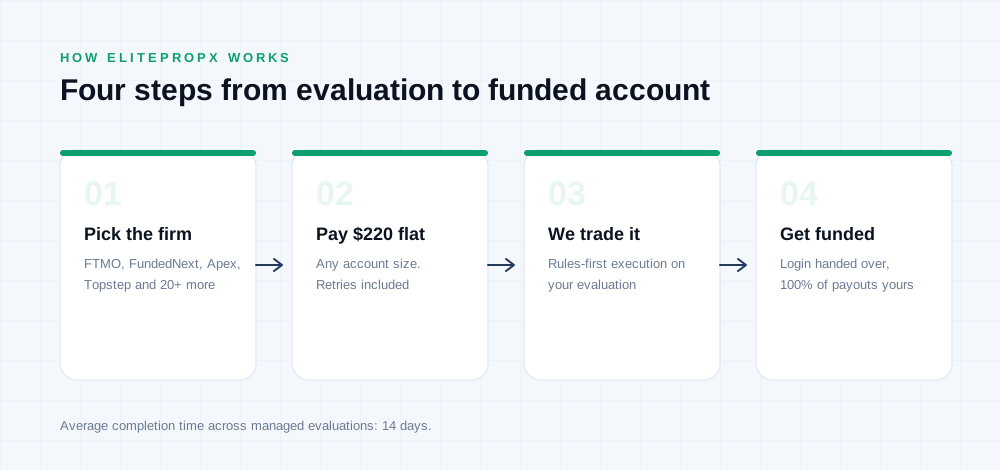
Strip the marketing away and a passing service sells two things at once. The first is labour: someone else sits through the evaluation sessions, applies a rule-aware trading plan, and produces the pass. The second is risk transfer: if the attempt fails, the provider absorbs the cost of the retry rather than the buyer paying for another evaluation.
Neither of those is a guarantee. The evaluation is still run by the prop firm, under the firm's rules, on the firm's platform, and the firm can void an account for a rule breach regardless of who placed the trades. A provider that promises a guaranteed funded account is either describing a different product — selling access to an account they already own — or is not being precise about the risks.
The scope of work is worth pinning down in writing before payment, because providers interpret it differently. The questions that matter are unglamorous:
- Which phases are covered? A single-phase evaluation and a two-phase evaluation are different jobs with different failure surfaces.
- What account sizes? Many providers scale their fee with the account, which means the largest account is not necessarily available at the advertised price.
- What happens at the funded stage? Some providers hand over the login and stop. Others trade the funded account for a share of payouts. The second is a materially different commercial relationship, and on some firms it is explicitly prohibited.
- Who pays the firm? The evaluation fee is normally the buyer's. Confirm that, because a provider who "includes" the fee is really marking it up.
- What is the failure policy? Retry at no cost, retry at a discount, or no retry — this is the term that decides whether the price is good value.
A provider that answers all five without hedging is a provider that has thought about the job. One that answers in slogans has not, and the gap will show up at the worst possible moment: when an account fails and the buyer discovers the retry policy was never as broad as the sales page implied.
There is a more fundamental question underneath all of this, and it is the one the industry prefers not to raise. If a provider can pass any evaluation reliably, the economics of doing so for $220 are strange — the same skill applied to a funded account would earn far more without the compliance risk. The honest resolution is that the service is a volume business with modest margins, and that most providers are trading a specific style of plan rather than possessing an edge that prints money. That does not make the service worthless; it makes it a labour purchase rather than an investment in superior skill. Buyers who understand that price the service correctly and are rarely disappointed.
The four pricing models
Once you start collecting quotes, patterns appear quickly. There are four shapes in the market, and each one encodes a different assumption about where the provider expects to make its money.
| Model | How it is charged | What it implies | Where it bites |
|---|---|---|---|
| Percentage of account | A share of the funded balance, typically payable on success | Provider expects to succeed and wants upside | Large accounts become expensive; small accounts are cheap but slow |
| Per phase | A fee for phase one, another for phase two | Provider prices the work, not the outcome | Failure in phase two means paying again |
| Retainer or subscription | Monthly fee for as long as the evaluation runs | Provider monetises time | Slow passes cost more; no cap on total spend |
| Flat fee | One price regardless of size or phases | Provider monetises volume and repeatability | Only viable if failures are rare and cheap to retry |
The percentage model is the most common and the most misunderstood. Because it is payable on success, it looks risk-free to the buyer — no pass, no fee. The catch is that the fee scales with the thing the buyer most wants, and on a large account the percentage can exceed the evaluation fee several times over. It also creates an incentive for the provider to prefer accounts it is confident about, which in practice means refusing the difficult firms and the difficult sizes. That is rational for the provider and frustrating for the buyer who came for exactly those.
The per-phase model is the most transparent and the least forgiving. The provider is paid for work performed, so a failure is the buyer's cost. Where the provider offers a discounted retry, this model becomes reasonable; where it does not, the buyer is financing the provider's variance.
The retainer is the model that hides the most. A monthly charge sounds modest next to a large percentage, but it has no ceiling. An evaluation that takes twelve weeks can easily cost more than a percentage-based quote on the same account, and the buyer has no way to cap the spend once they have started.
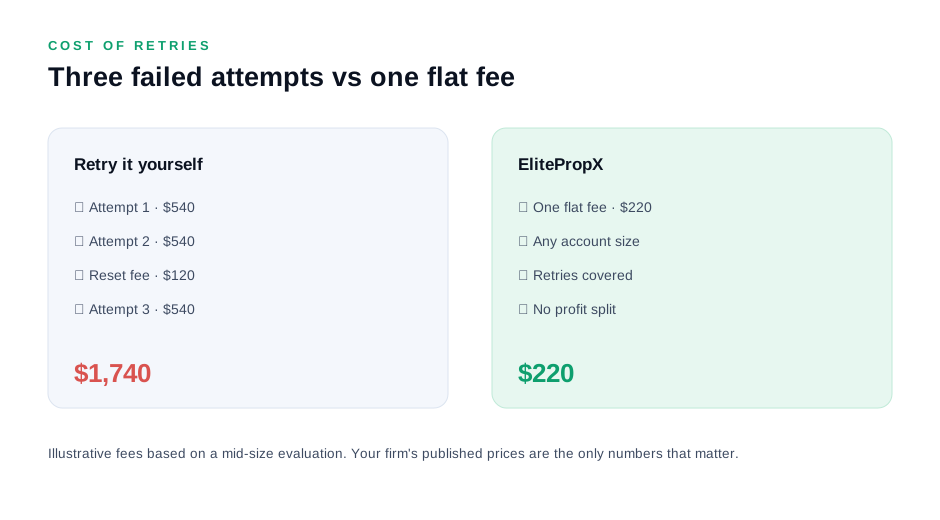
The flat fee is the least common, because it requires the provider to be confident in a repeatable process and to absorb the cost of its own failures. It is also the model buyers understand instantly: one price, any size, retries included. ElitePropX uses it at $220 for that reason — it makes the buyer's decision simple and puts the cost of a failed attempt on the party that controls the trading.
What each model incentivises
Price shapes behaviour, and the behaviour you should care about is what happens when the evaluation starts going badly. On a flat fee, a failed attempt is a pure cost to the provider, so the incentive is to trade conservatively enough to finish inside the rules. On a percentage, a failed attempt costs the provider only its time, and a pass on a large account is worth far more than a pass on a small one — which pushes the provider towards cherry-picking easy assignments.
The per-phase model aligns incentives reasonably well for phase one and poorly for phase two, because the second fee is small relative to the first and the second phase is where most evaluations die. A provider optimising for phase one revenue may take risks that make phase two fragile.
The retainer is the weakest alignment of the four. The provider is paid for elapsed time, so a fast pass is a short invoice. That is not an accusation — most providers in this category are honest and simply prefer predictable revenue — but a buyer should read the structure rather than the intentions.
One practical consequence follows for anyone comparing quotes. A percentage quote and a flat-fee quote are not comparable at face value, because they load risk in different places. Convert every quote into a single number: expected total cost across three attempts, including the firm's own evaluation fees and reset charges. That number is what the decision actually hinges on, and it is almost never the number on the sales page.
There is a second-order effect worth mentioning because it changes behaviour in the funded phase. Providers who take a share of payouts have an interest in the funded account performing, which sounds like alignment until you notice that the buyer may prefer a cautious funded account and the provider may prefer an aggressive one. Flat-fee providers have no position in the funded account at all, which is cleaner, provided the buyer is equipped to run it. That trade-off is set out in the propfirm passing service pricing models and in the payout process walkthrough.
The firm-terms problem
This is the section that decides whether the purchase is sensible, and it is the section most buyers skip. Proprietary trading firms write their own terms, and those terms govern whether someone else may trade the evaluation.
Three positions exist in the market. Some firms prohibit third-party trading explicitly, with account closure and forfeiture as the stated remedy. Some firms are silent on the question, which is not permission — it is an unresolved ambiguity that a firm can resolve against the trader later. A smaller number of firms permit it, sometimes with conditions such as disclosure or a limit on shared access.
The consequences are asymmetric. If a firm voids a funded account after a payout request, the buyer loses the account and anything owed on it, and has no recourse against the firm because the firm's terms were clear. A provider cannot indemnify that risk, because the relationship it breached is between the trader and the firm. The buyer carries it either way.
That is why the terms check belongs before payment, not after. The practical process is short: open the firm's terms of service, search for "third party", "authorised user", "account sharing" and "proxy", and read the surrounding paragraph rather than the heading. Where the answer is unclear, email the firm's support and keep the reply. It is not a guarantee, but a written answer is better than an inference.
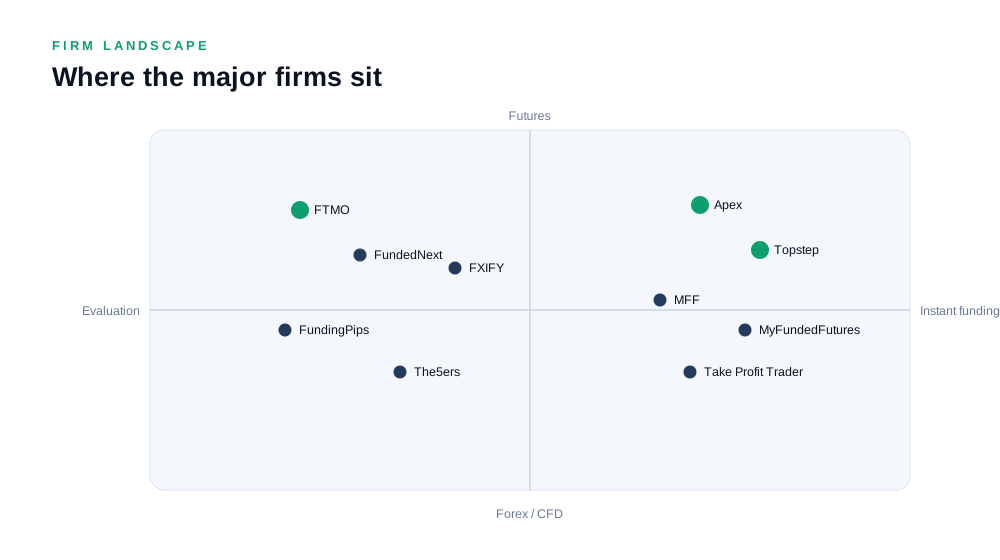
Five of the firms most often put through a service have their rule sets laid out at the account sizes on sale — FTMO, FundedNext, The5ers, Apex and Topstep — and each of those pages names the clause to search for before an account is handed to anyone, so the terms check above can be done in ten minutes rather than an evening.
A provider worth using will raise this itself and put the firm’s position in writing before payment. That disclosure is a useful signal: it means the provider has read the terms and understands the downside. ElitePropX states the position on every service page and tells the client in writing what the firm’s clause says and who carries the enforcement risk.
There is a second terms issue that nobody advertises, and it concerns the funded account rather than the evaluation. Several firms allow a trader to use assistance during an evaluation but require the funded account to be traded by the account holder personally, on the reasoning that payouts are the firm's real exposure. A buyer who has read the evaluation clause and stopped there has read half the contract. The question to ask support, in writing, is not "can someone trade the evaluation" but "who may trade the funded account after it is issued". The answers differ more often than the marketing implies, and the funded clause is the one with money attached.
There is a related trap that catches buyers who do check. Some firms permit third-party trading on the evaluation but prohibit it on the funded account, or vice versa. A provider covering only the evaluation has not solved the second problem, and the buyer inherits it at the moment of maximum value. Read the clause twice, once for each stage. The wider legitimacy test — lawful, permitted, honestly delivered — is worked through in the three-test legitimacy check.
What "retries covered" is worth
Pricing a retry is the clearest way to compare providers, because the retry is the event the buyer is actually buying insurance against. An evaluation that passes first time makes every provider look identical; an evaluation that fails twice separates them completely.
Start with the arithmetic of the firm's side. A failed evaluation must be replaced, and most firms charge a reset or a new purchase fee. That cost is the buyer's regardless of provider. What the provider can cover is the service fee for the next attempt — the labour — and that is the part worth comparing.
Three policies exist. The strongest is unlimited retries on the same firm and account size at no additional service fee. The middle is a discounted retry, usually a fraction of the original price. The weakest is a new full fee, which is simply another purchase.
Read the qualifying conditions even on the strongest policy. "Same firm and account size" excludes switching firms, which is exactly what a buyer wants to do after a strategical mismatch. "Same strategy" can exclude the buyer from a retry if the provider decides the plan was the problem. "Subject to availability" is a soft cap disguised as a promise. None of these is unreasonable; all of them narrow the headline.
Then value it honestly. A retry is worth the price of the alternative, which is a fresh service fee, multiplied by the probability of needing one. For a provider with a genuine completion rate near the top of the market, that is a small expected value. For a provider whose advertised rate is aspirational, the retry cover is the entire product. Which is why the number that matters is not the success rate on the page but the failure policy in the contract.
Reading proof properly
Every provider shows passes. The question is whether the evidence establishes what it claims, and most of it does not.
A screenshot of a balance is close to worthless: it shows a number, not an account, not a firm, not a date, and not whether the account was funded or evaluated. A screenshot of a firm's dashboard is better, because the interface identifies the firm and usually the account status. A third-party verified track record — a public myfxbook or similar linked account — is better again, because the history is timestamped and the equity curve cannot be edited after the fact.
Even a verified track record has limits worth understanding. A verified account proves that trading happened, not that it happened on a prop firm evaluation, and not that the same plan can be repeated on a firm with different rules. It also shows drawdown, which is the part providers rarely discuss and the part that decides whether the plan survives a trailing threshold. Read the maximum drawdown before the return.
The test that separates the serious from the theatrical is simple: ask for a pass on the exact firm and account size you are buying, dated within the last month, with the firm's own dashboard visible. A provider that can produce it is operating at volume. A provider that deflects to a general track record is telling you something useful about its coverage.
Reviews deserve the same scepticism and a different technique. Look for reviews that describe a failure, because the failure handling is the only part of the service a happy customer cannot evaluate. A wall of five-star reviews with no negative detail and no dates is a marketing asset, not a customer record. Ask a provider for its last failed attempt and how it was handled before you ask for its winning run. The service review works through what a published review actually establishes, and which parts of a provider's record it leaves unexplained.
What you should never hand over
The commercial relationship requires access to a trading account. It does not require access to your identity.
Never hand over the email address registered to your prop firm account unless the provider needs it for the platform login, and never hand over the password for that mailbox. Never provide identity documents, bank statements or payment-method details for KYC — those are between you and the firm, and a provider asking for them is either confused about the process or building a profile it does not need.
What a legitimate provider needs is narrow: the firm name, the account size and phase, the platform credentials for the evaluation account, and a way to reach you. Some providers ask for the platform investor password rather than the master password, which is a reasonable precaution on platforms that support it. On platforms that do not, the master password is unavoidable during the evaluation and should be changed the moment the login is returned.
Two habits reduce the residual risk. Use a unique password for the trading account, not one reused elsewhere. And screenshot the account settings before handing anything over, so that a later dispute about what was changed has a baseline. Both take a minute and neither is standard practice in this category, which is precisely why they are worth adopting.
Seven tests that separate real from not
None of these is decisive alone. Together they produce a clear picture quickly.
- They raise the terms issue before you do. A provider that never mentions the firm's position on third-party trading has either not read the terms or is hoping you will not.
- They quote one price. Providers that add a platform fee, a management fee or a success fee on top of the headline number are pricing in stages to make the first number look small.
- They describe the failure case without being asked. What happens on a breach, who pays the reset, how long a retry takes — a provider with a process answers immediately.
- They refuse some firms. A provider that will take any firm is not screening; it is selling. Screening is the expensive part of the service.
- They have a completion time, not a completion guarantee. "Fourteen days on average" is a measurement. "Funded in seven days guaranteed" is a sales script.
- They do not ask for your email password or KYC documents. The account credentials are the job. Everything else is overreach.
- They publish a business identity. A domain, an email address and a payment processor that resolves to a real merchant account. Anonymous providers are not automatically fraudulent, but a buyer has no remedy against one.
Two failures against that list is a warning; four is a decision. The category attracts operators who disappear after a bad month, and the tests above are mostly tests of whether the provider expects to be around next quarter.
When a service is the wrong purchase
A passing service is a labour and risk-transfer product, and it is the wrong product in several common situations.
It is wrong if your reason for buying is to learn. The evaluation is the cheapest trading education available — a defined risk, a defined target, and a clear verdict on whether the plan survives rules. Outsourcing it removes the feedback loop and leaves the funded account in the hands of someone who has never traded under those rules.
It is wrong if the funded account is the point. A trader who cannot run the funded account has bought a login, not an income. The funded stage has its own rules — minimum days, consistency checks, payout schedules — and the failure rate there is high precisely among traders who did not do the evaluation themselves.
It is wrong where the firm prohibits it, obviously, and it is wrong where the economics do not work. If the evaluation fee is small relative to the service fee, and the trader has a plan that passes most of the time, the service is expensive insurance against a loss that is already affordable.
It is right in a narrower set of cases: the trader has a funded-account plan but no time to execute an evaluation; the firm requires a pace of trading that does not fit a day job; the trader has failed the same rule repeatedly and wants the evaluation cleared while they work on the behaviour. Those are rational purchases. "I want to be funded" is not, on its own, a reason to buy labour.
What you are not buying
Clarity about the exclusions is half of a good purchase. Four things are almost never included, and a buyer who assumes otherwise will be disappointed at the worst moment.
You are not buying the firm's fee. The evaluation, the reset and any platform charges belong to the firm. A provider quoting a single all-in figure is either bundling the firm's charge into its own price or being vague about who pays what. Ask for the split explicitly.
You are not buying the funded account's performance. The login is handed over and the account is the trader's from that point. A provider that continues to trade it is selling a different product — a profit-share arrangement — which is usually prohibited and always a different risk profile.
You are not buying a guarantee against a rule breach. If the firm decides a trade breached its terms — a news window, a position cap, a hedging clause — the account can be voided regardless of the provider's intentions. Good providers trade defensively around those rules, but no provider can underwrite the firm's discretion.
You are not buying anonymity from the firm. The account is opened in the trader's name, verified with the trader's documents, and paid to the trader's payment method. Any arrangement that asks the trader to hide the relationship from the firm is both a terms risk and a sign that the provider knows it.
Those four exclusions explain most of the complaints in this category. They are also easy to state up front, which is why a provider that states them is worth more than one that leaves them to be discovered.
A checklist before you pay
Ten items, all answerable in under an hour, and all worth more than another review thread.
- I have read the firm's terms on third-party trading, for both the evaluation and the funded account.
- I have the provider's answer in writing on that specific firm.
- I know the total price, including the firm's fee, and whether a retry costs anything.
- I know which phases and which account sizes the price covers.
- I know what the provider does at the funded stage, and whether it takes a share of payouts.
- I have seen a pass on my firm and size, dated recently, on the firm's own dashboard.
- I know the expected completion time and what happens if it slips.
- I have a unique password on the trading account and a screenshot of its settings.
- I have not been asked for identity documents, bank details or mailbox access.
- I have compared this quote to the alternative — trading it myself — using expected total cost.
That list is deliberately unexciting. The category's problems are rarely exotic; they are the ordinary ones — an unread clause, an unpriced retry, a provider that stops answering. A buyer who works through ten boring questions is already in the top decile of customers this industry serves.
Frequently asked questions
How much should a propfirm passing service cost?
There is no single market price. Percentage-of-account providers can charge several hundred dollars on a large evaluation, per-phase providers charge per stage, and flat-fee providers like ElitePropX charge $220 regardless of size. The number that matters is the expected total across attempts, including the firm's own fees and resets.
Do prop firms allow passing services?
It depends on the firm and it is written in the terms, not the marketing. Some prohibit third-party trading with account closure as the remedy, some are silent, and a few permit it with conditions. Silence is not permission — ask the firm's support and keep the reply.
What happens if the evaluation fails?
On the $220 flat fee, a retry on the same firm and account size carries no additional service fee; the firm's own reset charge is separate and paid to the firm. Check any provider's retry policy for qualifying conditions such as switching firms or changing strategy, because those narrow the cover considerably.
Can the provider take my payout?
No. The funded account is opened in the trader's name and payouts are paid to the trader's own verified payment method. A provider that asks to receive payouts on your behalf — or asks for bank details to "process" them — is describing something the firms do not do.
How long does a pass take through a service?
Around two weeks on average across managed evaluations, with two-phase forex evaluations usually taking longer than single-phase ones and futures evaluations bounded below by a minimum session count. Be sceptical of any promise expressed as a guarantee rather than an average.
How do I verify a provider's claimed success rate?
You cannot verify a rate directly; you can verify individual passes. Ask for a recent pass on your specific firm and size, shown on the firm's dashboard with a visible date, and look at a third-party verified track record for drawdown rather than for return. A provider that cannot produce a specific example is quoting a number it does not measure.
Is a flat fee suspiciously cheap?
It is unusual rather than suspicious. Flat fees are viable for providers running a repeatable plan at volume, and they are unattractive to providers who prefer pricing on upside. What deserves scrutiny is not the price but the coverage: which firms, which phases, which sizes, and what happens on a failure.
Should I buy the evaluation or the funded account?
Buy the evaluation. A service that sells a ready-funded account is either reselling an account it already passed, which may breach the firm's transfer rules, or describing a profit-share arrangement on an account you do not control. The evaluation is the clean, documented product.
What proof should I ask for before paying?
A dated pass on your exact firm and account size, visible on the firm's own dashboard. Add a third-party verified track record if one exists, and read its maximum drawdown before its return. Screenshots of a balance chart prove nothing on their own.
What information does the provider need from me?
The firm name, account size and phase, the platform credentials for the evaluation account, and a way to contact you. Nothing else. Identity documents, bank details and mailbox access are outside the scope of the job and should be refused.
Can I use a service and then trade the funded account myself?
Yes, and that is the standard arrangement on a flat-fee model: the login is handed over and the funded account is entirely the trader's. It is also the harder half of the job — the funded rules on minimum days, consistency and payout schedules are covered in the payout guide.
What is the biggest mistake buyers make?
Buying before reading the firm's terms. Every other risk in the category is priced and disclosed; the terms risk is neither. A funded account removed for third-party trading is the one outcome that costs the buyer everything and is entirely avoidable with ten minutes of reading.
One flat $220, any firm, any size
ElitePropX trades your evaluation and hands back a funded login in your name. Retries covered, no profit split. If your firm's terms forbid third-party trading we say so before you pay.
Related reading
- The prop firm passing EA, tested free on a demo first
- How our flat-fee propfirm passing service works
- FTMO challenge passing service
- Prop firm scams to avoid
- Complete challenge passing guide
- Best prop firms for beginners
- Full prop firm comparison
- Verified passing track record
- Frequently asked questions
- How to Pass Prop Firm Challenge without Trading
- Apex Trader Funding passing service review
- Topstep Combine review
ElitePropX is an independent service and is not affiliated with, endorsed by or sponsored by any proprietary trading firm. Service terms, retry policies and firm rules change; verify them before purchasing. Nothing here is financial advice.