
Firm guide · reviewed October 2026
FTMO challenge passing: the complete guide
FTMO runs two phases — the Challenge and the Verification — each with its own target, loss limits and minimum trading days. This guide covers exactly how to pass both, where attempts actually fail, and the pacing arithmetic that gets an account funded.
Key takeaways
- The 5% daily loss limit is measured on equity including floating positions, which makes it the strictest rule on the account.
- The 10% maximum loss is static — the failure level is $90,000 on a $100,000 account and never moves.
- Phase 1 targets 10%, phase 2 targets 5%, with a four-day minimum on each.
- No overall time limit and no consistency rule at evaluation: the structure rewards patience over speed.
Contents
FTMO's rules, laid out plainly
FTMO is the reference structure in prop trading, and its rulebook is unusually well documented. Stripped of narrative, the numbers that matter are these.
| Parameter | Challenge (phase 1) | Verification (phase 2) |
|---|---|---|
| Profit target | 10% | 5% |
| Daily loss limit | 5% of initial balance | 5% of initial balance |
| Daily loss basis | Equity, including floating losses | Equity, including floating losses |
| Maximum loss | 10% — static | 10% — static |
| Minimum trading days | 4 | 4 |
| Time limit | None | None |
| Consistency rule | None at evaluation | None at evaluation |
Two features are worth isolating because they explain most of FTMO's reputation for being difficult and fair at the same time.
The first is the static maximum loss. Because the failure floor does not trail, profit genuinely increases the distance between the account and failure. Bank $4,000 on a $100,000 account and the floor is still $90,000; the cushion has grown from 10% to 14%. This is the most forgiving drawdown structure in common use, and it is why traders who can pass FTMO reliably often cannot pass a trailing futures evaluation with the same headline numbers.
The second is the equity basis of the daily limit. The rule is measured on equity including floating positions, not on closed balance. An open trade that is $3,000 down consumes $3,000 of the daily budget even if it recovers by the close. Most traders read the 5% figure and picture a closed-P&L budget, which is why the daily limit ends more FTMO attempts than any other rule.
The 5% daily loss limit — measured on equity
On a $100,000 FTMO account, the daily loss limit is $5,000 of equity loss measured from the day's starting equity. That last phrase matters: the limit is recalculated each day against the equity at the start of that day, so a winning morning raises the level at which the day would be failed, and a losing morning lowers it.
Three practical consequences follow.
Floating losses count. A position showing −$4,000 of unrealised loss has already spent 80% of the day's $5,000 budget. Recovery does not refund that budget in real time — the risk desk measures equity as it stands — so a further $1,000 of adverse movement breaches the limit while the position is still open, regardless of where it closes. Traders who keep the position and add to it are the most common source of daily-limit failures at FTMO.
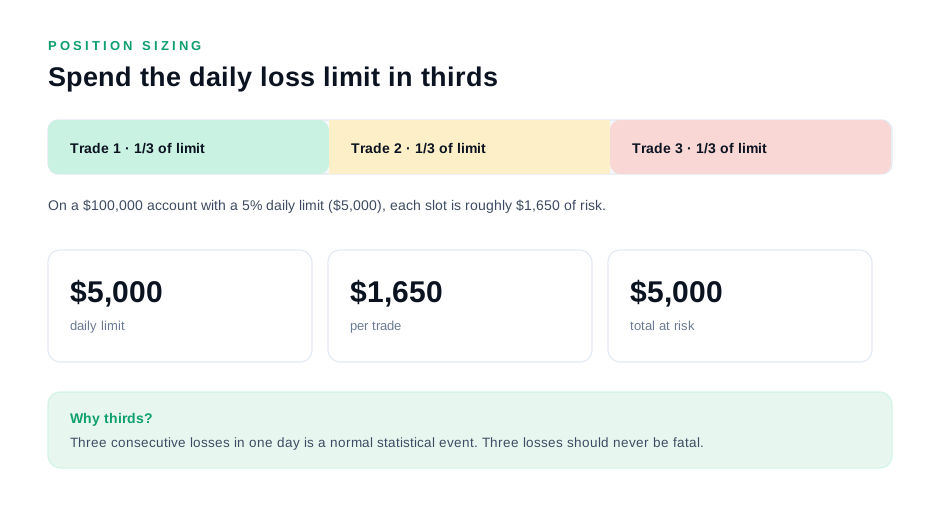
The limit is a day-level constraint, not a trade-level one. The right way to use it is to define a per-trade risk that leaves room for a normal sequence of losses. At a third of the daily budget, each trade risks $1,650 on a $100,000 account, and three consecutive losses cost $4,950 — uncomfortable but survivable. At half the budget, two losses end the day with different consequences.
The daily reset is not an invitation. Because the budget resets every morning, a losing day feels temporary. It is, but the loss itself is permanent: $4,900 lost on Monday is $4,900 of the $10,000 target that must be earned back, and it also reduces the cushion above the static floor. Two consecutive near-limit days leave an account at −9.8% with a 10% maximum loss, which is a far worse position than one −2% day.
The sizing rule that follows from this: maximum risk per trade is a third of the daily limit — $1,650 on a $100,000 FTMO account — and trading stops when roughly 80% of the daily budget has been realised or is currently floating against the position. The remaining 20% exists to absorb slippage on closing, not for another setup.
The 10% static maximum loss
The failure level is set 10% below the initial balance and never moves. On a $200,000 account it is $180,000; on a $50,000 account it is $45,000. Because it is static, the arithmetic of an FTMO evaluation is simpler than on any trailing structure: the distance to failure is exactly the headroom created by profit, plus the 10% starting buffer.
It is worth being precise about what this does and does not give you. A static floor does not make the daily limit more forgiving — the 5% equity-based daily rule still applies every day. What it does is remove the second-order punishment that trailing structures impose: growth never reduces safety. That property is why a static account can be traded with constant risk per trade throughout the evaluation, whereas a trailing account requires risk to fall as profit accumulates.
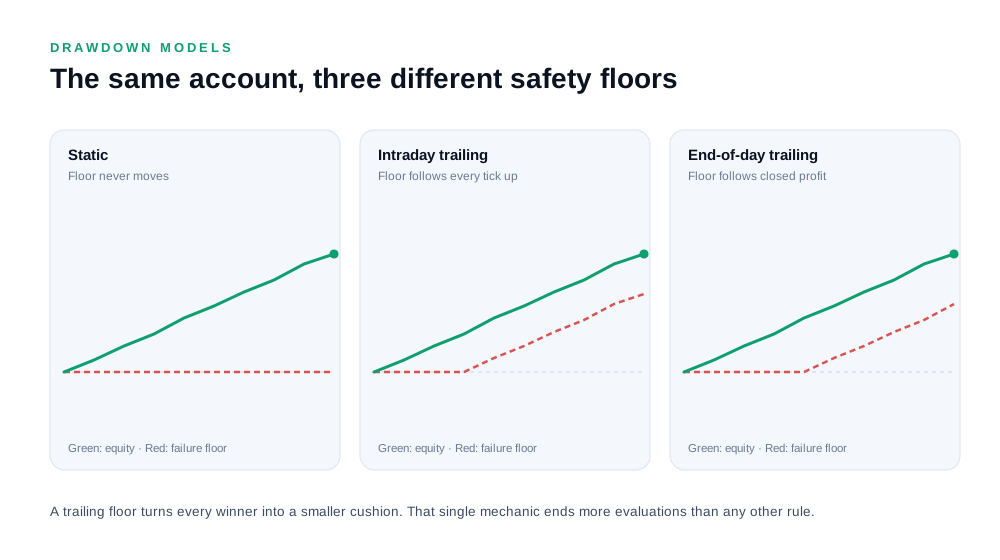
The practical implication for pacing is straightforward: on a static floor, profit is pure progress. There is no reason to reduce size as the target approaches, other than the variance argument that applies everywhere — and given the minimum-day requirement, finishing early creates the exposure problem described below rather than an advantage.
Phase 1 and Phase 2
FTMO's two phases have different targets and identical limits, and the second one is psychologically harder despite being smaller.
Phase 1: 10% in an unlimited window. With no time limit and a four-day minimum, the sane pace is sixteen to twenty trading days at a third of the daily budget per trade. Nothing about the structure rewards speed, and a fast pass creates a specific problem: once the target is reached before the minimum day count, the remaining sessions must be traded at target-level equity. Most plans handle this by pacing the target to arrive on or after the minimum day rather than before it.
Phase 2: 5% with the same limits. A smaller target looks like relief. It is not, for three reasons. First, the target is smaller but so is the margin for a mistake: an account that has already passed phase 1 has more to lose than one that has not started. Second, the temptation to close the gap quickly is strongest when the target is close, and one oversized attempt can consume 40% of the daily budget. Third, the discipline that got a trader through phase 1 is often relaxed in phase 2 because the finish line feels immediate.
Our own approach is to reduce risk per trade by a quarter for phase 2 and to spread the smaller target across a similar number of sessions rather than fewer. The reduction costs a few days and removes the largest single risk to an otherwise completed evaluation.
The full breakdown of the payment and verification side — including what FTMO issues after a pass — is covered in the passed challenges section, and the structural comparison against firms with trailing floors is in the 2026 comparison.
The risk plan for an FTMO account
Four numbers define the plan, and all four come from the rulebook rather than from a market view.
- Maximum risk per trade: a third of the daily limit — $1,650 on $100,000, $825 on $50,000, $3,300 on $200,000.
- Maximum positions at once: two. Correlated positions count as one for sizing purposes, because FTMO measures equity across the account rather than per instrument.
- Daily stop: stop opening new positions once 80% of the daily budget is realised or floating.
- Profit per session target: 0.5% to 1.2% of account balance, which paces a 10% target across sixteen to twenty sessions.
Two additional rules come from FTMO's terms rather than from arithmetic. Restricted instruments must be respected — FTMO publishes a permitted list and it is enforced — and positions are not held through major scheduled news events where the firm's rules restrict trading. Both are covered in the rules matrix alongside the rest of the firm's constraints.
Pacing a 16–20 day pass
The pace that produces reliable FTMO passes is deliberately unremarkable. Spread over twenty sessions with a 0.75% average daily gain, the 10% target requires roughly thirteen profitable sessions and seven flat or losing ones. That distribution is achievable without a single exceptional day, which is the point.
Sessions 1–4: build the cushion. One or two setups per day at full planned size, no averaging into losers, and no trading in the first thirty minutes while spreads are wide. Target outcome: +2% to +3.5% of balance, or a small net loss with the daily budget lightly used. Both are acceptable because the objective is separation from the $90,000 floor, not progress.
Sessions 5–12: grind. This is where the evaluation is actually won. Risk per trade stays constant, the daily target stays between 0.5% and 1.2%, and any day that reaches 40% of the target is closed early rather than extended. Reaching +5% or +6% by session 12 puts the account in a position where the remaining work is a formality if discipline holds.
Sessions 13–20: protect the pass. Size comes down by a quarter, sessions shorten, and the final 4% is collected in increments. If the target is reached on session 16 and the four-day minimum is already satisfied, phase 1 is finished and verification begins. If the minimum day count is not satisfied, the remaining sessions are traded at minimum size rather than at normal size — the account is effectively at target and has nothing to gain from exposure.
A worked version of that sequence, session by session with realistic numbers, is in the ultimate guide.
Six ways FTMO attempts end
These are the failure modes we see most often, in order of frequency.
1. The recovery trade after a losing morning
A −$1,500 morning produces a position sized to win it back in one trade. That position risks 4% of the account, and a loss takes the day to −5.5%, past the limit. The rule did not fail the trader; the response to a small loss did.
2. Holding and adding to a floating loss
The equity basis of the daily limit means an open loser counts immediately. Adding to a position that is already $3,000 down is the fastest route to a breach that exists, and it is often rationalised as averaging into a good entry.
3. Trading a restricted instrument
FTMO publishes a permitted list, and trades outside it void the attempt regardless of outcome. This is occasionally a genuine misunderstanding and frequently a habit carried over from a personal account.
4. Sprinting through the final percent
At +9.2% the instinct is to add size and finish today. The last 0.8% is where oversized attempts do the most damage, because the account has the most to lose and the least to gain.
5. Waiting at target for the minimum day count
Reaching target on day two of a four-day minimum means two more days of trading an account that cannot improve its standing. Plans that pace the target to arrive on day four or later avoid the exposure entirely.
6. Relaxing during verification
Phase 2's smaller target creates a false sense of safety. The limits are identical, and the damage from a single oversized attempt is the same as in phase 1 — except that it now erases a completed first phase as well.
After the pass
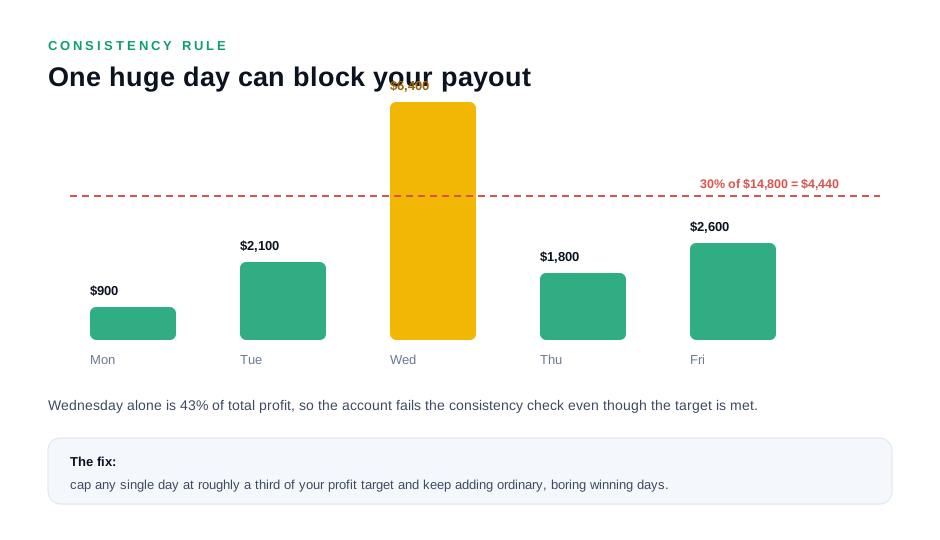
A passed FTMO verification produces a funded account with its own conditions. FTMO applies a minimum number of trading days before the first payout, a profit threshold and identity verification, and the first reward becomes available from day 14 after the first trade on the FTMO Account, then on demand after that. The 2-Step product has no consistency rule at either stage; the 50% consistency rule belongs to the 1-Step and Instant products.
The practical consequence is that a pass achieved with one dominant day is not finished. Adding ordinary winning days before requesting a withdrawal is the standard remedy, and it is easier to do when the evaluation itself was paced in small increments rather than in bursts. The payout process guide covers the sequence and the delays.
Compliance note: FTMO's terms on third-party trading are worth reading before purchasing any passing service, and they can change. If your firm's current terms prohibit it and the policy is enforced, an account can be voided after funding. ElitePropX will tell you in writing what it knows about the current position — and will name the risk plainly before you pay — but that risk remains the account holder’s.
Using FTMO's trial before you pay for anything
FTMO's structure makes it unusually easy to test a plan before committing money, and the trial is worth treating as a genuine rehearsal rather than a formality.
What the trial is good for. Verifying that a risk plan can be executed without touching the daily limit. That is not a market question — it is an operational one, and it is answerable in a week. A trader who completes ten trial sessions without a single day exceeding 40% of the daily budget has demonstrated the discipline the real evaluation requires. A trader who breaches the daily limit twice in ten trial sessions has learned something more useful than any preview of the live account could teach.
What it does not prove. That the strategy has an edge. Trial performance is short, unrepresentative, and often distorted in the opposite direction — traders take fewer risks when the money is not real, which slightly inflates discipline and slightly deflates returns. The trial answers the question "can I follow this plan?", not "is this plan profitable?".
How to structure it. Run it with the exact numbers you intend to use: the same per-trade risk as a percentage of balance, the same maximum position count, the same daily stop, the same session window and the same instrument list. If the trial runs at one size and the live evaluation at another, the trial proves nothing about the live attempt.
The pacing test. After ten sessions, log four numbers per day: closing equity, distance from the failure level, share of target completed and days used. If the target completion rate implies a total pass time inside twenty-five sessions, the plan is viable. If it implies forty sessions on a structure with a thirty-day limit, the plan is wrong — reduce risk per trade further or lower the daily profit expectation, because the arithmetic will not be rescued by a better week.
Useful side effect: the trial is also the cheapest way to test whether a passing service's reporting is real before paying it. A solution that provides daily logs on a trial account is likely to provide them on a live one.
FTMO compared to a trailing-drawdown firm
Traders who pass FTMO and then attempt an intraday trailing futures evaluation often discover that the second task is harder despite a smaller headline target. The difference is not the target; it is the behaviour of the failure level, and it changes the shape of the correct plan.
| Dimension | FTMO (static 10%) | Intraday trailing firm |
|---|---|---|
| Failure level | Fixed at −10% | Follows unrealised equity upward |
| Effect of profit | Increases the cushion | Reduces the cushion |
| Risk near the target | Can stay constant | Must be reduced |
| Typical pass pace | 16–20 sessions | Slower final third |
| Main failure mode | Daily limit breach | Drawdown on a retracement after a strong day |
The consequence for planning is the single most counter-intuitive rule in prop trading: on a trailing structure, profitability makes the account more dangerous, not less. A trader who is 60% of the way to target with a trailing floor is in a more fragile position than one at 20%, because the floor has risen and the remaining buffer is smaller. The correct response is to reduce size as progress increases — the exact opposite of the instinct to press an advantage.
On a static structure like FTMO's, that rule disappears. Risk per trade can stay constant from the first session to the last without the floor moving, and the only arguments for reducing size near the target are variance and the possibility of an avoidable mistake. That is why FTMO is the structure most often recommended as a first large evaluation, and why traders who pass it comfortably sometimes find trailing futures accounts unexpectedly difficult: the skill that carried them through — consistent size maintained to the end — is precisely the behaviour a trailing floor punishes.
Account sizes and how the numbers scale
FTMO's rules are percentages, so they scale exactly with the account, and that scaling has two practical effects that traders often miss.
The first is that the dollar value of a mistake grows linearly while the tolerance for it does not. A $50,000 account has a $2,500 daily limit and a $825 per-trade ceiling; a $200,000 account has a $10,000 limit and a $3,300 ceiling. In relative terms these are identical. In absolute terms, a single slip — one extra position, one position left open over a news release, one order entered twice by mistake — costs four times as much on the larger account, and the evaluation's outcome is exactly as binary in both cases.
The second is that commission and spread costs are also dollars, and they do not scale with the account. On a $50,000 account, $6 of round-turn cost per trade is a larger drag relative to the $2,500 daily budget than the same $6 on a $200,000 account with a $10,000 budget. In practice this makes small accounts slightly harder to pass than large ones at identical risk discipline, which is worth knowing before buying the cheapest available evaluation and expecting the same pass rate.
A third consideration is sequencing. Traders who intend to run several accounts are usually better off passing one, trading it into a first payout, and then adding a second, rather than running two evaluations simultaneously. Two accounts at once split attention and can produce correlated positions across accounts that firms treat as a single exposure. Sequential funding also means the first funded account is available sooner, which matters if the objective is income rather than collection.
Frequently asked about FTMO
How long does an FTMO challenge take to pass?
With pacing rather than sprinting, sixteen to twenty trading days for phase 1 and around nine to twelve for phase 2 — roughly four to six calendar weeks in total. There is no time limit, so the pace is set by the daily loss budget rather than by urgency.
Is the FTMO daily loss limit measured on balance or equity?
Equity, including floating losses. An open position that is $3,000 down in unrealised terms has consumed $3,000 of the day's $5,000 budget on a $100,000 account, even if it later recovers.
Does the FTMO maximum loss trail?
No. The 10% maximum loss is static, so the failure level stays at $90,000 on a $100,000 account regardless of profit. This is the most forgiving common drawdown structure.
What is the minimum number of trading days?
Four on each phase. Reaching the target earlier does not complete the evaluation, which is why plans pace the target to arrive on or after the fourth day.
Does FTMO have a consistency rule?
The 2-Step FTMO Challenge has none, at evaluation or at payout. The 1-Step product applies a 50% consistency rule, and the Instant product applies a consistency limit of its own. Check which product the account belongs to before assuming.
What risk per trade should I use?
A third of the daily limit at most: $1,650 per trade on $100,000, $3,300 on $200,000, $825 on $50,000. Three consecutive losses at that size leave the account alive and the evaluation on track.
Can I pass FTMO with a passing service?
ElitePropX passes FTMO evaluations for a flat $220, with retries covered and no profit split, subject to the compliance check described above. Clients should satisfy themselves about FTMO's current terms before purchasing.
What happens if I fail an FTMO challenge?
FTMO's reset and purchase options apply, and the cost of a new attempt is charged by FTMO. With a passing service, a reset on the same firm and size carries no additional service fee.
Swing accounts: what actually changes
FTMO's swing account is the normal challenge with the weekend restriction removed, and it is usually a small additional fee. That sounds like a straightforward upgrade, and for some traders it is — but the change is not neutral, because holding positions overnight changes the risk profile in ways the rulebook does not spell out.
The rule change itself is simple: swing accounts may hold positions over the weekend, normal accounts must be flat before the close. Everything else — the 5% daily loss, the 10% maximum loss, the phase targets, the four-day minimum — is unchanged. What changes is the distribution of outcomes. A gap through the weekend is a loss that arrives without a session to manage it, and because the daily limit is measured on equity, a Sunday gap counts against Monday's budget in full from the first tick.
| Consideration | Normal account | Swing account |
|---|---|---|
| Weekend holding | Not permitted | Permitted |
| Gap risk | Removed by closing Friday | Carried, and counted on equity |
| Typical use case | Intraday strategies | Multi-day setups and position trades |
| Session management | Must plan an exit by Friday | Must plan size for a gap |
When swing is the right choice
Swing is right when the strategy genuinely requires multi-day exposure — a position built around a weekly range, or a trade that needs two or three sessions to develop. In that case the normal account forces a compromise that damages the edge, and the extra fee is buying the ability to trade the plan as designed.
It is the wrong choice when the only reason for wanting it is a reluctance to close a losing position on a Friday. That is not a strategy requirement; it is a hope that the weekend fixes something the week did not. Traders who take swing for that reason tend to discover the difference between a stop and a gap within the first month.
Sizing for a gap
On a swing account, position size has to be set against the worst plausible gap rather than the stop distance. A practical rule is to halve normal size for any position carried over a weekend and to avoid carrying positions into scheduled central bank decisions entirely. The cost is a slower path to target; the benefit is that a Sunday gap costs a fraction of the daily budget instead of all of it.
Resets, retries and the true cost of a second attempt
The fee for a challenge is not the cost of an attempt; it is the cost of the first attempt. The expected cost includes however many attempts are needed, and that arithmetic is rarely done before the first purchase — which is why traders under-estimate the value of passing slowly on the first try.
At a 40% pass probability, the expected number of attempts is 2.5, so a $540 challenge has an expected cost of roughly $1,350 before any resets are counted. Raising the probability to 65% by halving risk per trade drops the expected cost to about $830 and, more importantly, drops the expected elapsed time — because a failed attempt costs weeks as well as money, and weeks are the scarce resource when a trader is trying to build a track record.
Free retries and discounted resets change this arithmetic, and it is worth checking exactly what a firm offers on the account size you are buying rather than assuming the promotional wording applies. The distinction that matters is between a retry granted automatically after a failure and a reset purchased at a discount: the first shifts the arithmetic meaningfully, the second less so. Either way, the planning conclusion is unchanged — an attempt that fails on a rule breach has failed on something that was knowable in advance.
What a reset does not reset
A new attempt resets the balance. It does not reset the behaviour that ended the previous one unless the trader decides to change it, and the most common pattern in this market is a series of attempts that fail in the same way at different account sizes. Before buying a reset, write down the single rule that was broken and the specific change that prevents it. If the answer is "be more careful", the reset is a purchase of the same outcome at a slightly higher price.
One asymmetry is worth knowing: the fee for a second attempt is usually lower than the first, but the elapsed time is not. Two attempts at three weeks each is six weeks of a trader's life spent on the same puzzle, and if the second attempt fails for the same reason as the first, the cost is not the fee — it is the evidence that the process was never changed.
There is one further item to check before a reset: whether the firm's rules have changed since the failed attempt. Firms revise terms, and a reset bought on the assumption that the old rulebook still applies can start a challenge that is harder than the one just failed. Reading the objectives page again takes two minutes and occasionally saves an entire attempt.
Finally, decide before the reset whether the account size should change. Moving down a size is not an admission of defeat; it is the cheapest way to buy margin, because every percentage rule becomes a smaller dollar figure while the target stays proportionally identical. Traders who reset at the same size after a loss-limit failure are usually buying the same experience twice, and the second time it costs more to learn the same lesson.
One habit makes that decision easier: log the reason for the previous failure at the top of the new attempt's plan and date it. It takes a sentence, and it converts a reset from a fresh start into a continuation — the same folder, the same rules, the same trader, one fewer mistake available to repeat.
None of this makes a reset cheap, and none of it should. It makes the second attempt an experiment with one variable changed rather than a rerun of the first, and that distinction is the difference between a trader who eventually funds an account and one who collects challenge receipts.
Where these rules come from
Firm figures on this page are read from the rulebooks below rather than from other comparison sites. Every link was opened and checked on . Firms revise targets and drawdown rules without notice, so confirm the figures on the plan you are buying before paying. How we check firm rules sets out what a checked date means, what we publish when a figure cannot be confirmed, and how corrections are handled.
Want the FTMO evaluation traded for you?
Related reading
- Have the FTMO challenge traded for a flat $220
- How to pass an FTMO challenge, step by step
- FTMO vs The5ers compared
- How the flat-fee propfirm passing service works
- Daily drawdown explained
- The consistency rule, worked out
- From funded account to first payout
- Profit and payout calculator
- Prop firm comparison 2026
FTMO is named for identification only. ElitePropX is an independent service and is not affiliated with, endorsed by or sponsored by FTMO. Targets, loss limits and payout conditions change; verify them against the firm's current terms. Trading involves substantial risk of loss.