
Post-pass guide · reviewed October 2026
What happens after you pass a prop firm challenge
A pass is not a promotion. It is a change of contract: a new agreement, a different drawdown, new payout conditions, and a set of administrative steps that run on their own clock. Most traders prepare for the evaluation and improvise the funded month, which is why newly funded accounts are lost faster than evaluation accounts ever were. This guide covers what actually arrives, which rules get tighter, and how to trade the first thirty days.
Key takeaways
- A pass triggers a new agreement with its own drawdown, payout conditions and conduct clauses — reread it before the first funded trade.
- The funded drawdown is usually tighter as a percentage than the evaluation's, so the correct first move is to halve the risk.
- Verification is administrative and can be completed in week one; leaving it until the payout request is the most common avoidable delay.
- Profit is not income until it is withdrawn, and on a trailing structure an unwithdrawn balance makes the account more fragile.
- The first payout cycle matters more than the first payout amount: it establishes the route, the timing and the conditions for every cycle after it.
Contents
- The pass is a new contract
- What actually arrives, and when
- Which rules get tighter
- Week one: paperwork and calibration
- Week two: the first real trades
- Recalibrating the risk line
- The minimum-day and consistency clock
- Problems that look like payout problems
- Completing the first cycle
- When to stop trading the allocation
- The psychology of the first funded month
- A thirty-day post-pass checklist
- Frequently asked questions
The pass is a new contract
During an evaluation, the trader's relationship with the firm is simple: a fee has been paid and a target has to be met. On funding, that relationship becomes a commercial arrangement with ongoing conditions, a revenue split and a set of conduct clauses that apply to every trade.
The practical difference is that evaluation rules are designed to test a strategy, while funded rules are designed to protect the firm's capital. Those two objectives produce different numbers. A firm can be generous about a target because a failed evaluation costs the trader a fee; it cannot be generous about the funded drawdown, because a funded breach costs the firm money.
That asymmetry explains almost every surprise in the first funded month. The drawdown is tighter, the daily limit may be calculated differently, the consistency condition applies to profit that is being withdrawn rather than to a target, and the conduct clauses — news, overnight holding, permitted instruments — are enforced rather than observed.
So the first action after a pass is not to trade. It is to read the funded agreement as a document, with a pen, and to write down five numbers: the funded maximum loss, the funded daily limit, the minimum profitable days, the profit threshold before withdrawal, and the consistency condition. Those five numbers define the account that will actually be traded, and none of them can be inferred from the evaluation's rules.
If any of the five is unclear, ask support in writing before the first trade. A written answer is the only version of the terms that can be relied on later, and the cost of asking is a day.
What actually arrives, and when
The sequence after a pass is administrative and reasonably consistent across firms, though the timing varies. Knowing the order prevents the most common mistake, which is treating a pending step as a completed one.
| Step | What it is | What it requires from the trader |
|---|---|---|
| Pass confirmation | Notice that the target and rules were satisfied | Nothing, but check the day count and consistency position |
| Funded agreement | A new contract with new limits | Read it; the drawdown and payout terms are not the evaluation's |
| Account credentials | New login, sometimes a new platform server | Confirm the platform, feed and server time before trading |
| Identity verification | Documents and address confirmation | Submit immediately, not at the first withdrawal |
| Payment details | Withdrawal method and account | Set up and verify in advance; mismatches cause delays |
| First payout request | Available after the conditions are met | Check day count, threshold and consistency before requesting |
The step that most often goes wrong is the credentials. A funded account is frequently on a different platform server or a different data feed from the evaluation, and the difference changes the spread, the fill quality and the timestamp on every trade. A trader who assumes the environment is identical calibrates against the wrong numbers for the first week.
The second most common problem is verification timing. Identity and address checks have nothing to do with the trading record, and they are frequently the reason a first payout takes longer than expected. Submitting them on the day the funded login arrives removes the only part of the chain that cannot be fixed later.
The third is a version problem. Firms revise agreements, and a trader who saved the evaluation terms may be holding a document that no longer governs the funded account. Save the funded version in force on the day it was accepted, including any email confirming a specific clause. It is the only reliable reference if a payout question arises three months later.
Which rules get tighter
Four conditions typically change between evaluation and funding, and every one of them changes in the direction of less room.
The drawdown. Usually tighter as a percentage of balance on the funded side, because the firm is now carrying real risk. The mechanism may also change — a structure that trailed during the evaluation may be static on funding, or the reverse. Both directions exist, and the only way to know is to read the funded terms rather than assume continuity.
The daily limit. Often similar in percentage but measured from a different reference point: balance rather than equity, or the day's opening balance rather than the previous close. A small change in the reference point is a large change in behaviour for a trader who holds positions through the session.
The consistency condition. Almost always more prominent on the funded side, because it governs what can be withdrawn rather than what can be earned. A rule that was a formality during the evaluation becomes a hard constraint on daily profit once a payout depends on it.
The conduct clauses. News windows, overnight and weekend holding, permitted instruments and any prohibition on third-party trading are enforced on the funded account in a way they rarely are during an evaluation. A trader whose evaluation contained a small breach that went unnoticed should not assume the same tolerance applies now.
There is a fifth change that is not a rule at all: the absence of a reset. An evaluation that is breached can be bought again. A funded allocation that is breached is usually gone, and with it the record that would have supported a scaling request. That asymmetry, more than any individual clause, is why the first funded month should be traded more conservatively than the evaluation was.
Week one: paperwork and calibration
The first week has two jobs, and neither of them is making money.
The first is administrative: submit verification, confirm the payment method, save the agreement, and confirm the platform server time and the exact hour at which the trading day begins. Each takes minutes and each is capable of delaying a payout by weeks if neglected.
The second is calibration on the funded account. Trade at a quarter to a half of the evaluation's risk for the first five sessions and measure the same three things measured during the evaluation: planned risk, realised risk including spread and commission, and time in the trade. The funded environment may be a different server, a different feed or a different commission schedule, and those differences compound over a month.
Week one is also the right time to establish the funded risk line in writing. It has the same four components as the evaluation's — risk per trade, trades per session, maximum daily loss, and the stop rule — but every number is smaller. A line carried over unchanged from the evaluation is a line written for a different account.
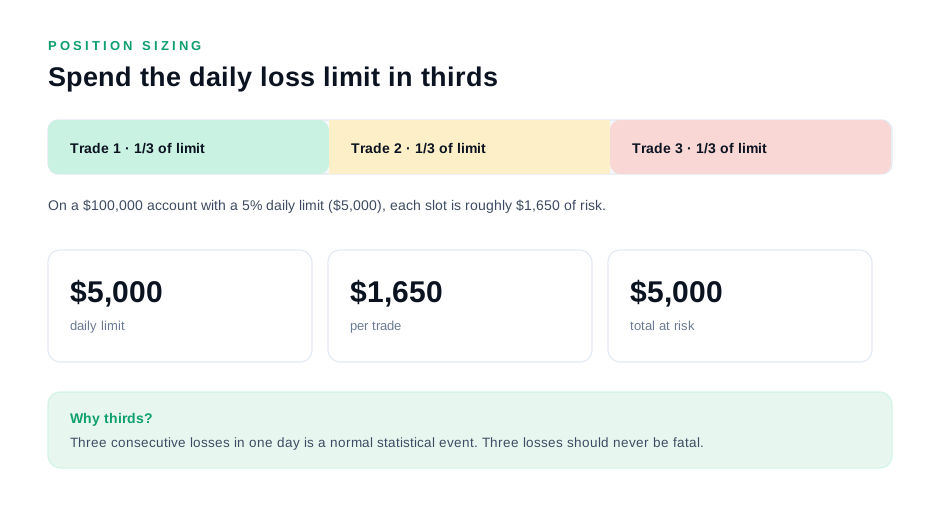
Two things should not happen in week one. The first is a size increase to "make the funded account count". The account counts from the first payout cycle, not from the first trade, and the fastest route to that cycle is a size that survives ordinary variance. The second is a strategy change. A plan that passed an evaluation has demonstrated one thing — that it can produce a positive expectation under a rulebook — and the funded month is not the place to test a different one.
Week two: the first real trades
Week two is where the funded account is either established or lost, and the pattern is consistent enough to describe in advance.
The first pattern is the return of the evaluation's size. Calibration goes well, the account is up slightly, and the trader concludes that the smaller size was unnecessary. Risk returns to the old number on the first genuinely uncertain trade, which is exactly the trade where the account cannot afford it. The rule that prevents this is mechanical: the size increases only after a completed payout cycle, not after a good week.
The second pattern is the profitable day that raises the floor. On a trailing structure, a strong session moves the failure point up, and the following day's ordinary retracement is measured against a higher floor. The trader believes the account is healthy because it is in profit; the mechanism disagrees. The countermeasure is to recompute the distance to the floor at the start of every session and to treat the result as the account's real risk capacity.
The third pattern is boredom. A funded account with a small position and no target produces long stretches with nothing to do, and the trades taken to fill them have no setup behind them. During an evaluation, the target absorbed that energy. On funding, the payout threshold is distant and abstract, so the discipline has to come from the session cap: a fixed number of trades and a fixed number of sessions, decided before the week begins.
The fourth pattern is the early withdrawal request. A trader reaches a modest profit and requests a payout before the minimum-day count or the consistency condition is satisfied, is refused, and concludes that the firm is withholding. In almost every case the conditions were published and unmet. Checking the three conditions before requesting — day count, threshold, consistency — prevents the entire episode.
None of these patterns requires a different strategy to fix. They require the funded rules to be treated as a new specification rather than as a continuation, and the funded risk line to be smaller than the evaluation's rather than equal to it.
Recalibrating the risk line
The funded risk line is not a scaled copy of the evaluation's. It is derived again from three inputs: the funded drawdown, the funded daily limit, and the payout conditions.
Start with the drawdown. Divide the distance to the funded floor by the number of consecutive losses the plan should survive, and treat the answer as a ceiling rather than a target. On a fully funded account the design case is usually stricter than on an evaluation — ten to twelve consecutive losses rather than eight — because there is no reset and because the first payout cycle is worth protecting.
Then check the daily limit. Multiply the per-trade risk by the number of losses a session should absorb and compare. If the product exceeds the daily limit, reduce the trade count first; the per-trade risk is already at its survivability floor.
Then apply the payout constraint, which has no equivalent during an evaluation. If the consistency condition caps a single day's share of total profit, the plan needs a daily profit cap as well as a daily loss limit. A trader aiming for a payout threshold and a consistency ratio simultaneously is solving two equations, and the daily profit cap is the variable that satisfies both.
Finally, fix the withdrawal cadence in advance. Deciding to withdraw "when it looks good" produces either an accumulation that makes the account fragile or a series of premature requests that fail the threshold. A fixed schedule — the same day each month, at the smallest permitted size for the first cycle — converts an emotional decision into a calendar entry.
The daily drawdown guide covers the reference-point arithmetic in detail, and the consistency guide covers the ratio calculations for the common thresholds.
The minimum-day and consistency clock
Two conditions run on their own clocks after a pass, and both are satisfied by behaviour rather than by profit.
The minimum-day count is the simpler of the two. It requires a number of trading days with a qualifying result, and it is usually satisfied long before the profit threshold on a plan of any reasonable pace. The trap is the trader who reaches the threshold early and then trades to fill the count: those sessions are the ones taken without a setup, and they can give back a meaningful portion of the profit. Trade the count at reduced size, accept flat days, and treat it as a calendar problem.
The consistency condition is the subtler one. Expressed as a best-day share of total profit, it means the largest day sets the minimum total. Under a share of around a third, total profit must reach roughly three times the largest day. A trader whose best day was a fifth of the threshold needs five times that day in total profit before the ratio permits a full withdrawal.
There are only two ways to satisfy the condition once a dominant day exists: earn more, or withdraw less. Earning more takes time and risks the account; withdrawing less is immediate and costs only the delay. Most traders choose the first when the second is correct — a partial withdrawal that satisfies the ratio and completes the cycle is worth more than a full withdrawal three months later, because it establishes the payment route and the timing.
The preventive measure is a daily profit cap set well below the threshold, applied from the first funded session. A cap converts the ratio from a problem discovered at the request into an arithmetic fact known in advance. The payout process guide walks through the sequence of conditions in order.
Problems that look like payout problems
Four situations present as a firm refusing to pay and are almost always something else.
A day-count shortfall. The threshold was reached, but the account had not traded the required number of qualifying days. Nothing is wrong; the condition is simply unmet. It is the most common cause of a first refusal and the easiest to avoid by counting the days before requesting.
A consistency shortfall. The profit is real, but one day dominates it. The refusal is procedural rather than punitive, and the remedy is to keep trading to a total that satisfies the ratio, or to withdraw a smaller amount that does.
Unfinished verification. Documents pending, address mismatched, or a payment method in a name that does not match the account. This is administrative and entirely under the trader's control in week one.
A conduct-clause question. A trade that appears to breach the news, overnight or permitted-instrument rules, or an arrangement that the firm classifies as third-party trading. This is the only category where the outcome can be genuinely adverse, which is why the clause should be confirmed in writing before the arrangement begins rather than defended afterwards.
The pattern across all four is that the trading was fine and a condition was not. That is why the funded month should be planned around the conditions rather than around the profit: the profit is the part the trader already knows how to make.
Completing the first cycle
The first payout cycle is the real milestone. It is worth more than a large balance, more than a second evaluation, and more than any single month's result, because it establishes that the whole chain works.
The cycle has six elements, and all of them should be completed before the size increases: the minimum-day count, the profit threshold, the consistency position, verification, the withdrawal request itself, and the receipt of funds. A trader who has completed all six knows the payment route, the processing time, the fees involved and the treatment of the payment. A trader who has completed five of six knows nothing about the sixth and will discover it at the least convenient moment.

The size of the first withdrawal is a separate decision from the size of the profit. Withdrawing the smallest permitted amount completes the cycle sooner and leaves more buffer in the account; withdrawing the maximum leaves less buffer and takes longer to qualify. For a first cycle, the smaller amount is usually the better trade, because the information is worth more than the difference.
After the cycle completes, two things become possible that were not possible before: a scaling request, where the firm's programme rewards completed payouts, and a considered decision about running a second allocation. Both should wait until the cycle is complete rather than run in parallel with it.
When to stop trading the allocation
There is a point on a funded account where the correct action is to stop, and it is worth defining it in advance because it is never obvious in the moment.
The first trigger is a drawdown that has consumed more than a set share of the funded limit — a half is a reasonable threshold. At that point the account can still be recovered, but not by trading the same size, and not within the same month. Reducing size by half and extending the calendar is the only survivable response; continuing at the original size converts a recoverable drawdown into a closed account.
The second trigger is a breach of the plan's own rules, as distinct from the firm's. A stop widened, a size doubled, a trade taken without a setup: these are plan breaches, and a plan that has been breached once is statistically more likely to be breached again in the same week. The response is a mandatory pause of several sessions, not a resolution to be more careful.
The third trigger is a change in the funded terms. If the firm revises the drawdown, the payout conditions or the conduct clauses, the plan built on the old version may no longer be viable. Re-deriving the risk line from the new terms is the minimum response; stopping until that is done is usually the correct one.
The fourth trigger is life. A funded account requires attention, and a trader who cannot give it for a fortnight — travel, illness, work — is better off flat than holding positions they cannot monitor. The account does not expire because it is not traded.
Defining these four triggers before the first funded trade is the difference between a drawdown that is managed and one that is discovered. A trigger written in advance is a decision; a trigger recognised in the moment is a rationalisation.
The psychology of the first funded month
The evaluation had a target, a deadline and a fee already paid. The funded account has none of those, and the absence changes behaviour in predictable ways.
Without a target, there is no natural stopping point, so trades continue past the point where the plan would have stopped. Without a deadline, the calendar stretches, and a drawdown that would have been decisive during an evaluation becomes something to trade through. Without a fee at stake, the cost of a breach feels abstract until the allocation is gone — at which point the cost is the whole account rather than a resettable purchase.
The countermeasure is to invent the missing structure. A monthly target, expressed as a payout threshold rather than a profit goal. A fixed number of sessions per week. A daily profit cap as well as a daily loss limit. A review every Friday with the same four numbers used during the evaluation. None of these is required by the firm, and all of them reproduce the conditions under which the evaluation was passed.
There is a second psychological shift worth naming. During an evaluation, the money is not real: the target is a number and a breach costs a fee. On funding, the profit is real and withdrawable, which makes the risk feel larger than it is and the reward feel smaller. Traders respond by taking profits early and letting losses run — the exact inversion of the plan that passed. The written rule matters more here than anywhere else, because the feeling is strongest precisely when the trade is working.
A third shift is identity. A trader who has passed is now, in their own mind, a funded trader, and funded traders are expected to size up. That expectation is not in any agreement. The only thing a funded account rewards is a plan that survives its own rulebook, which is exactly what the evaluation rewarded.
A thirty-day post-pass checklist
Thirty days is enough to complete a first cycle on most firms and long enough to establish whether the funded plan is sound. The checklist runs in order.
Day 1. Read the funded agreement. Write down the five numbers: funded maximum loss, funded daily limit, minimum profitable days, profit threshold, consistency condition. Submit verification and confirm the payment method.
Day 2. Confirm the platform server, the data feed and the exact time the trading day begins. Compare the spread and commission with what the evaluation delivered. Write the funded risk line with all four components.
Days 3 to 7. Calibrate at a quarter to a half of the evaluation's risk. Two trades per session maximum. Record planned risk, realised risk and time in the trade for every position.
Days 8 to 20. Move to the funded size if the calibration matched. Keep the session cap. Recompute the distance to the floor at the start of every session and the size every Monday. Set a daily profit cap below the consistency threshold.
Days 21 to 30. Check the three payout conditions — day count, threshold, consistency — and request the first withdrawal at the smallest permitted size if all three are satisfied. If they are not, extend rather than increase size.
Two rules apply throughout. No size increase before a completed cycle, and no strategy change during the first month. The first protects the account; the second protects the only evidence the trader has that the strategy works.
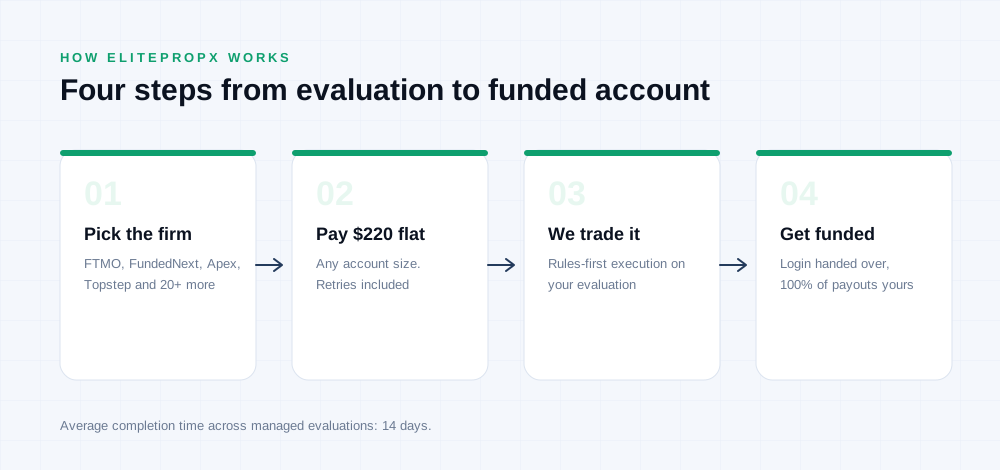
If a passing service produced the pass, the post-pass work is the account holder's regardless. The firm's terms on third-party trading must be confirmed for the funded stage as well as the evaluation, and the funded login should be in the trader's own name with credentials under their control. ElitePropX charges a flat $220 per evaluation at any stage and size, covers retries, and takes no profit split — the passing services guide explains what to check before paying anyone.
Frequently asked questions
What is the first thing to do after passing a challenge?
Read the funded agreement and write down five numbers: funded maximum loss, funded daily limit, minimum profitable days, profit threshold and consistency condition. Then start verification. None of the five can be inferred from the evaluation's rules, and the funded drawdown is usually tighter.
How much should I risk on a newly funded account?
Half or less of the evaluation's risk for the first five to ten sessions. The funded drawdown is frequently tighter, the server and feed may differ, and there is no reset behind a breach. Increase size only after a completed payout cycle.
Why is the funded drawdown tighter than the evaluation drawdown?
Because the firm is now exposed to real payouts rather than to a fee. Evaluation rules are designed to test a strategy; funded rules are designed to protect capital. The two objectives produce different numbers, and only the funded one governs the account that pays.
When can I request my first payout?
When three conditions are met: the minimum number of qualifying trading days, the profit threshold, and the consistency condition on the profit being withdrawn. Check all three before requesting — a request that fails a condition is the most common reason a payout appears to be refused.
Should I withdraw the maximum or the minimum on the first payout?
The smallest permitted amount, for the first cycle. Completing the cycle establishes the payment route, the processing time and the fees, and leaves more buffer in the account. The information is worth more than the difference in amount.
Do I need to verify my identity? When?
Almost always, and in the first week rather than at the first withdrawal request. Verification is administrative, has nothing to do with the trading record, and is routinely the step that delays a first payment. Name and address mismatches are the usual cause.
What is the consistency rule on a funded account?
A cap on the share of total profit that can come from one day, commonly around a third. It means total profit must reach roughly three times the largest day before a full withdrawal. Set a daily profit cap below the threshold from the first session so the ratio is satisfied when the threshold is reached.
Can I increase my size after passing?
Yes, but only after a completed payout cycle rather than after a good week. Scaling programmes generally reward completed withdrawals and consistent results, and increasing size before the first cycle means scaling a process that has not been tested end to end.
What happens if I breach the funded account?
The allocation is typically closed and the fee is not refunded. That is the main structural difference from an evaluation, which can be bought again. Treat the funded account as an allocation with no reset and size it accordingly.
Why do traders lose a funded account in the first month?
Four reasons: returning to the evaluation's size, a trailing floor raised by a strong session, trading without a setup because there is no target, and requesting a payout before the conditions are met. All four are planning failures rather than strategy failures.
Is the funded account's profit mine?
The profit split is defined in the funded agreement, and profit only becomes income when it is withdrawn. Unwithdrawn profit sits in the account, counts in the drawdown calculation, and on a trailing structure raises the floor. Withdraw on the earliest permitted schedule after the first cycle.
Does a passing service change anything after the pass?
The post-pass work belongs to the account holder regardless: verification, the payout conditions and the funded rules are theirs. Confirm the third-party clause covers the funded stage as well as the evaluation, and keep the funded login in your own name.
Want the evaluation traded for you?
Related reading
- The payout process, step by step
- Consistency rule guide
- Daily drawdown explained
- Passing an MFF challenge
- How to pass an FTMO challenge
- Weekend holding rules and gap risk
- Verified passes and what they prove
- Frequently asked questions
- How to Keep Funded Account
ElitePropX is an independent service and is not affiliated with, endorsed by or sponsored by any proprietary trading firm. Funded-account conditions, payout requirements and conduct clauses change; verify every detail against your firm's current agreement. Trading involves substantial risk of loss.