
Firm guide · reviewed October 2026
Topstep challenge rules and how to pass the Combine
Topstep combines a trailing maximum loss limit with an optional daily loss limit chosen at checkout, plus a best-day consistency target of 55% of the profit target during the Combine. This guide covers each rule as it is published, the sizing that survives them, and the mistakes that end attempts. The rules were checked against Topstep's own help centre on 19 October 2026.
Key takeaways
- Two loss rules apply at once — a trailing threshold and a daily loss limit — so the binding constraint is whichever is tighter that day.
- The best-day target is 55% of the profit target during the Combine, and 40% at payout. Exceeding 55% raises the profit target rather than failing the account.
- Progress makes a trailing account more fragile, so risk per trade falls as the target approaches.
- Typical pass time with disciplined pacing is ten to eighteen trading days.
Contents
What a passed Combine looks like afterwards. Firm-issued certificates, with the trader's name redacted, are on the passed challenges page. If you are weighing a passing service against doing it yourself, the propfirm passing service pricing prices the alternative, and the reviews page covers the attempts that were reset.
The rules, laid out
Topstep's Combine is a futures evaluation with dollar-based figures. The headline numbers scale with account size, but the mechanics do not.
| Parameter | How it works | What it means in practice |
|---|---|---|
| Profit target | Fixed dollar target per account size | Convert to a percentage before comparing firms |
| Trailing threshold | Follows peak equity upward | Progress reduces room; size must fall near the end |
| Daily loss limit | Optional at checkout: $1,000 / $2,000 / $3,000 by size | If chosen, it caps the session; triggering it is not a rule breach |
| Consistency | 55% of the profit target in the Combine; 40% at payout | The best day must stay below the stated share, or the target rises |
| Minimum days | Set by the firm's current terms | Pace the target to arrive on or after the count |
The distinctive feature of this rulebook is that the daily limit is a choice rather than a fixed rule. If it is bought at checkout, it caps the session and triggering it is not a breach; if it is not bought, the trailing maximum loss limit is the only failure condition. On a day when the trailing floor sits far beneath current equity, the optional daily limit binds first. On a day after a strong session — when the floor has risen close to the balance — the trailing limit binds first. A plan that assumes both rules always apply will overstate the constraint on an account that never bought the daily limit.
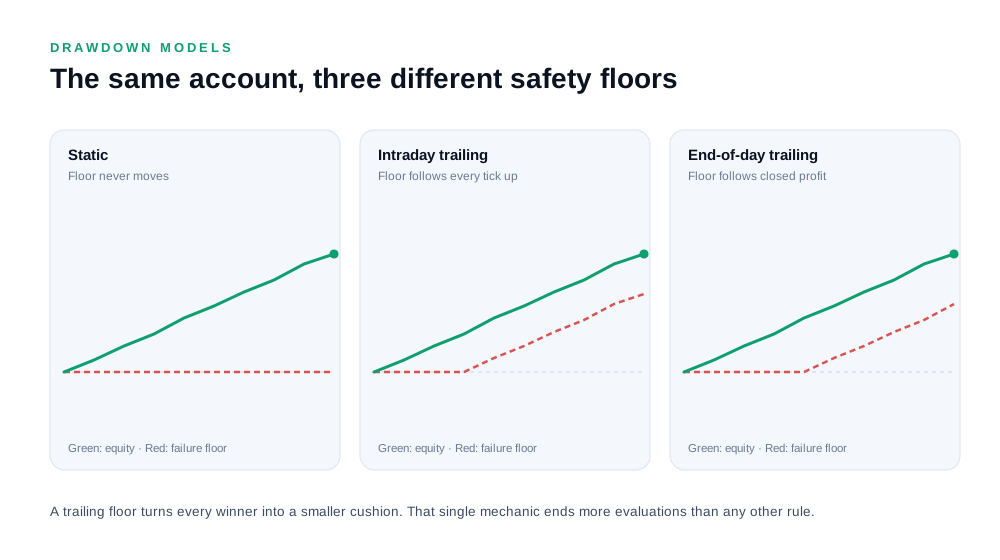
Two comparisons are worth having in mind before choosing a futures firm. Against Apex, the difference is the shape of the floor: Topstep's maximum loss limit trails the end-of-day balance, while Apex's intraday threshold follows unrealised profit. The second is stricter during a winning session, because a retracement has already moved it. Topstep's end-of-day method is closer to a static floor early in the account, and the limit locks permanently once it reaches the starting balance.
The trailing limit and the optional daily limit
The trailing limit is the rule traders underestimate, and the optional daily limit is the rule they misread. Both deserve precise treatment.
The maximum loss limit
Topstep sets the limit at $2,000 on a $50,000 account, $3,000 on $100,000 and $4,500 on $150,000. It is a trailing limit that rises with the end-of-day balance, never moves down, and locks permanently once it reaches the starting balance. Suppose a $100,000 account opens with a $3,000 limit at $97,000. If the balance closes the day at $102,000, the limit rises to $99,000; a $500 loss the next day leaves it at $99,000, and the room is now $2,500 rather than $3,000.
The critical detail is the measurement point. Because the floor follows the closing balance rather than unrealised profit, an open position that moves $3,000 in the money does not move the limit until the session closes. That makes the rule gentler than an intraday threshold during a winning day, and stricter in one specific case: a position held into the close that gives back its gain still sets the higher floor if it closed profitably.
The daily loss limit
The daily limit resets each session and is measured on the day's loss, which means a losing day is capped independently of the trailing floor. Three consequences follow.
First, a losing day is cheap on a trailing account. The floor only ever rises, so a session that ends down does not move it — the loss consumes the daily budget and nothing else. That asymmetry means the expensive behaviour is not losing; it is giving back a peak.
Second, the effective daily room is not the daily limit on every day. After a strong session the trailing floor may sit closer than the daily limit allows, in which case the floor binds first. A plan should compute both numbers each morning and use the smaller.
Third, because the daily limit is a dollar figure while the trailing distance is also a dollar figure, both scale with account size — but the ratios between them differ by plan. On some account tiers the trailing distance is the tighter constraint; on others the daily limit is. This is exactly the kind of detail that is invisible in a headline comparison and decisive in practice.
The best-day consistency expectation
Consistency is treated differently here than at firms where it appears only as a payout gate. The expectation is that no single session dominates total profit, and it is applied with enough weight that a trader who reaches the target on the back of one large day can find the evaluation incomplete or the payout delayed.
The arithmetic is different from a 30% payout rule, and it is worth restating in dollars. In the Combine the best day must stay at or below 55% of the profit target: under $1,650 on a $3,000 target, under $3,300 on a $6,000 target and under $4,950 on a $9,000 target. Exceeding the line does not fail the account; it raises the target to best day ÷ 0.55. A $2,000 best day on a $3,000 target therefore turns the target into $3,636, and the extra profit has to be earned on a later session. At payout the limit tightens to 40% of total profit.
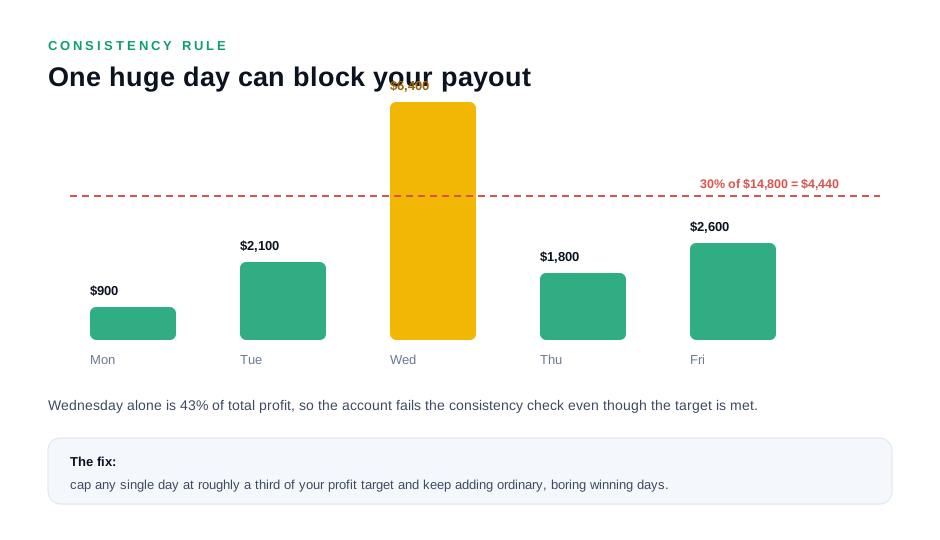
On a futures evaluation this restraint is doubly important, because the same session that produces a dominant day also lifts the trailing floor. A trader who finishes a strong day has both a consistency problem and a thinner cushion — the two worst outcomes in the same session, produced by the behaviour that felt most successful.
A risk plan that satisfies all three rules
Five numbers define a workable Combine plan, and each derives from one of the rules above.
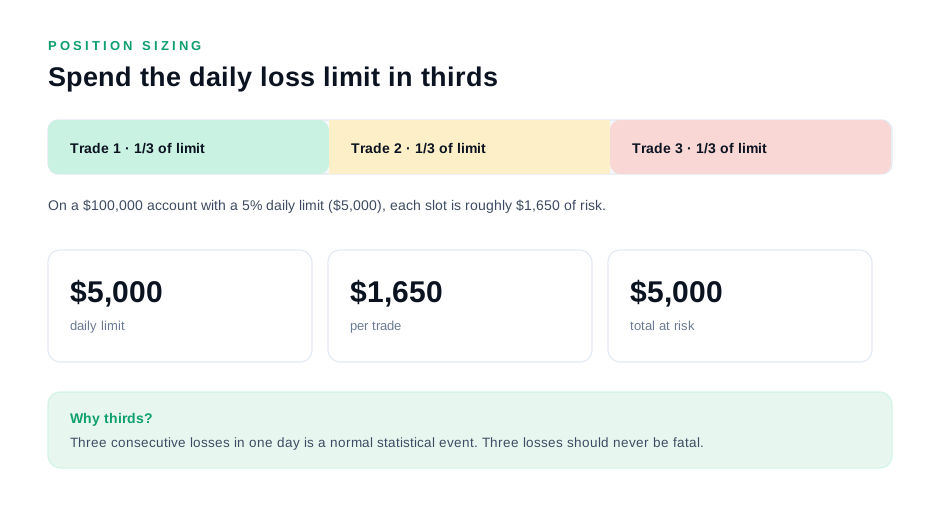
- Maximum risk per trade: a third of the daily loss limit. This keeps three consecutive losses survivable, which is the property that matters across a multi-week evaluation.
- Daily stop: stop opening positions once 80% of the daily limit is realised. The remaining 20% exists to absorb slippage on the closing trade.
- Daily profit cap: well below 55% of the target. On a $6,000 target the hard line is $3,300; a self-imposed cap of $2,000 leaves room for an ordinary day to be the best day.
- Size ladder: full planned size to 40% of target, three quarters from 40% to 70%, half beyond 70%. This is the response to the trailing threshold, and it is mandatory rather than optional.
- Floor check: recalculate the trailing failure level every morning and compare it with current equity. If the remaining buffer is smaller than the risk of a single planned trade, the session does not start.
The fifth item is the one traders skip, and it is the one that prevents the defining failure mode of a trailing account. The check takes twenty seconds: current equity minus trailing threshold equals available room; if that number is under the planned per-trade risk, either reduce size or do not trade that session. There is no scenario in which trading anyway is correct, because the evaluation can always be finished tomorrow and cannot be recovered once failed.
The counter-intuitive rule: on a Combine, a strong start is a liability as well as an asset. It raises the floor and raises the consistency bar. The correct response to a large winning session is not to press, but to reduce.
Pacing a 10–18 day pass
A realistic pace on a $100,000 account with a dollar target and a trailing threshold is ten to eighteen trading days, structured as follows.
Sessions 1–3 — establish the plan. Half of planned size while the plan is tested against real conditions. One or two setups per session, a hard daily cap and an explicit decision to stop at the cap rather than extend a good day. Expected outcome: 15–25% of target with the floor moved modestly.
Sessions 4–7 — the working middle. Full planned size, which on a six-day-a-week futures schedule is three or four sessions a week. Daily profit capped at roughly a third of the target. Target completion should reach 55–70% by the end of this phase, with no single day exceeding the cap.
Sessions 8–12 — reduce and protect. Size falls to three quarters and then to half as completion passes 70%. The trailing floor is now close enough that a retracement from the peak is a genuine risk, so sessions get shorter and the remaining ground is covered in small increments. Any session that reaches the cap is closed rather than extended.
Completion. Once the target is reached and the minimum day count is satisfied, trading stops. On a trailing structure there is nothing to gain from continuing: the account cannot improve its standing, and every tick in either direction moves the floor or consumes budget.
The single most useful habit during pacing is to write the daily cap and the floor check into the plan as rules rather than intentions. Traders who track their ratio and their buffer informally tend to abandon both in the session where they matter most — which is the session after a large winner.
Where Combine attempts fail
- Holding a runner through a retracement. The floor moved with the peak; the retracement is measured from the peak, not from the entry. This is the most common failure on any trailing structure.
- Increasing size as completion approaches. The instinct that fails trailing accounts, because progress is precisely when the buffer is thinnest.
- One dominant day. Efficient for reaching the target and expensive for consistency, in the same session that raises the floor.
- Reading only one of the two loss rules. A plan built around the daily limit alone assumes the trailing floor is distant. After a good session it is not.
- Trading through the daily cap to "stay active". Activity is not a requirement; the minimum day count is. On a qualified day, the smallest possible closed trade satisfies it.
- Treating a flat day as lost ground. Flat sessions cost nothing on a trailing account, because a losing day does not move the floor. The recovery trade after a flat day is a bigger risk than the flat day itself.
- Ignoring news and session restrictions. Futures firms restrict trading windows around scheduled releases and enforce them by pattern detection rather than manual review.
From Combine to payout
Rule sources (checked 19 October 2026). Maximum loss limit, optional daily loss limit and consistency targets. Figures apply to the Trading Combine and can change; confirm the plan at purchase. How we check firm rules explains what the checked date covers.
Passing the Combine produces a funded account with its own conditions, and on a futures firm they are usually more demanding than the evaluation itself.
| Condition | During the Combine | On the funded account |
|---|---|---|
| Profit target | One-time, to pass | Recurring threshold before each payout |
| Trailing threshold | Follows peak equity | Usually static at the starting balance |
| Daily loss limit | Optional at checkout | Often retained in some form |
| Consistency | Applied to the evaluation | Applied firmly at payout |
| Minimum days | To complete the evaluation | Five to ten before each payout |
The good news is that the trailing behaviour usually disappears at funding, replaced by a static failure level. That removes the mechanic that made the evaluation hardest. The less good news is that the consistency check becomes strictly binding, so a trader who passed with one dominant day can be funded and still unable to withdraw.
The remedy is the same discipline applied one step earlier: cap daily profit at about a third of the eventual total during the funded phase too, complete KYC in the first week rather than at the payout request, and plan the threshold and the minimum day count to complete together. The payout process guide walks through the sequence and the delays that block first withdrawals.
A worked Combine, session by session
A $100,000 account, a dollar target of $6,000, an end-of-day trailing maximum loss limit of $3,000 and the optional $2,000 daily limit, traded on the size ladder described above.
Session 1 — +$520. Half size while the plan is tested. The floor rises modestly with the peak. Nothing notable, which is the objective of a first session.
Session 2 — +$1,180. Full size. The session is closed at $1,180 rather than extended toward the daily cap of $2,000, because the cap exists to protect the consistency ratio and extending a good session spends that protection for no additional benefit.
Session 3 — −$410. One loss at planned size, then closed. Note what this session did not cost: on a trailing account a losing day does not move the failure floor, so the day consumed budget and nothing else.
Session 4 — flat. Three scratch trades. Logged as flat and treated as a normal outcome rather than a reason to increase size the next morning.
Sessions 5–8 — +$2,940 combined. The working middle. Completion reaches 74%, so risk per trade drops to three quarters of planned size and then to half. The daily cap of $2,000 means no session can threaten the consistency ratio even if it finishes at the cap.
Sessions 9–11 — +$1,760 combined. The final 26% at half size, in three short sessions. The floor is checked each morning before trading; on one of those mornings the remaining buffer was smaller than the planned per-trade risk, so size was cut again for that session rather than trading the standard plan.
Completion. The target is reached on session 11 with a best day of $1,180 — 19.7% of the $6,000 target, comfortably inside the 55% consistency line. The minimum day count is satisfied on the same session because the pace was planned backwards from the requirement. Trading stops.
What the sequence demonstrates: two losing-or-flat sessions, no dominant day, a floor check that changed the plan once, and a completed evaluation in eleven sessions. None of it required a better market view than the plan already assumed.
Account sizes and choosing where to start
Topstep's account tiers run from $50,000 to $150,000, and the target and the trailing distance both scale with size. Two practical observations follow from that.
The smaller tiers are not proportionally easier. Because both the target and the threshold distance scale with the account, the evaluation difficulty is roughly constant across tiers — a $50,000 account needs a smaller dollar target and has less dollar room. What does not scale is the fixed cost per contract: commissions and slippage are identical in dollars, so on a smaller account they consume a larger share of the target. In practice, small accounts are marginally harder to pass than large ones at identical discipline, which is worth knowing before buying the cheapest tier and expecting a higher pass rate.
The funded phase is where size pays. A funded account at a mid-tier size with a satisfied consistency record produces real income; a failed evaluation at the largest tier produces nothing. The efficient path for a trader new to futures is to prove the plan at a mid-tier size, then scale on the firm's own terms once a payout history exists. Firms increasingly tie additional accounts or larger balances to a record of completed payouts rather than to a single large profit month.
A related point about sequencing: running two Combine attempts at the same time splits attention and creates correlated positions across accounts, which firms treat as a single exposure. Sequential funding — pass one, trade it, add a second — is slower to start and considerably faster to reach a first payout.
Session structure, news rules and permitted hours
The rules that surround the loss limits matter as much as the limits themselves, because they determine which opportunities are legitimate in the first place.
Permitted hours. Futures trading is confined to session windows defined by the firm and by the exchange's own trading hours. The practical effect is that the plan must choose its windows in advance rather than reacting to an instrument that looks interesting at an unusual hour. For most evaluations, the liquid part of the session is where the plan operates, and the thin overnight hours are avoided — not because they are prohibited, but because slippage on a thin book is the most expensive kind of loss on an account with a fixed dollar threshold.
News windows. Firms restrict trading around scheduled economic releases, and the futures firms are generally strict about it. The definition matters more than the existence of the rule: windows are usually specified in minutes either side of the release, and a position opened legitimately before the window can still breach if the rule requires it to be closed. The safe reading is the strict one, and the plan treats the window as closed regardless of what any instrument is doing inside it.
Contract caps. Maximum position size per instrument is often stated in the terms rather than on the evaluation page. Trading a permitted instrument at twice the permitted size is a breach, and it is one of the most common accidental ones because the cap is easy to exceed on a fast-moving contract.
Daily session count. A plan that trades four or five sessions a week rather than every available session produces a slower pass and a materially lower breach rate. Rest is not a cost on a trailing account; it is a control, because every session moves the floor or consumes budget, and sessions with no clear plan do one or the other without adding profit.
Holding overnight and over weekends. Policies differ and the fees or restrictions attached to them can convert a technically valid position into a rule breach. Where the plan permits holding, it accounts for the gap risk explicitly; where the firm restricts it, the position is flat before the close rather than left to chance.
Frequently asked about Topstep
What is the single most important rule in the Combine?
The trailing threshold, because it changes every other decision. It sets how much room remains, how size must fall as progress accumulates, and why a flat day costs far less than a day that gives back a peak. Read the daily limit second.
How long does it take to pass a Topstep Combine?
Ten to eighteen trading days with disciplined pacing, depending on the account size, the target and the minimum day count. Faster passes are possible but usually create a consistency problem at payout.
Does the Topstep threshold trail intraday?
No. The maximum loss limit trails the end-of-day balance, not unrealised profit, and it never moves back down. Once it reaches the starting balance it locks there permanently. That makes it gentler than an intraday threshold during a winning session, though a strong closing day still raises the floor for the next session.
What is the best-day consistency rule?
In the Trading Combine the best day must stay at or below 55% of the profit target. If it exceeds that, the target rises rather than the account failing: on a $50,000 account, a $1,800 best day raises the target to about $3,273. At payout the stricter 40% limit applies, so the largest day cannot exceed 40% of total profit.
Which rule binds first, the daily limit or the trailing floor?
It depends on the day. Early in an evaluation the daily limit usually binds because the floor is distant; after a strong session the trailing floor can sit closer to current equity than the daily limit allows. Calculate both each morning and use the smaller number.
What risk per trade should I use?
A third of the daily loss limit at most, with a hard stop at 80% of the day's budget spent. Three consecutive losses at that size leave the account alive, and the plan intact.
Is Topstep harder than Apex?
They use different floors. Apex's intraday threshold follows unrealised profit, so a retracement on a winning day has already tightened the account; its EOD evaluation does not trail intraday. Topstep's follows the end-of-day balance and locks at the starting balance. Topstep publishes a 55% best-day target during the Combine and a 40% threshold only on its optional consistency payout path, while Apex applies a 50% best-day rule at payout (30% on legacy accounts). The harder firm depends on whether your method gives back open profit or closes it.
What happens if I fail the Combine?
The firm's reset and purchase options apply. Where a passing service trades the evaluation, a reset on the same firm and account size carries no additional service fee under the flat $220 arrangement — the firm's own reset charge is separate.
Should I trade every session of the week?
No. Four or five planned sessions a week produces a slower pass and a lower breach rate than trading every available window. On a trailing account, every session either moves the floor or consumes budget, so a session with no specific plan costs something and gains nothing.
How do payouts work after passing?
A funded account is issued with a minimum day count, a profit threshold, a consistency check and KYC requirements. Most futures firms also apply a first-payout waiting period. The payout guide covers each step.
The two loss rules, and why they are not the same rule
Topstep states a maximum loss limit and an optional daily loss limit separately, and the distinction matters more than it appears. The maximum loss governs what can happen to the account; the daily limit, if bought at checkout, governs what can happen in a session. A Combine without the add-on has only the trailing maximum loss, so a bad day is bounded by the floor rather than by a session stop.
The daily limit ends the session. Reach it and the day is over; the account survives, and tomorrow starts with a fresh budget against the same floor. The maximum loss ends the account. There is no tomorrow, and the only recovery is a new purchase.
| Daily loss limit | Maximum loss limit | |
|---|---|---|
| What it governs | The session | The account |
| Consequence of breach | Day ends, account continues | Account is closed |
| Resets | Every session | Never |
| Planning implication | Three losses at 1.5% risk | Roughly six losses from the starting balance |
Why the daily limit is the one that matters
In practice almost every failure arrives through the daily limit first, because reaching the maximum loss requires either a single enormous position or a run of days that each came close to the daily cap. Both are preventable, and the second is entirely visible in a journal two weeks before it happens.
The useful habit is to compute both numbers each morning and to treat the smaller of the two as the binding constraint. On a $50,000 account with a $1,000 daily limit and a $2,000 maximum loss, the daily limit is a fifth of the total room — which means the account can only survive two bad days before the maximum loss becomes the live number.
The payout path after a pass
The funded stage on Topstep has its own conditions, and they are the ones that decide whether a pass becomes income. The variables are familiar: a minimum number of winning days, a profit threshold, a consistency expectation on the best day, and a processing schedule. What differs is how they combine.
Winning days, not just profitable days
Where a firm counts winning days, a day with a small loss does not count and a scratch does not count. That changes pacing: a trader who reaches the profit threshold in a week may still need another fortnight of positive sessions to satisfy the day count, and the efficient plan lands both conditions on the same date rather than treating the second as a formality.
Consistency at withdrawal
Where a best-day expectation applies, the same arithmetic as every other firm applies: required total profit equals best day divided by the threshold. A trader with one very strong session and a thin remainder will be asked to keep trading until the ratio normalises, and the correct response is smaller size and ordinary profit rather than a second strong session.
What to do between the pass and the first withdrawal
Trade small, close the day early, and keep a written record of the running totals for both conditions. The temptation during this period is to make the first payout worth having, which is the single most common way a funded account is lost before it pays anything. The first payout's purpose is to prove the pipe works, not to change a trader's month.
If this is your first futures evaluation
Topstep is a reasonable first assignment because the rules are documented and the day count is forgiving, but three things are worth doing before the fee is paid.
- Trade the platform on demo for a week. Futures mechanics — tick value, contract sizing, session hours, the difference between ES and MES — are learned cheaply before money is involved.
- Choose the smallest size that permits a meaningful payout. The percentage rules are identical at every size, so the only thing a larger account buys is a bigger payout ceiling and a bigger fee.
- Write the daily budget on paper. In dollars, in ticks, and in contracts. A trader who has to calculate the budget mid-session has already lost the discipline the budget was meant to enforce.
None of that is novel advice; all of it is routinely skipped. The traders who pass futures evaluations on the first attempt are not usually better analysts than the ones who fail — they are the ones who did the arithmetic before the market asked them a question.
One further suggestion, drawn from the pattern of failures rather than from best practice: choose the session before the instrument. A trader who knows they will be at the screen from the New York open until 11:30 has a fixed window, a fixed set of instruments that behave well in it, and a natural end to the day. A trader who trades "whenever there is a setup" has no end to the day, and the session that never ends is the one that spends the last dollars of the daily budget on a trade nobody needed.
The complementary rule is to decide the day's maximum trade count before the open and to treat the third trade as a decision rather than a continuation. Futures traders on a five-contract limit reach three trades remarkably quickly in a volatile session, and the third trade is where sizing discipline usually slips.
Both rules — a fixed session and a fixed trade count — are ways of putting an end to the day before the account puts one there. On a firm with a separate daily limit and maximum loss, that end is the only thing standing between a bad session and a closed account.
Neither rule is difficult to follow on a good day. Both are almost impossible to follow on a bad one, which is why they are written down in advance and checked before the first trade rather than remembered in the middle of the third.