
Firm review · reviewed October 2026
TFT funded trader review: the rulebook, the cost, and who it fits
Take Profit Trader sells futures evaluations on two different account models, and the difference between them is not cosmetic — it changes the arithmetic of every trade you take. This review works through the drawdown structure, the consistency gate at payout, the real cost of a failed attempt, and the specific kind of trader each model rewards. It is written from the rule mechanics outward, because the mechanics decide outcomes long before the market does.
Key takeaways
- TFT runs two models — a cheaper one with an intraday trailing threshold and a costlier one with an end-of-day threshold. The second is materially easier to pass at equal skill.
- A trailing threshold that responds to unrealised profit punishes a winning session that retraces. An end-of-day threshold does not, because it only looks at the closing balance.
- Cost per attempt, not headline fee, is the number to compare. Two resets on a cheap account can cost more than one attempt on a better-structured one.
- The consistency expectation binds at payout, not at evaluation. A fast pass built on one dominant day can produce a funded account that cannot withdraw.
- Futures firms restrict sizing, session hours and news windows. Those rules fail more accounts quietly than the drawdown does.
- Terms change. Every figure below describes a mechanism; confirm the current numbers on the firm's own pages before paying.
Contents
- What this review measures
- Two models, two rulebooks
- The drawdown structure, precisely
- The payout gate
- Cost per attempt, not cost per account
- A sizing plan for each model
- Where TFT attempts fail
- Who the rulebook suits
- TFT against the futures field
- A pre-purchase verification checklist
- Frequently asked questions
What this review measures
Most prop firm reviews answer a question nobody asked. They list a fee, a target and a drawdown figure in a table and call the firm cheap or expensive, as though the three numbers were the whole product. They are not. The numbers that decide whether a trader passes are the ones that describe how the failure floor moves, what counts as a breach, how many sessions the target realistically takes, and what has to be true before a withdrawal is approved.
So this review measures five things, and it measures them in a fixed order. First, the structure of the loss limit: is the floor static, does it trail on closed profit, or does it trail on open profit? Second, the target expressed as a percentage of the account, because that is the only form in which it can be compared across firms. Third, the daily constraint, which on a trailing account is often the tighter of the two loss rules. Fourth, the conditions attached to the funded stage, because a cheap evaluation leading to an unusable funded account is not cheap. Fifth, the total cost of reaching a first payout, which includes resets, not just the initial purchase.
Everything else — platform quality, dashboard design, the friendliness of support — matters to the experience and almost nothing to the outcome. A trader can be comfortable on a platform and still fail a rule, and the rule does not care about comfort. This is why the review leads with mechanism. If the mechanism is understood, the platform is a preference. If the mechanism is not understood, no amount of platform polish will save the account.
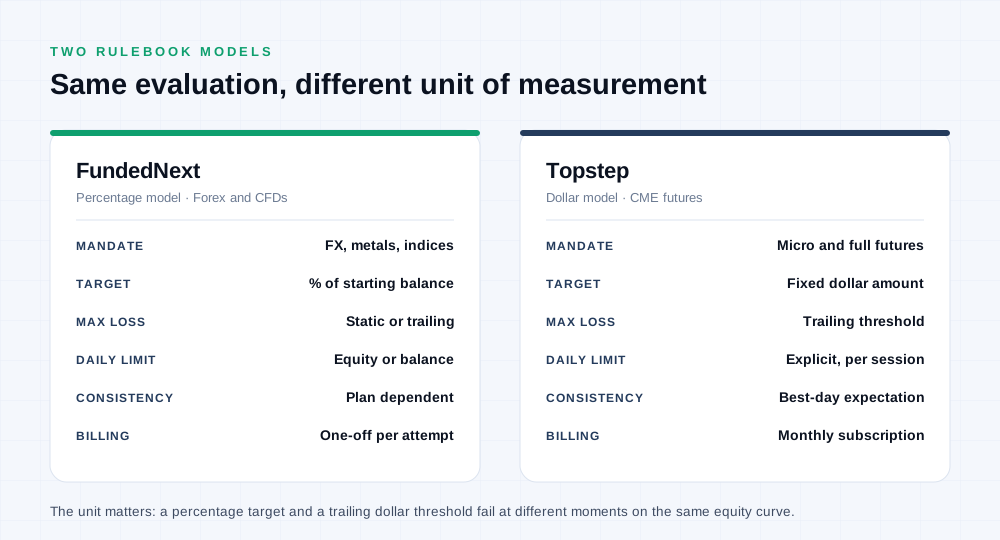
One structural note before the detail. TFT is a futures firm, which means two things that do not apply to Forex evaluations. Accounts are denominated in dollars and traded in contracts, so a target is a dollar figure rather than a percentage you can halve or double freely. And futures firms enforce conduct rules — maximum contracts, permitted hours, news windows, holding restrictions — that Forex firms usually leave unstated. A review that ignores conduct rules is reviewing perhaps half of the product.
Two models, two rulebooks
The single most important fact about TFT is that the firm sells two accounts with genuinely different failure mechanics. The cheaper model uses an intraday trailing threshold; the more expensive one uses an end-of-day threshold. Calling them both "the TFT evaluation" is the mistake most reviews make, and it produces advice that is wrong for half the readers.
| Mechanic | Entry model | Pro model |
|---|---|---|
| Failure floor | Trails intraday, on unrealised equity | Trails at end of day, on closed balance |
| Effect of a winner that retraces | Floor already moved; cushion permanently smaller | Floor unmoved until the close |
| Effect of progress | Account grows more fragile as it succeeds | Account grows more resilient as it succeeds |
| Sizing response required | Size must fall as the target approaches | Size can stay constant |
| Typical pass difficulty | Higher at equal skill | Lower at equal skill |
| Where the extra fee goes | — | Into the removal of the intraday mechanic |
The important insight is not that the Pro model is better. It is that the two models reward different behaviour, and a trader who has practised on one will be miscalibrated on the other. A trader trained on the entry model has learned to take profit early and to cut size as the target approaches, because the floor punishes the alternative. Put that trader on the Pro model and nothing breaks: the habits are conservative, and conservative habits cost only a little pace. Reverse the direction and it is expensive. A trader raised on end-of-day thresholds has never had to reduce size after a strong session, and the first strong session on an intraday account will feel like progress while it is quietly removing the cushion.
There is a second asymmetry worth noting. On an end-of-day structure, the account's risk profile is fixed each morning: you know the floor, you know the distance from equity to the floor, and that number cannot change during the session. That makes the sizing decision a single calculation made once. On an intraday structure, the distance shrinks and grows within a session, and the sizing decision is continuous. Continuous decisions are harder to execute well, because they have to be made while the position is live and the trader is emotionally engaged.
Choosing between them: if the two fees differ by less than the cost of one reset on the cheaper account, the more forgiving model is usually the better purchase. The calculation is in the cost section below, and it is the only comparison that matters when the choice is between these two.
The drawdown structure, precisely
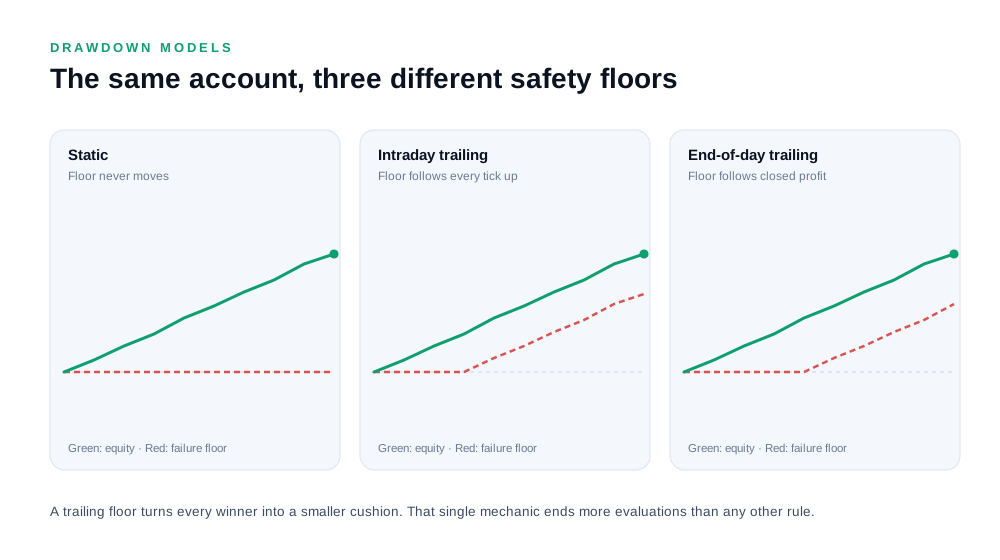
A trailing drawdown is a failure floor that rises with account equity and never falls. The detail that decides everything is which equity it follows.
An intraday trailing floor follows the peak of unrealised equity, tick by tick. If a position runs $2,000 into profit, the floor has already risen by $2,000, even though nothing has been banked. Close the trade at $600 after a retracement and the floor stays where the peak pushed it. The trader kept $600 of profit and lost $1,400 of room, permanently. On a $100,000 account with a $3,000 starting buffer, that single sequence can remove nearly half the remaining cushion on a day that ended in profit.
An end-of-day trailing floor follows the closing balance. Nothing moves while the market is open. A position that runs to $2,000 and closes at $600 moves the floor by $600, because $600 is what the account actually holds. The unrealised excursion is invisible to the rule.
This is not a small difference in strictness; it is a difference in what the rule is measuring. The intraday version measures the best moment; the end-of-day version measures the result. A trader who is right about direction but poor at exits is punished severely by the first and barely at all by the second. A trader who is right about direction and disciplined at exits is punished only slightly by the first — which is why some traders genuinely do not need the more expensive model, and why the recommendation has to be conditional rather than universal.
What "trailing" does to a good start
On a trailing account, a strong opening week is both an asset and a liability. The asset is obvious: you are closer to the target. The liability is that the floor has risen with you, so the remaining room is smaller than it was at the start, while the remaining distance to the target is also smaller. If the two shrink at the same rate, the evaluation never gets easier — it just gets shorter.
Work the numbers. A $100,000 account, a $6,000 target, a $3,000 trailing buffer, all figures dollars. After $4,000 of profit the target is two thirds complete and the floor has risen $4,000; remaining room to the floor is $3,000, unchanged in absolute terms, but now the account is risking a $4,000 gain against a $3,000 buffer. In ratio terms the trade has become considerably worse. That is the arithmetic most traders never perform, and it is the reason a plan must reduce size as completion rises rather than hold it constant.
On an end-of-day structure the same sequence produces a different picture only because the peak cannot outrun the close. The trader who books $4,000 has genuinely moved the floor $4,000, so the ratio arithmetic is identical — but the trader who books $600 of a $4,000 excursion has moved the floor $600 and kept the other $3,400 of room. The end-of-day model converts exit discipline into structural advantage. The intraday model converts it into survival.
The daily limit on top
Futures firms typically apply a daily loss limit alongside the trailing threshold, and the binding rule each morning is whichever sits closer to current equity. After a flat week the trailing floor is usually distant and the daily limit binds. After a strong session the floor can be closer than the daily limit permits, and then the floor binds first.
The practical consequence is that a single number is not enough. Compute both each morning, take the smaller, and size from that. The arithmetic takes twenty seconds and prevents the most common self-inflicted failure on a trailing account, which is trading a normal-sized position on a morning when the floor had quietly moved within one trade of current equity.
The payout gate
Passing an evaluation at TFT produces a funded account with its own conditions, and on futures firms those conditions are usually stricter than the evaluation. Three gates matter: a minimum number of trading days before a withdrawal can be requested, a profit threshold that has to be met again on the funded account, and a consistency expectation that caps how much of the total any single day may represent.
The consistency gate deserves its own arithmetic because it is the one that surprises traders. If a best day may not exceed a stated share of total profit, then required total profit equals the best day divided by that share. A $3,000 best day under a 30% rule requires $10,000 of total profit before the payout clears. A trader who reaches the funded threshold quickly on the back of one enormous session has not finished; they have created a requirement to keep trading until the ratio normalises, and that requirement arrives exactly when the trader believes the work is done.
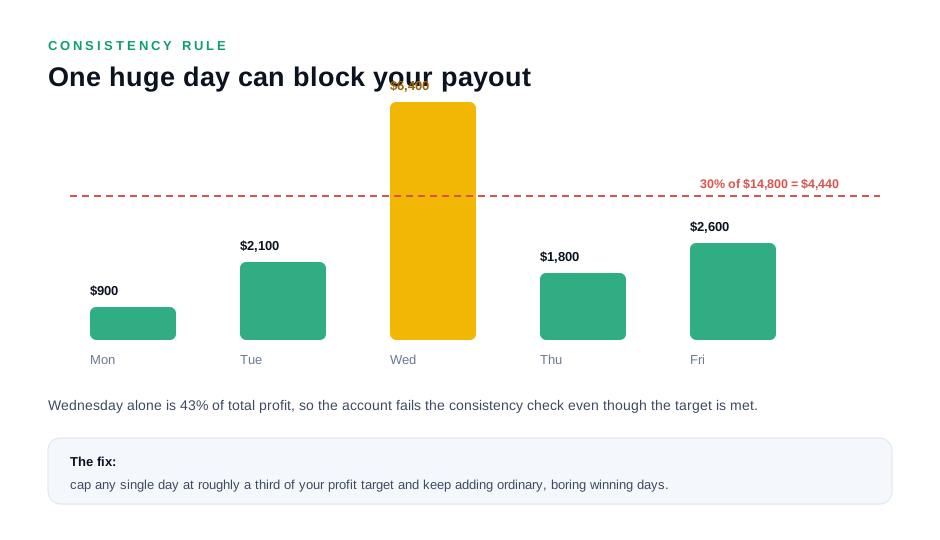
The remedy is to cap daily profit during the evaluation at roughly a third of the eventual total. On a $6,000 target that is a $2,000 daily cap, which automatically satisfies a 30% best-day rule the moment the target is reached: the best day is $2,000 and the total is $6,000, a share of 33%. Adjust the cap to the firm's stated threshold, and remember that the threshold can differ between the evaluation and the funded stage, so read both.
| Best-day share rule | Total profit needed if best day is $2,000 | Daily profit cap that satisfies it at a $6,000 target |
|---|---|---|
| 20% | $10,000 | $1,200 |
| 25% | $8,000 | $1,500 |
| 30% | $6,667 | $2,000 |
| 40% | $5,000 | $2,400 |
| 50% | $4,000 | $3,000 |
Read the table from right to left. The cap is the decision; the total follows. A trader who sets the cap at a fifth of the target will satisfy even a strict rule, and will do so without ever thinking about the rule again. A trader who sets no cap is making a bet that no session will be unusually good, which is a strange bet for someone whose entire plan depends on sessions being good.
Two further gates are administrative rather than mathematical, and they block more first payouts than either of the above. Identity verification must be complete before a withdrawal is reviewed, and it is often left until the request is submitted. And the first payout is frequently subject to a waiting period measured from the first trade on the funded account. Neither is a rule to plan around so much as a calendar to plan against: complete verification in week one, and request the first withdrawal on the earliest permitted date rather than at the largest possible size. The first payout exists to prove the pipe works.
Cost per attempt, not cost per account
Prop firm pricing is quoted per attempt, and attempts fail. That makes the headline fee a poor measure of cost. The number that matters is the expected spend required to reach one funded account, which is the fee times the number of attempts a trader of that skill level typically needs.
The arithmetic is unforgiving. If a trader fails twice before passing, three fees is the cost of one funded account. At that ratio, a firm charging 60% more with a materially more forgiving drawdown structure is the cheaper purchase — and it is cheaper by a wide margin, because the second fee is not discounted by anything. This is the calculation that makes the entry-versus-Pro decision, and it is also the calculation that most traders skip when they compare firms on a pricing page.
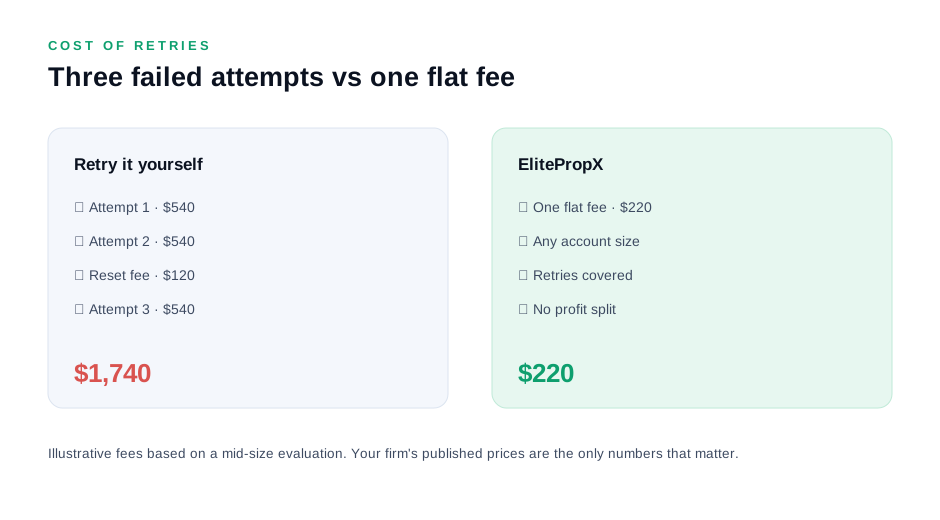
There is a third option that changes the arithmetic entirely, and it should be stated plainly because it is the service this site sells. A passing service trades the evaluation for a flat fee, once, and covers resets while the evaluation is running. Under a flat $220 arrangement the expected cost is not fee times attempts; it is the flat fee, plus whatever the firm charges for a reset if one is needed. That is a different cost curve, and it is worth comparing against the fee-times-attempts figure rather than against a single fee.
Two honesty conditions apply, and a service that does not state them is not worth using. First, many firms prohibit third-party trading of an evaluation; if the firm's terms forbid it, the service should decline the job rather than quietly accept the risk on the client's behalf. Second, a passed evaluation is only worth paying for if the funded account is in the client's name and the payout history is genuine. The passing service review covers what to check, and the comparison of services sets out how the flat-fee model compares with doing it yourself.
For completeness, the do-it-yourself cost has three components that a fee comparison ignores: the fee, the time, and the opportunity cost of the capital. A trader spending six weeks on three failed attempts has spent more than three fees — they have spent six weeks during which a funded account could have been earning. That is not an argument for outsourcing; it is an argument for measuring the whole number before choosing. The profit calculator handles the payout side of the same question.
A sizing plan for each model
The two rulebooks need two plans, and the difference is concentrated in one decision: whether size falls as the target approaches.
For the intraday model, size must ladder down. A workable structure is full planned size to 40% of target, three quarters from 40% to 70%, and half beyond 70%. The reason is the ratio arithmetic above: as completion rises, the gain at risk grows while the buffer shrinks, so the trade that got you to 70% is not the trade you should take at 70%. Traders who hold size constant through the last third are the population that fails from a winning position.
For the end-of-day model, size can stay flat — provided the daily loss limit is respected independently, because the daily limit still binds within a session even when the trailing floor does not move until the close. A flat size ladder is simpler to execute and produces a faster pass, which is part of what the higher fee buys.
In both cases the per-trade risk should be a third of the daily limit at most, and the session should stop at 80% of the daily limit realised. Three consecutive losses at that size leave the account alive and the plan intact, which is the property that matters across a multi-week evaluation. A plan that survives two losses but not three is not a plan; it is a sequence of coin flips with a calendar attached.
The floor check: every morning, subtract the current failure floor from current equity. If the result is smaller than the risk of one planned trade, either cut size or do not trade. There is no scenario in which trading anyway is correct, because the evaluation can be finished tomorrow and cannot be recovered once failed.
The daily session count deserves the same treatment as the size. Four or five planned sessions a week produces a slower pass and a materially lower breach rate than trading every available window. On a trailing account every session either moves the floor or consumes budget; a session with no specific plan does one or the other without adding profit. Rest is not a cost. On this rulebook it is a control.
Where TFT attempts fail
Failures cluster. The same six behaviours account for the overwhelming majority, and none of them is a market-view error.
- Holding a runner through a retracement on the intraday model. The floor moved with the peak, so the retracement is measured from the peak rather than from the entry. This is the defining failure of any intraday trailing structure.
- Increasing size near the target. The instinct that feels like confidence and behaves like a liquidation order. Progress is precisely when the buffer is thinnest.
- One dominant day. Efficient for reaching the target, fatal for the consistency ratio, and — on a trailing account — the same session that removes the cushion.
- Trading a news window. Futures firms restrict trading around scheduled releases and enforce the restriction by pattern rather than by discussion. A position opened legitimately before the window can still breach if the rule requires it closed.
- Exceeding the contract cap. Maximum position size is usually in the terms, not on the marketing page. Trading a permitted instrument at twice the permitted size is a breach, and it is easy to do on a fast contract.
- Continuing after the target. Reaching the target is not the same as satisfying the minimum day count, and a trader who keeps trading to fill days is adding risk to a completed evaluation. Flat, qualified days satisfy a day count; they do not endanger it.
There is a seventh failure that is really a category: treating the funded account as a continuation of the evaluation. It is not. The evaluation asks whether a trader can reach a target without breaching; the funded stage asks whether a trader can extract money repeatedly under a consistency gate. The behaviours that answer the first question well are not identical to the ones that answer the second. The payout process guide walks through the sequence, and the scam checklist covers the firms for which the second question never gets asked.
Who the rulebook suits
A review that does not say who should walk away is a brochure. Here is the honest split.
The entry model suits traders who exit well. If your edge includes taking profit at a target rather than riding, the intraday mechanic costs you comparatively little, and the lower fee is genuinely better value. It also suits traders who want to learn the strictest version of the rule first, on the theory that everything else will feel easy afterwards. That theory is sound, and it is expensive to test.
The Pro model suits traders whose exits are discretionary. If you give back a third of your winners as a matter of habit — most discretionary intraday traders do — the end-of-day structure converts that habit from a structural threat into a cost. You still lose the giveback; you simply do not lose the room as well.
Neither model suits a trader without a written plan. This is not a moral judgement, it is an arithmetic one. Both accounts have a fixed dollar floor and a fixed dollar target. A trader who sizes by feel is running an uncontrolled process against a control system, and the control system wins on a long enough timeline regardless of skill. The fix is a page of numbers, not a different firm.
Neither model suits a trader who cannot trade the permitted hours. Futures rules are time-bound in a way Forex rules are not. If your available hours fall outside the liquid window, or inside a restricted news window, the evaluation is not a fair test of your trading — it is a test of your schedule. Choose a firm whose hours match your life rather than restructuring your life around a fee.
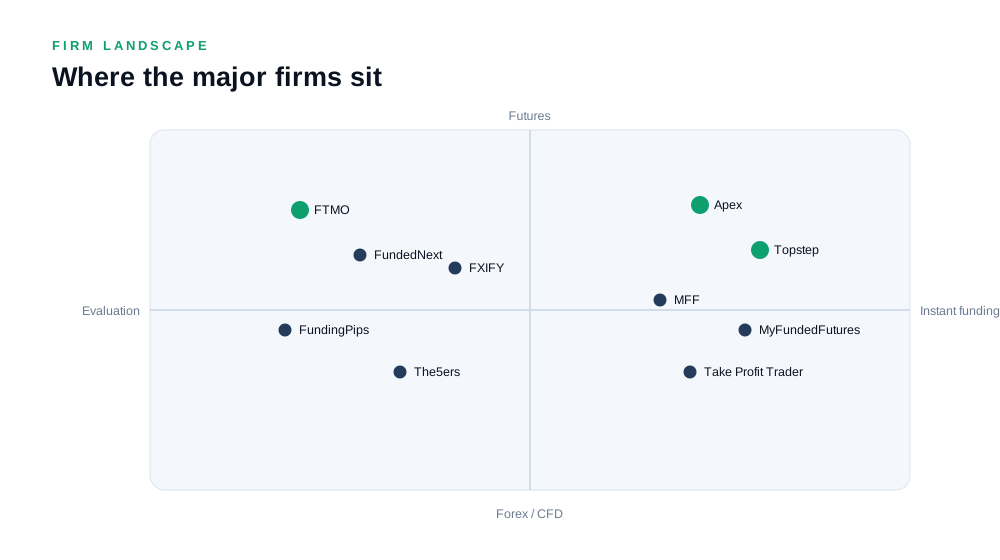
TFT against the futures field
Three comparisons do most of the work when choosing a futures firm, and they are all structural rather than financial.
Against Apex: both firms run trailing thresholds, and the useful question is which equity the threshold follows and whether the firm offers a non-trailing alternative. Apex's rulebook is widely documented and its consistency treatment at payout is explicit; TFT's distinguishing feature is the existence of two models, one of which removes the intraday mechanic entirely. A trader choosing between them is choosing between one rulebook and a menu. The Apex guide covers that side in detail.
Against Topstep: Topstep states a daily loss limit and a maximum loss limit separately, and applies a best-day expectation to the evaluation itself rather than only at payout. That makes its constraints more visible and its failure modes easier to plan around. TFT's evaluation is less explicit about the consistency expectation during the pass, which is either freedom or a trap depending on whether you read the funded terms first. The Topstep guide sets out the two-limit structure.
Against a flat-fee pass: the comparison that matters most for anyone reading a review rather than a rulebook. A service trades the evaluation for a fixed fee and absorbs the reset risk; the firm still applies its rules to the resulting funded account. That means the service removes the evaluation risk and not the payout risk, which is the correct division of labour and is worth being clear about. The passed challenges page shows what a completed evaluation looks like when it is done this way.
The general principle across all three: compare the failure floor first, the target second, the daily constraint third, and the fee fourth. Any review that inverts that order is selling rather than reviewing.
A pre-purchase verification checklist
Terms change, and a review written in October is a snapshot rather than a contract. Before paying, confirm the following on the firm's own pages, in this order. Each item takes under a minute and each one has invalidated a purchase decision at some point.
- Which equity the floor follows. Starting balance, closed balance, or intraday peak including unrealised profit. The third is the strictest and the first is the most forgiving.
- The distance from the starting balance to the floor, in dollars and as a percentage of the account. Compare that percentage, not the dollar figure, across account sizes.
- The target as a percentage of the account. A dollar target on a $150,000 account and the same dollar target on a $50,000 account are not the same evaluation.
- Whether a daily loss limit applies, whether it resets each session, and whether it is separate from the trailing floor.
- The consistency rule, stated for the evaluation and for the funded stage separately, with the percentage and the measurement basis.
- The minimum day count, for the evaluation and before each payout, and whether a scratch day counts.
- Conduct rules: contract caps, permitted hours, news windows, overnight and weekend holding.
- The reset price and whether a reset preserves the account size or restarts the evaluation from scratch.
- The first-payout waiting period and the verification requirements.
- Whether third-party trading is permitted. If it is not, no passing service should be engaged, and a service that does not ask is a service to avoid.
If any of those ten cannot be found in writing, that absence is itself the answer. A firm that does not state its failure mechanics clearly is not being modest; it is declining to be reviewed.
Frequently asked about TFT
Is TFT good for beginners?
The Pro model is reasonable for a first futures evaluation because its end-of-day threshold does not punish a winning session that retraces. The cheaper model is a harder first assignment, and the lower fee does not compensate for the extra attempts it typically takes.
What is the difference between the two TFT account models?
The drawdown mechanic. One trails the failure floor intraday on unrealised equity, so a winner that retraces permanently reduces the cushion. The other trails only at the close, so unrealised excursions are invisible to the rule. Everything downstream — sizing, pacing, expected number of attempts — follows from that difference.
Does the drawdown trail on open profit?
On the entry model, yes. That is the single most consequential rule on the account, because it means a position that is $2,000 in profit has already moved the floor even if it closes at $600. On the Pro model it does not, because the floor is only recalculated at the end of the day.
How long does a TFT evaluation take to pass?
Typically ten to eighteen trading days at a disciplined pace, depending on the model, the account size and the minimum day count. Faster passes are possible, but a pass built on one dominant session creates a consistency problem at payout that takes longer to fix than the pass saved.
What risk per trade should I use?
A third of the daily loss limit at most, with the session closed once 80% of the daily budget is realised. On the intraday model, reduce to three quarters and then half of that as completion passes 40% and 70% of the target.
Why does my cushion shrink when I am winning?
Because the floor trails the peak. Profit raises the floor, so the distance from current equity to the floor does not grow with the gain — the account's remaining room is consumed by its own success. This is why size has to fall as the target approaches.
What is the consistency rule at payout?
A cap on how much of total profit any single day may represent. Required total profit equals the best day divided by the permitted share, so a $3,000 best day under a 30% rule requires $10,000 of total profit before the withdrawal clears.
Can I hold positions overnight?
Policies differ by firm and by account type, and futures contracts carry rollover and gap risk that Forex pairs do not. Check the current terms; where holding is permitted, account for the weekend gap explicitly rather than assuming the stop will fill where it was placed.
Is TFT cheaper than Apex or Topstep?
A single fee comparison usually says yes for the entry model and no for the Pro model. The meaningful comparison is fee multiplied by expected attempts, and on that measure the cheaper account often loses once it needs a second purchase.
What happens if I breach a rule?
The account is closed and the only recovery is a new purchase or a reset, priced by the firm. Where a passing service is trading the evaluation, a reset on the same firm and size carries no additional service fee under the flat $220 arrangement — the firm's own reset charge is separate.
Can someone else pass the evaluation for me?
Only if the firm's terms permit third-party trading, which many futures firms prohibit. The service should check the terms and decline the job where it is banned. Passing an evaluation in breach of the terms produces a funded account that can be voided at payout, which is the worst possible outcome.
What should I check before paying for an evaluation?
Which equity the floor follows, the floor and target as percentages, whether a daily limit applies, the consistency rule at both stages, the minimum day counts, the conduct rules and the reset price. If the firm does not publish those, that absence is the answer.
How does this compare with a flat-fee passing service?
A flat-fee service removes the evaluation risk and the reset cost while the firm's rules still govern the funded account. That is the correct division: the service solves the test, the trader keeps the payout. The service reviews cover how the model is priced and what to verify.
A worked evaluation, session by session
Abstract rules are easy to agree with and hard to apply. Here is the same plan executed on both models with identical trades, so the structural difference is visible in outcomes rather than in description.
The setup: a $100,000 account, a $6,000 target, a $3,000 starting buffer, a $1,000 daily loss limit, and a trader risking $350 per trade with a $1,000 daily profit cap. The trade sequence is fixed and deliberately unremarkable: +$520, +$1,180, −$410, flat, +$980, +$760, −$350, +$1,240, +$640, flat, +$940.
On the end-of-day model, the floor rises by each closed profit and never by an excursion. Total realised profit after eleven sessions is $5,500, the best day is $1,240 — about 23% of the total — and the floor has risen $5,500 from its starting point. The account is $500 from target with $3,000 of room measured from the original balance and a best-day share comfortably inside a 30% rule.
On the intraday model, the same trades produce the same realised profit, but each winner's peak mattered. Suppose the $1,240 day touched $1,900 before closing, the $980 day touched $1,450, and the $640 day touched $1,050. The floor rose to the peaks, not the closes. Realised profit is still $5,500, but the floor is now $1,900 higher than the end-of-day case across those three sessions — and the remaining room is correspondingly smaller. The trader is closer to the target and closer to failure at the same time.
That is the whole difference between the models, expressed in one sequence. It does not say the intraday account is unfair, and it does not say the trader behaved badly. It says the rule measures a different quantity, and a plan calibrated to closed profit is miscalibrated for a rule that measures peaks. The correction is not more skill; it is a smaller size ladder and an earlier exit on the days that run.
| After eleven sessions | End-of-day model | Intraday model |
|---|---|---|
| Realised profit | $5,500 | $5,500 |
| Floor movement | $5,500 | $7,300 |
| Room left from original balance | $3,000 | $1,200 |
| Best day share of profit | 23% | 23% |
| Distance to target | $500 | $500 |
Note what the table makes obvious: the consistency ratio is identical on both accounts, because it is computed from realised profit, which the rule does not change. Only the failure floor diverges. Traders often assume the stricter model is stricter in every dimension; it is stricter in exactly one, and that one is the one that ends accounts.
The pacing lesson follows directly. On the intraday model, the eleven-session sequence above should have been twelve or thirteen sessions at a smaller size, with the winners cut earlier. On the end-of-day model the same sequence is unremarkable and can be repeated until the target is reached. Neither is right or wrong; they are two different products, and the fee difference between them is the price of removing a single mechanic.
The funded phase, and why it feels easier and is not
Two things change the day an evaluation passes. The trailing mechanic usually disappears, replaced by a static failure level measured from the starting balance of the funded account. And the consistency gate stops being a planning consideration and becomes a payment condition.
The first change is genuinely a relief: with a static floor, progress can no longer make the account more fragile, so a winning week is unambiguously good. The second change is the one that catches traders, because it arrives after the pressure has lifted. A trader who passed with a best day at 45% of total profit has a funded account that is technically active and practically unpayable until enough ordinary profit accumulates to bring the ratio down. The fix is to keep the daily cap in place during the funded phase, at the same fraction of the eventual payout threshold that satisfied the evaluation.
There is a third change that is rarely discussed and matters for planning: the funded account's minimum day count is usually counted separately for each payout cycle. A trader who reaches the profit threshold in five sessions but needs ten qualifying days has five sessions of nothing to do, and the temptation to fill them with size is the single most common way a funded account is lost. The correct approach is to land the threshold and the day count on the same date by pacing from the start, and to treat qualifying days as complete at the smallest closed trade that keeps the day positive.
Finally, the exit itself. Withdrawal processing on futures firms runs on a posted schedule, and the first request is usually the slowest because verification has not yet been completed. Complete identity checks in the first week, request the first withdrawal on the earliest permitted date rather than at the largest available amount, and treat that first payment as a test of the pipe rather than as income. The payout guide sets out the sequence in full, including the verification steps that cause most first requests to be rejected.
None of this is unique to TFT. It is the shape of the futures funded stage generally, and it is the part of the pipeline where a firm's reputation is actually made. An evaluation fee is small compared with a month of funded profit; the firm that pays reliably is worth a stricter rulebook, and the firm that does not is worth avoiding at any fee.
How to buy the right account
Four decisions, in order, and each one narrows the next.
- Choose the model by exit behaviour, not by fee. If your journal shows winners routinely giving back more than a third of their peak, the end-of-day model is buying you room you are currently donating. If your exits are mechanical, the entry model is the better value and the stricter rules cost you little.
- Choose the size by payout ceiling, not by pass probability. The percentage rules are identical across sizes, so a larger account buys a bigger payout and a bigger fee, not an easier test. The smallest size that produces a meaningful payout is almost always the correct first purchase.
- Budget for two attempts. Not because you will fail, but because the expected cost of the purchase includes the resets, and a trader who budgets for one attempt tends to take a second one in a hurry and a bad mood. The profit calculator makes the comparison against a flat-fee pass straightforward.
- Read the funded terms before paying the evaluation fee. The evaluation is the audition; the funded terms are the contract. A firm whose payout conditions are vague at the evaluation stage is telling you something about how the withdrawal will be reviewed.
The order matters because each decision constrains the next in a way that is invisible if you shop by price. A trader who begins with the cheapest account is choosing the strictest mechanic and then compounding it with the smallest payout ceiling, which is the worst combination available: maximum difficulty per dollar of upside.
For readers who would rather not run the evaluation at all, the flat-fee route exists and is priced at $220 for any firm and any account size, with resets covered while the evaluation is running. It is only available where the firm's terms permit third-party trading; where they do not, the service should say so before taking payment. The service comparison sets out the trade-offs honestly, and the rules matrix lets you check a firm's mechanics against the others before deciding whether to trade it yourself.
Want the evaluation traded for you?
One flat $220 for any prop firm, any account size. Retries covered, no profit split, funded login in your name. If your firm bans third-party trading we tell you before you pay, and we will not take the job.
Related reading
- Passing an Apex evaluation
- Topstep Combine rules and how to pass
- Trailing drawdown maths, worked line by line
- How much money you need to trade micro futures
- Best futures prop firms in 2026
- From funded account to first payout
- Profit and payout calculator
- The 2026 passing service review
- Recently passed evaluations
Take Profit Trader and other firms are named for identification only. ElitePropX is an independent service and is not affiliated with, endorsed by or sponsored by any proprietary trading firm. Targets, drawdown rules and payout conditions change; verify them against the firm's current terms. Trading involves substantial risk of loss.