Payout rules · reviewed November 2026
The consistency ratio, calculated
A consistency rule caps how much of your profit a single day is allowed to produce. It is not a limit on daily loss and it is not a percentage of the target — it is your best day divided by your total profit, measured at the moment you ask for money. This page does that division on real trade lists, shows why the same profit can pass or fail depending on when you stop, and sets out the three ways to bring a failing ratio back inside the line.
Key takeaways
- The ratio is best-day profit divided by total profit, not divided by the target.
- Adding profit lowers the ratio; withdrawing earlier raises it, because the denominator shrinks.
- A 40% rule allows a best day of $400 on $1,000 of profit and $1,400 on $3,500.
- Firms measure the best day, the best trade or the best week — the three variants are not interchangeable.
- Rebalancing means adding small winning days, not deleting the big one.
- A blocked payout is usually a timing problem, not a rule breach.
Contents
- What the rule measures
- The formula on one line
- A five-day pass, worked
- Why the denominator moves
- Three variants firms use
- Where the rule sits in the sequence
- Three ways to rebalance
- The mistake of measuring the target
- Consistency against the daily limit
- When a payout is already blocked
- The calendar view
- Choosing the payout size
- Keeping a ratio log
- Common questions
What the rule measures
The rule answers one question: how much of this payout came from a single session? A trader who made $3,000 across forty trading days, with no day above $300, is doing something a firm can model. A trader who made $3,000 in one afternoon has produced a sample of one, and the firm has no evidence that the result repeats. The consistency clause exists to make the second trader wait.
That framing matters because it explains the behaviour of the number. The ratio points at concentration, not at quality. A very profitable trader can fail it by being unusually good on a single Tuesday, and a marginal trader can pass it by being uniformly mediocre for a month. Neither result says anything about skill, which is exactly why reading the rule as a performance judgement leads people to argue with the firm instead of adjusting the calendar.
It also explains why the rule is usually checked at payout rather than during the evaluation. During the challenge, the firm wants the target reached. At the payout, the firm is being asked to part with money, and the concentration test is applied to the profit being withdrawn. Check the front matter of the plan you bought: the clause is written into the payout terms far more often than into the evaluation terms.
The formula on one line
Percentage = best day's profit ÷ total profit × 100. Two inputs, one division, and the answer is what the dashboard compares against the threshold.
On a 40% rule, the permitted best day is 40% of whatever total profit the account has booked. The relationship is flexible rather than fixed, which is the part most traders miss. The same $700 day fails against $1,500 of profit and passes easily against $2,000.
| Best day | Total profit | Ratio | 40% rule | 25% rule |
|---|---|---|---|---|
| $400 | $1,000 | 40.0% | At the line | Fails |
| $400 | $1,600 | 25.0% | Passes | At the line |
| $700 | $1,500 | 46.7% | Fails | Fails |
| $700 | $2,000 | 35.0% | Passes | Fails |
| $1,400 | $3,500 | 40.0% | At the line | Fails |
| $1,400 | $5,600 | 25.0% | Passes | At the line |
Read the table by column and the rule becomes a target for the denominator. To keep a $700 best day inside 40%, total profit must reach $1,750. To keep it inside 25%, total profit must reach $2,800. The trader is not being asked to earn less; they are being asked to earn the same amount over more days, which is a scheduling instruction rather than a trading one.
The rounding conventions differ between firms, and so do the boundary cases. Some treat exactly 40.0% as a pass and some as a fail, and a few round to a whole number before comparing. On a payout that sits within a point of the threshold, assume the strict reading and add another day of profit before requesting the withdrawal.
A five-day pass, worked
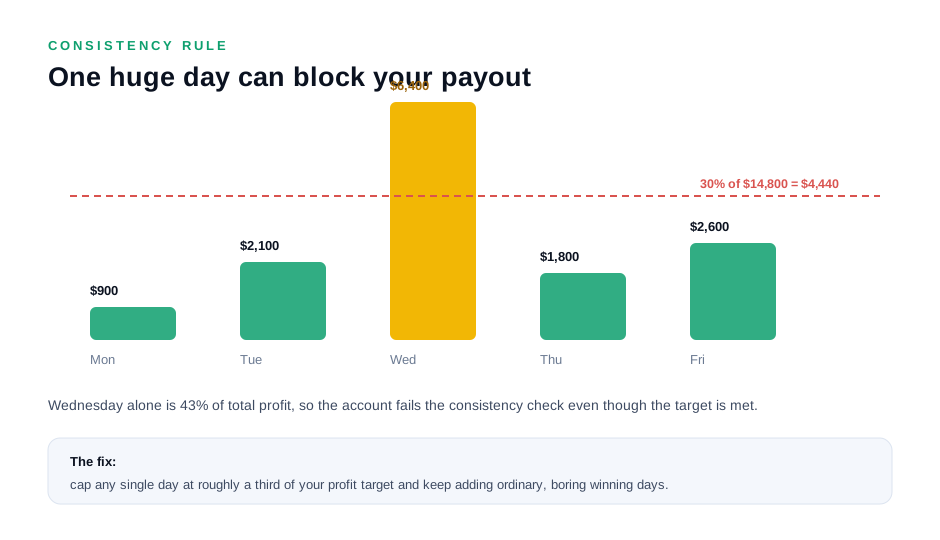
Five winning days on a $100,000 evaluation that finished with $3,000 of profit: Monday $320, Tuesday $180, Wednesday $1,400, Thursday $640, Friday $460. The best day is Wednesday at $1,400. Divided by $3,000, the ratio is 46.7%, which fails a 40% clause by 6.7 points and fails a 25% clause outright.
The reflex is to wish Wednesday away, but that is not the fix. The $1,400 day is the reason the target was reached on schedule, and a trader who avoids their best session is optimizing for a compliance metric at the cost of the thing the metric is meant to prove. The fix is to add sessions that raise the total without raising the maximum.
Two more days at $400 and $600 take total profit to $4,000. The best day is still $1,400, and 1,400 ÷ 4,000 is 35%. The account now passes a 40% rule with five points of room, and would need $5,600 of total profit to satisfy a 25% rule. Note what did not change: the size of the biggest day, the number of winning days that produced it, and the amount the trader is asking for. Only the denominator moved, and it moved because the trader kept trading after the target rather than requesting a payout immediately.
That sequence is the whole practical lesson of the rule. On accounts with a consistency clause, the profitable move after reaching the target is usually to keep going at reduced size for a week or two, because that converts a concentrated pass into a diversified one at very little risk to the profit already banked.
Why the denominator moves
Total profit is not a constant of the account. It grows with every winning day and shrinks with every withdrawal, and the consistency check runs against the balance at the moment of the request. This makes the ratio a moving target rather than a fixed grade.
Take an account that has booked $5,000 with a best day of $1,500. That is 30% and passes a 40% rule comfortably. Request a $4,000 payout and the remaining profit is $1,000, at which point the historical best day of $1,500 exceeds the remaining total and the ratio is meaningless. Firms handle this differently — some measure against profit before the withdrawal, some against lifetime profit, and some exclude the withdrawn amount from both sides. Read the wording before assuming which.
Several firms also reset the consistency clock. A payout request confirms that the first batch of profit met the rule; the next request is measured on the profit accumulated since. That reset is why traders who space payouts report fewer problems than traders who request the maximum on the day the target is hit: each cycle starts with a clean denominator and a best day that is fresh rather than accumulated.
The practical rule is to know which denominator applies to the request you are about to send, and to check the number on the dashboard the same day. A ratio computed from memory of last week's balance is routinely wrong by several points.
Three variants firms use
The word "consistency" covers three different measurements, and a plan that quotes one of them tells you nothing about the other two. Getting the variant wrong is the single most common reason a trader argues about a result they could have predicted.
| Variant | Numerator | Effect on the trader | How it fails |
|---|---|---|---|
| Best day | Largest daily profit | Easiest to plan for | One outsized session |
| Best trade | Largest single closed position | Punishes one big winner | A single 8R trade |
| Best week | Largest five-day profit | Punishes a fast start | A strong first week |
The best-day variant is the one most traders prepare for and the one most firms publish. It is generous because a day is a large bucket: a trader who takes five small winners inside one session has a large day without having had a large risk. A 40% best-day clause on a 30-day pace is usually satisfiable by simply continuing to trade.
The best-trade variant is much tighter in effect, because a single position is a small bucket. A trader whose method produces an occasional 6R winner will trip it repeatedly, and the only remedy is to scale out of large winners so no single position carries the whole day. That changes trade management rather than scheduling, and it should be decided before the account is bought, not after the first refusal.
The best-week variant is the one that surprises fast starters. A trader who makes 60% of the target in the first five sessions has created a numerator that the remaining weeks have to dilute. On that variant, a slow first week is worth more than a fast one, which is the opposite of the instinct that gets evaluations passed.
Where the rule sits in the sequence
The check is one step in a payout sequence and not a standalone verdict. Minimum trading days come first, then the profit threshold, then the consistency check, then identity verification, then the transfer. A refusal at step three is a much better position than a refusal at step five, because step three is fixable by trading and step five is fixable only by paperwork.
That ordering also explains the timing of most complaints. Traders who fail a consistency check usually reach the request in under two weeks, because a concentrated result is a fast result. The clause is doing exactly what it was written to do: slowing down the small sample. The payout sequence in full sets out what each step tests, and the payout calculator runs the arithmetic for a given account.
Some firms publish the ratio on the dashboard, some only reveal it on request, and a few never show it until the payout is refused. A trader who cannot see the number should compute it from their own statement at the end of each week, because the calculation is one line and the consequence of not doing it is a two-week delay.
Three ways to rebalance
Every remedy works on the denominator. There is no legitimate way to change the numerator after the fact, and attempts to hide a winning day by splitting it across accounts are treated as a breach rather than a fix.
The first and safest remedy is to add ordinary winning days. Trade the same method at the same size for another two weeks and the total grows while the maximum stays put. On the five-day example above, two days of average profit moved the ratio from 46.7% to 35%. Nothing about the trading changed.
The second is to reduce size while the ratio is being repaired, so a new best day is unlikely. Trading at half the usual size for the repair period makes it arithmetically hard for any single session to become the new numerator, and it turns the repair into a low-variance exercise rather than a second attempt at the same outcome.
The third is to request a smaller payout. Since the check usually runs against profit on the account, leaving profit in place keeps the denominator high. A trader who needs cash can take part of the balance and let the rest continue to dilute the best day, which is a cash-flow decision rather than a rules one.
What does not work is deleting the big day from the record, splitting it across two accounts, or asking the firm to exclude it. Each of those converts a compliance delay into an integrity question, and the second is much harder to resolve.
The mistake of measuring the target
The commonest error is dividing the best day by the profit target instead of by realised profit. On a $100,000 account with a $6,000 target and a 40% clause, a trader reads the rule as "no day above $2,400" and relaxes, because their best day was $2,000. Then they request a payout after booking $3,500 and discover that 2,000 ÷ 3,500 is 57%.
The two denominators are only equal when the account stops exactly at target. Most accounts do not: they overshoot, they take a payout early, or they finish the evaluation with a buffer. The ratio should be computed from the number on the statement, and it should be recomputed on the day of the request rather than on the day the target was reached.
A second error is assuming the clause scales with account size. It does not, because it is a ratio: the same percentage applies to a $10,000 account and a $200,000 one. What changes is the dollar size of the best day that satisfies it, and that is a position-sizing question rather than a rules question. The plain-language rules guide covers how the ratio sits alongside the other clauses.
Consistency against the daily limit
The two rules pull in opposite directions, and a plan that satisfies one can make the other harder. The daily loss limit rewards small size and frequent stops. The consistency rule rewards an even distribution of profit, which on a fixed method means the same size on the good days and the bad ones.
A trader who shrinks after a loss and expands after a win can end up with a handful of large winning days sitting on top of a long flat tail. That is a perfectly rational way to manage risk and a poor way to satisfy a concentration test. The resolution is usually to keep position size constant through a winning streak rather than pressing it, which costs some upside and buys compliance.
The same tension appears with a trailing drawdown. On a floor that follows the high-water mark, an outsized winning day lifts the floor and leaves less room beneath the position that produced it. The trailing drawdown arithmetic works that consequence through a session-by-session example, and it is the reason some firms apply a consistency check to profitable accounts specifically.
When a payout is already blocked
A refusal is not a breach unless the firm says it is. The email usually states the ratio, the threshold and the profit figure it was computed from, and the remedy is to keep trading until the denominator clears. Reply with the arithmetic you intend to use and ask for the exact denominator the firm will apply to the next request, so the two sides are working from the same number.
Ask, too, whether the current balance carries forward. Some firms let the refused profit stand as the base for the next request, in which case the repair is a handful of average days. Others reset the cycle, in which case the repair is a full new period. The difference is a week or a month and it is entirely a matter of the firm's wording.
If the refusal cites something other than the ratio — a flagged practice, a document discrepancy, a rule breach identified in review — the remedy is different and the evidence file matters more than the trading. The refusal reasons in detail covers that branch, and the client results show what a clean payout history looks like when the sequence is followed in order.
The calendar view
Because the rule is a ratio, it converts cleanly into a number of days. Work out the total profit the current best day requires, subtract what the account has already booked, and divide by the method's average daily profit. The answer is how long the repair takes, and it is knowable before the payout is requested.
Take a best day of $1,400 and an average of $250 of profit per trading day. The required total for each threshold, and the days still needed from a balance that has already booked $3,000, follow directly.
| Threshold | Total profit needed | Additional profit from $3,000 | Trading days at $250 |
|---|---|---|---|
| 50% | $2,800 | — | Already met |
| 40% | $3,500 | $500 | 2 |
| 30% | $4,667 | $1,667 | 7 |
| 25% | $5,600 | $2,600 | 11 |
| 20% | $7,000 | $4,000 | 16 |
The table makes the threshold choice the dominant variable. Moving from a 40% rule to a 25% rule turns a two-day repair into an eleven-day one, using the same trades and the same method. That is why the variant matters so much when shopping for an account: the fee difference between two plans is trivial next to the calendar difference between their clauses.
It also shows why the repair should be planned rather than improvised. A trader who knows on the day of the target that the ratio will need two more weeks of ordinary trading can size those two weeks conservatively and treat the profit as a formality. A trader who discovers it at the request has usually spent the buffer on size and has to rebuild it under time pressure.
The average daily profit in the calculation should be the method's real figure, not its best week. Using the best week shortens the estimate and produces a second refusal. Use the median day over the last month, and add a couple of days of slack for the sessions that go nowhere.
Choosing the payout size
The request amount is a variable the trader controls, and it interacts with the ratio in a way that is easy to get backwards. Reducing the request leaves more profit on the account, which keeps the denominator higher for the next cycle. Increasing it takes cash out and shrinks the base the firm will measure against.
A worked case: an account has booked $6,000 with a best day of $2,000, which is 33% and passes a 40% rule. Requesting $4,000 leaves $2,000 of profit, and against that base the best day is 100% — a second request in the same cycle would fail immediately. Requesting $2,000 leaves $4,000 and a 50% ratio, still failing. Requesting $1,000 leaves $5,000 and a 40% ratio sitting exactly on the line.
Three lessons come out of that arithmetic. The first is that a large payout can reset the ratio problem the trader just solved. The second is that the profit split percentage does not change the ratio, only the dollars, so there is no split structure that rescues a concentrated account. The third is that the payout cycle length matters: a firm that measures each cycle separately lets the trader take the full amount and start clean, while a firm that measures lifetime profit forces the denominator to stay high permanently.
Ask which basis applies before choosing the amount. On a lifetime basis, the sensible strategy is to withdraw modestly and often, keeping the best day permanently diluted. On a per-cycle basis, the sensible strategy is to take the maximum that still clears the threshold, because the next cycle starts from zero either way. The two answers differ by thousands of dollars and neither is guessable from the marketing page.
Keeping a ratio log
Five fields on a Friday afternoon keep the rule from becoming a surprise: best day this cycle, total profit this cycle, the ratio between them, the threshold on the plan, and the profit still needed to clear it. The whole entry takes under a minute once the statement is open.
A sample row reads: best day $900, total $2,400, ratio 37.5%, threshold 40%, still needed $0. The next week's row might read best day $1,900, total $4,100, ratio 46.3%, threshold 40%, still needed $650. That trajectory — a best day growing faster than the total — is the pattern that produces refusals, and it is visible a month before the request rather than on the day.
The log has a second use at payout time. If a refusal quotes a figure that disagrees with the trader's own record, the log is the evidence that the disagreement exists, and a discrepancy of a few hundred dollars in the denominator is often the entire dispute. Firm dashboards are not always refreshed, and a refusal computed from a stale balance is worth querying politely rather than accepting.
Finally, the log makes the rule teachable. A trader who can see that their best day is consistently 50% of profit has learned something about their method that no amount of screen time would reveal: they are a breakout trader whose results arrive in clusters, and the fix is a scheduling one rather than a discipline one. The dashboard shows the verdict; the log shows the trend.
Common questions
Is the consistency rule a percentage of the profit target?
No. It is a percentage of realised profit at the time of the payout request. The two numbers are the same only if the account stops exactly at target, which most accounts do not.
Does a 40% rule mean no day above 40% of the target?
It means no day above 40% of total profit. On a $6,000 target reached exactly, that is $2,400. On a $3,500 balance it is $1,400, which is why the same win can pass one week and fail the next.
Can I fail the rule with a losing account?
The clause is normally applied to profit being withdrawn, so a losing account has nothing to test. A few firms apply a separate consistency measure to the evaluation itself, which is a different clause with the same name.
Does withdrawing profit make the ratio worse?
It can, because the denominator shrinks while the best day stays in the record. Whether it does depends on whether the firm measures against profit before or after the withdrawal, which is stated in the payout terms.
Which is stricter, best day or best trade?
Best trade, in practice. A day is a large bucket that can hold several ordinary winners, while a single position is a small bucket that one outsized result fills by itself.
How long does it take to repair a failing ratio?
Usually one to three weeks of ordinary trading at the same or reduced size. The exact number is the additional profit needed to bring the best day under the threshold, divided by the average daily profit of the method.
Do prop firms waive the rule?
Rarely, and a waiver is not something to plan around. Some firms publish a lower threshold for larger accounts or a higher one for accounts held longer, but the clause is a payout condition rather than a discretionary penalty.
Tired of a ratio deciding when you get paid?
Flat $220, any firm, any account size — paced to the firm's consistency clause from the first session.
Related reading
- The consistency rule in full
- The payout sequence, step by step
- Payout calculator
- When a payout is rejected
- Trailing drawdown, worked out
- FTMO payout refusals
- Every prop firm rule, in plain language
- Prop firm rules matrix
- Passing services compared
- Passed challenges and certificates
Consistency thresholds, denominators and payout conditions are set by each firm and change without notice. Confirm the clause on the plan you are buying rather than from a general guide. ElitePropX is an independent service and is not affiliated with, endorsed by or sponsored by any proprietary trading firm. Trading involves substantial risk of loss; this page is general information, not financial advice.