
Firm guide · reviewed October 2026
Apex funded accounts: the complete guide from pass to payout
Passing an Apex evaluation is the audition, not the job. The funded account has its own activation condition, its own payout threshold, its own consistency cap and a scaling path that decides what the account is worth in a year. This guide covers that whole arc — activation, the first payout, the second, the transition from trailing to static behaviour, and the ninety days that turn a funded login into recurring income. Rules are described by mechanism, because the numbers change and the mechanics are what you actually trade.
Key takeaways
- A funded account is a different product: the failure floor usually becomes static, and a consistency cap becomes a payment condition rather than a planning consideration.
- The first payout exists to prove the process. Sizing it modestly is the correct strategy, not a timid one.
- Activation and minimum-day conditions are calendar problems. Plan them alongside the profit threshold so both complete on the same date.
- The current 50% best-day rule means required total profit equals the best day divided by 0.50. Legacy accounts still use 30%. Cap the day at a fifth of the payout target and the gate is satisfied by construction either way.
- Scaling is granted on a record of completed payouts, not on a single large month. The fastest route to a bigger account is boring consistency.
- Terms change. Confirm the current figures on the firm's own pages; this guide describes structure, not a contract.
Contents
- Why the funded account is a different product
- Activation and the first calendar
- The payout threshold, in dollars
- The consistency cap at withdrawal
- The first payout, sized correctly
- Trading a static floor after a trailing one
- The second payout and the rhythm after it
- Scaling, additional accounts and the portfolio question
- How funded accounts are lost
- Records, tax and the paper trail
- A ninety-day plan
- Frequently asked questions
Why the funded account is a different product
An evaluation asks one question: can this trader reach a target without breaching a rule? A funded account asks a different one: can this trader extract money repeatedly, under a consistency condition, without losing the account? The behaviours that answer the first are close to the behaviours that answer the second, but not identical, and the gap is where most funded accounts die.
Three things change the day the evaluation passes. The failure floor usually stops trailing and becomes static, measured from the funded account's starting balance. A consistency condition stops being advice and becomes a gate on the withdrawal. And the target stops being a single number to reach and becomes a recurring threshold that has to be cleared again before every payout.
The first change is unambiguously good. On a trailing account, profit makes the account more fragile: the floor rises with the peak, so the remaining cushion shrinks as the target approaches. On a static account, profit makes the account safer, because the floor does not move. That is a genuine relief, and it is the reason some traders find the funded stage easier to trade than the evaluation.
The second change is the opposite. A consistency cap that was a planning consideration becomes a payment condition, and it is applied to realised profit rather than to the plan. A trader who passed with one dominant session has a funded account that is technically active and practically unpayable until enough ordinary profit accumulates to bring the ratio down. That is not a punishment; it is arithmetic, and it is avoidable.
The third change is the one that surprises on timing. A funded account's profit threshold is usually paired with a minimum day count, and the two rarely complete on the same day unless the plan is built to make them. A trader who reaches the threshold in five sessions but needs ten qualifying days has five sessions of doing nothing useful, and the temptation to fill them with size is the single most common way a funded account is lost before it pays.
Activation and the first calendar
Futures firms commonly require an activation step before the funded account is live, and it is a cost that traders forget when they budget for the evaluation. The evaluation fee is paid at purchase; the activation condition arrives after a pass, when the trader is committed and less price-sensitive. Budget for it from the beginning, because a pass you cannot activate is not a funded account.
The activation condition is usually one of two shapes: a fee, or a profit threshold that has to be met on the funded account before anything is withdrawable. Some programs combine them. The practical effect is the same — the first money earned on the funded account belongs to the firm until the condition is cleared — and the planning consequence is that the first payout is farther away than the evaluation's marketing implies.
Then the calendar. Three clocks start at roughly the same moment: the minimum day count before a withdrawal can be requested, the profit threshold that has to be reached, and any waiting period measured from the first trade on the funded account. The efficient plan finishes all three on the same date, which means working backwards from the longest clock rather than forwards from today.
| Clock | What starts it | What it blocks | How to plan it |
|---|---|---|---|
| Activation condition | The pass | Any trading at all | Pay it immediately; do not delay |
| Minimum day count | The first funded session | The withdrawal request | Spread small positive days early |
| Profit threshold | The first funded session | The amount available | Cap daily profit; reach it on the last counted day |
| Verification | Registration | The payment | Complete in week one |
Two mistakes recur here. The first is trading the funded account at maximum size on day one to "get the threshold out of the way", which converts a calendar problem into a drawdown problem. The second is treating the day count as a formality and then discovering that a scratch day does not count, which pushes the date back a fortnight. Both are solved by the same decision: decide the payout date first, then work out how many sessions and how much profit per session it requires, and check that the answer is compatible with the daily loss limit.
Do the activation arithmetic before the evaluation. Evaluation fee plus activation condition is the true entry cost. If that total is uncomfortable, the account size is too large or the firm is the wrong purchase — not something to discover after a pass.
The payout threshold, in dollars
A funded account's profit threshold is a dollar figure, and dollar figures hide the two things that decide difficulty: what fraction of the account it represents, and how the consistency cap interacts with it.
Convert first. A threshold of a few thousand dollars on a $50,000 account is a materially different requirement from the same dollar threshold on a $150,000 account, even though the marketing page shows the same number in both places. Divide the threshold by the balance to get the percentage, and compare that percentage across tiers. On futures accounts the threshold usually scales with size, which means difficulty per dollar is roughly constant and the smaller tiers are not proportionally easier — commissions and slippage are identical in dollars, so they consume a larger share of a smaller target.
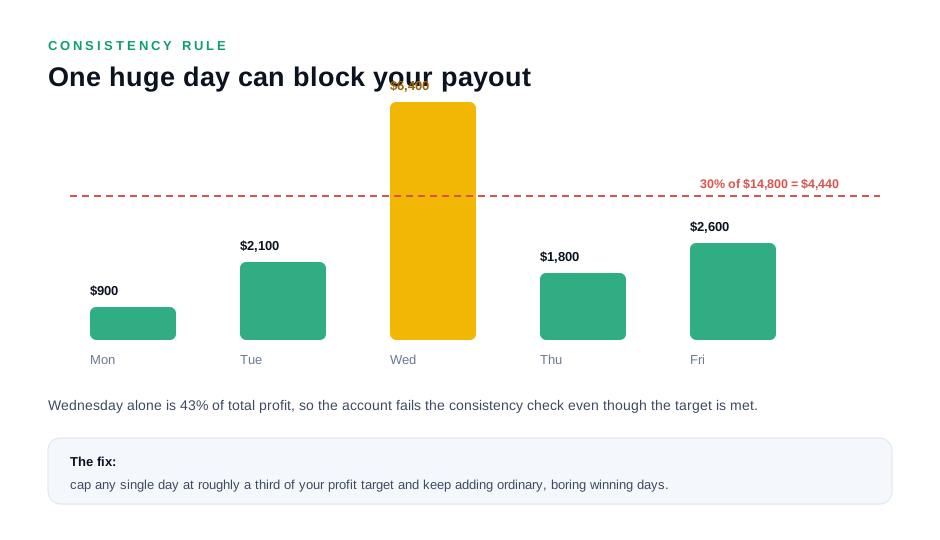
Then check the interaction with the cap. If the threshold is $3,000 and the current consistency rule permits a best day of 50% of total profit, a single $3,000 day requires $6,000 of total profit before the withdrawal clears — twice the threshold. On a legacy 30% account the same day requires $10,000. That is the trap: reaching the threshold quickly with one large session creates a requirement larger than the threshold itself. A daily profit cap set at a fifth of the threshold prevents it entirely.
| Best day | Total needed at 50% (current) | Total needed at 30% (legacy) | Daily cap that satisfies 50% at a $3,000 threshold |
|---|---|---|---|
| $600 | $1,200 | $2,000 | $900 |
| $1,000 | $2,000 | $3,334 | $900 |
| $1,500 | $3,000 | $5,000 | $900 |
| $2,000 | $4,000 | $6,667 | $900 |
| $3,000 | $6,000 | $10,000 | $900 |
Read the table from right to left again. The cap is the decision; everything else follows. A trader who caps the day at $900 against a $3,000 threshold has a best-day share of at most 30% at the moment the threshold is reached, inside both the current 50% rule and the legacy 30% rule, and can request a withdrawal without further arithmetic. A trader who caps nothing is running a lottery on their own behaviour.
The consistency cap at withdrawal
The consistency rule is the only condition on a funded account that can block a payment while the account is profitable, so it deserves more than a sentence.
The mechanics are a single division. Required total profit equals the largest day divided by the permitted share. A $2,400 best day under the current 50% rule needs $4,800 of total profit; under the legacy 30% rule it needs $8,000. A $1,200 best day needs $2,400 at 50% and $4,000 at 30%. The larger the best day, the more total profit is needed, which means the fastest route to a large number is the slowest route to a payment.
Three measurement details decide whether a trader is inside the rule, and they differ by firm and by program. Is the share computed against total profit, against the payout amount, or against the threshold? Is it measured at the request or at some later review? And does a day count from realised profit only, or from the day's peak equity? Read the clause for the exact basis, because the same headline percentage measured against total profit and against the payout amount are not the same rule at all.
Where the rule is measured at the request, a trader at exactly the threshold with a best day at exactly the permitted share is in a knife-edge position: one ordinary session improves the ratio, one unusually good session makes it worse. In that position the correct move is to keep trading at reduced size until the ratio has clear headroom rather than to submit and hope. A request that is refused costs time; a request that is never marginal costs nothing.
There is a second-order effect that catches traders who know the rule well. The best day is a fixed historical fact. Once a $2,400 day exists in the record, the total profit requirement is $4,800 at 50% (or $8,000 on a legacy 30% account) regardless of how the remaining profit is earned. A trader cannot reduce the best day; they can only raise the total. That is why the cap has to be applied from the first funded session rather than discovered at the request: after the fact, the only remedy is more profit, and more profit means more exposure to the drawdown that ends accounts.
The first payout, sized correctly
The first withdrawal is not an income event. It is a test of the pipe: that the request is accepted, the review clears, the payment arrives and the account continues afterwards. Treating it as a test changes every decision around it.
Size it modestly. A first payout that is small relative to the account is less likely to run into a consistency problem, less likely to be held for review, and less likely to leave the account in a fragile position afterwards. A trader who withdraws the maximum available on the first request is optimising a number before verifying the process that delivers it, which is the wrong order.
Complete verification first. Identity checks, address documentation and any source-of-funds request should be finished in the first week of the funded account, not at the moment of the request. A document request is the single most common cause of a delayed first payment, and the delay is entirely self-inflicted.
Then keep the record. Screenshot the request confirmation, save the statement for the period, and note the date the payment lands. Those three artefacts make the second request faster and give you something to point at if the process stalls. The payout process guide walks through the sequence step by step.

Trading a static floor after a trailing one
The shift from a trailing to a static floor is a genuine change in the maths, and traders who do not adjust leave value on the table in one direction and take unnecessary risk in the other.
On a trailing account, the correct response to profit is to reduce size, because the floor has risen and the remaining cushion is thinner. On a static account, that response is unnecessary: profit does not move the floor, so the cushion grows with the balance. A trader who keeps shrinking size after the pass is being needlessly conservative and will take far longer to reach the payout threshold.
The correct response on a static account is to keep size constant in dollar risk terms and let the cushion grow. If risk per trade was a fixed dollar amount during the evaluation, keep it. If it was a percentage, a larger balance produces a larger dollar risk, which is also defensible — but be deliberate about which of the two you are doing rather than drifting between them.
What does not change is the daily limit. A static floor does not remove the daily loss limit if the firm applies one, and on a funded account the daily limit is often the constraint that actually ends accounts. The morning calculation is the same as during the evaluation: current equity minus the floor is total room, current equity minus the daily limit is today's room, and the smaller number governs.
The one rule that survives the transition: a static floor makes the account safer as you win, but it does not make a single trade safer. Risk per trade should be set by the daily limit, not by the cushion — otherwise a comfortable account is used to justify an uncomfortable position.
There is a further subtlety on futures accounts specifically: once the floor is static, the funded account's threshold and the floor define a band. The account is only dangerous at the bottom of the band and only paid at the top. That framing makes the mid-band the place to do ordinary work at ordinary size, which is exactly what the ninety-day plan below is designed to produce.
The second payout and the rhythm after it
The second payout is where a funded account becomes a process rather than an event. It is also where most traders break the discipline that produced the first one, because the fear that motivated the evaluation has gone.
The efficient rhythm is a repeating cycle with four parts: reach the profit threshold, satisfy the day count, keep the best day in proportion, request. Once the cycle has run twice, the trader knows the actual dates and amounts, and can plan three months rather than one payout.
Two adjustments make the rhythm cheaper. First, spread the profit across sessions rather than compressing it: a threshold reached in fifteen ordinary sessions produces a better consistency ratio than the same threshold reached in six, and the daily limit is never stressed. Second, keep the daily profit cap in place permanently, at a fraction of the threshold that satisfies the consistency rule at every point in the cycle — not just at the first request.
The rhythm also changes how a losing week is experienced. During an evaluation, a losing week consumes calendar that cannot be recovered. On a funded account with no deadline, a losing week is a smaller drawdown against a static floor and an unchanged threshold, so the correct response is to trade the next ordinary session at ordinary size. Traders who respond by increasing size to "get back on schedule" are applying an evaluation instinct to a funded account, and it is the instinct that ends accounts.
Scaling, additional accounts and the portfolio question
Futures firms scale on a record, not on a month. The path to a larger balance or an additional account usually runs through a completed payout history, so the fastest way to a bigger account is a boring sequence of small, on-time withdrawals.
That has a counter-intuitive implication for the first quarter: a trader optimising for income should withdraw modestly and consistently, and a trader optimising for account size should do the same thing. The two objectives point in the same direction for once, because both are served by a clean record rather than by a large single payment.
Running multiple accounts is where the record gets complicated. Firms generally treat correlated positions across accounts as a single exposure, and some prohibit the practice explicitly. Two accounts trading the same instrument in the same direction at the same time is not diversification; it is one position with two sets of fees. The legitimate version of a portfolio is several accounts traded at different times, in different instruments, or with genuinely different plans — and even then the firm's terms come first.
The practical sequencing advice is unglamorous and correct: pass one account, trade it for a full quarter, complete two or three payouts, and only then consider a second. A trader running three funded accounts in month one has three times the conduct-rule exposure and no payout history to show for it.
How funded accounts are lost
The failure modes on a funded account are different from those on an evaluation, and they are more expensive because the thing being lost produces income.
- Size inflation after the pass. The single largest cause. The pressure that produced discipline disappears once the fee is earned, and the first position after the pass is often the largest of the trader's career.
- Filling the day count with size. Waiting for qualifying days and using them to make money is the second largest. A qualifying day can be completed with one small closed trade.
- One dominant session near the request. Converts a compliant account into one that needs three times the profit before it can pay.
- Treating the static floor as unlimited room. A larger cushion is not a licence for a larger position, because the daily limit still applies and the threshold is still the objective.
- Conduct breaches after the pass. News windows and size caps do not disappear at funding, and a breach on a funded account costs the account and the pending payout together.
- Withdrawing the maximum immediately. Maximising the first request leaves no room for a review query and no cushion if the payment is delayed.
Every one of those is a decision rather than an accident, and every one is prevented by a number written down: risk per trade as a fixed dollar amount, a daily stop at 80% of the limit, a daily profit cap at a fraction of the threshold, and a first payout sized to be unremarkable. The failure recovery guide covers what to do if the account is lost anyway.
Records, tax and the paper trail
A funded account generates income, and income generates obligations. The paperwork is not difficult, but it has to be assembled as it happens rather than reconstructed in April.
Keep three records. A trade log with entry, exit, size and result for every position, exported monthly. A payout log with the request date, the amount, the fee withheld and the date the payment landed. And a copy of the firm's terms as they stood when each payout was requested, because the basis for the payment can change and the version that applies is the version in force at the time.
On tax, the treatment differs by country and by whether the activity is classified as trading, self-employment or something else. That classification is a question for a local accountant rather than for a blog, and it is worth asking early — the answer affects whether the income is reported gross or net, what expenses are deductible, and how the firm's payment documentation should be read. What can be said generally is that a payout log makes any of those conversations shorter.
Keep payment documentation as well. Firms typically issue some form of payment statement or invoice, and a trader who relies on bank deposits alone will find the reconciliation harder than it needs to be. Save the statements alongside the payout log, and keep them for as long as your jurisdiction requires.
A ninety-day plan
Here is the arc that turns a pass into a track record, expressed as three months rather than as a list of rules.
Days 1–10 — activate and verify. Clear the activation condition, complete identity checks, and set the daily and per-trade numbers in writing. Trade small. The objective of this period is a verified account and a recorded baseline, not profit.
Days 11–30 — reach the first threshold at a controlled pace. Cap the daily profit at a fifth of the threshold, spread the work across ordinary sessions, and complete qualifying days deliberately. Request the first payout on the earliest permitted date, at a modest amount, with the record attached.
Days 31–60 — repeat the cycle twice. By the second payout the dates and amounts are known, so the plan becomes a calendar rather than a hope. Keep the cap in place. Do not add an account yet.
Days 61–90 — build the record that scaling depends on. Three completed payouts, no conduct breaches, no dominant session, and a documented plan that produced them. That record is the asset. A larger balance is usually granted against it, and it is worth more than any single month's profit.
| Window | Objective | What would undo it |
|---|---|---|
| Days 1–10 | Activation and verification complete | Trading full size before the plan is written |
| Days 11–30 | First payout requested and paid | One dominant day tripling the requirement |
| Days 31–60 | Two further cycles completed | Size inflation after the first payment |
| Days 61–90 | A clean record for scaling | A conduct breach or a maxed-out withdrawal |
The plan is deliberately unambitious per week, because the objective is a record rather than a number. A trader who completes three modest payouts in ninety days has something a firm will scale and a trader can budget against. A trader who makes one large withdrawal and loses the account has a story.
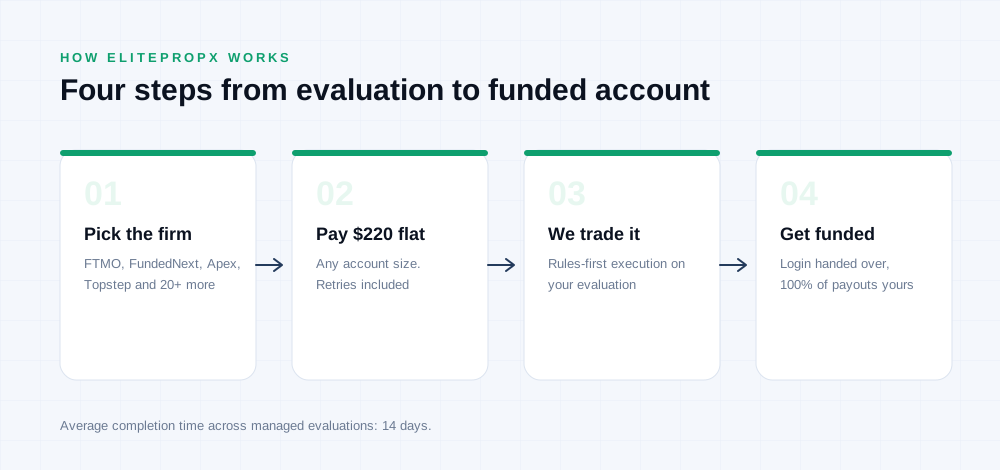
For the evaluation side of the same journey, the Apex challenge guide covers the rulebook and the trailing drawdown maths works the floor arithmetic line by line. Readers who would rather not run the evaluation at all can have it traded for a flat $220 where the firm's terms permit third-party trading; the service review sets out what to verify, and the passed challenges page shows completed evaluations.
A worked ninety days, in numbers
Take a funded account with a $3,000 payout threshold, the current 50% best-day rule, a $1,000 daily loss limit and a ten-day minimum before a request. The plan: 1.5% risk per trade, a daily stop at 80% of the limit, a daily profit cap of $600 and four sessions a week.
Week one. Activation cleared on day one, verification submitted on day two, three ordinary sessions producing $1,100 in total with a best day of $450. Two qualifying days.
Week two. Four sessions, $1,050, best day $600 at the cap. Five qualifying days, total $2,150, threshold 72% complete.
Week three. A losing session of $400, then three ordinary sessions of $260, $330 and $290. Total $3,030 — threshold reached on the tenth counted day, which is also the earliest permitted request date. The best day is $600, which is 20% of total profit, comfortably inside both the 50% rule and the legacy 30% rule.
The request. $2,000 withdrawn rather than the full balance above the threshold. The account continues with just over $1,000 of profit above the starting balance and the full daily limit intact.
Notice what the numbers did not require: no dominant session, no day near the daily limit, and no session in which size was increased. The threshold was reached in ten counted days at an average of $303 per session against a $600 cap, which means the cap was never the binding constraint on progress — it was the binding constraint on the consistency ratio, doing its job by remaining unused.
| Week | Result | Best day | Qualifying days | Cumulative |
|---|---|---|---|---|
| One | +$1,100 | $450 | 2 | $1,100 |
| Two | +$1,050 | $600 | 3 | $2,150 |
| Three | +$880 | $330 | 5 | $3,030 |
The pattern is the point. Three weeks of unremarkable sessions produced a compliant payout, and the same plan can run again immediately. A trader who reached the same threshold in four sessions with one $2,000 day would have needed $6,667 of total profit before a request, and would still be trading three weeks later with the daily limit as the only thing standing between them and a reset.
Before the first funded trade
A short list, in the order it should be completed. Each item takes minutes and each one has delayed a first payout for someone.
- Activation condition cleared and confirmation saved.
- Verification submitted — identity, address, and any source-of-funds request.
- Failure floor recorded as a dollar figure, with the basis noted (static or trailing, from starting balance or from equity).
- Daily loss limit recorded and the per-trade risk set at a third of it.
- Payout threshold, minimum day count and consistency share recorded from the current terms, with the date the terms were read.
- Daily profit cap set at a fraction of the threshold that satisfies the consistency share.
- Calendar marked for the earliest request date, the verification follow-up and any payout window.
- Conduct rules re-read — news windows, size caps, holding restrictions — because they are unchanged by the pass.
That list is the whole of the difference between a funded account that pays and one that does not. It is not a trading edge; it is the administrative layer that lets a trading edge reach a bank account.
Frequently asked about Apex funded accounts
What changes when I pass an Apex evaluation?
Three things. The failure floor usually becomes static instead of trailing, so profit stops making the account more fragile. A consistency cap becomes a payment condition rather than planning advice. And the target becomes a recurring threshold with a minimum day count attached before each withdrawal.
How long after passing can I withdraw?
That depends on the activation condition, the minimum day count and any first-payout waiting period, all of which are in the current terms. Plan backwards from the longest of the three rather than forwards from the pass date, and complete verification in week one so it is never the thing that delays you.
Why does my best day matter so much at payout?
Because a consistency rule caps the largest day as a share of total profit. Required total equals the best day divided by the permitted share, so a $3,000 best day under the current 50% rule needs $6,000 of total profit — twice a $3,000 threshold — and $10,000 under the legacy 30% rule. Cap the daily profit at a fraction of the threshold and the problem never arises.
Should I withdraw the maximum on my first payout?
No. The first payout's purpose is to prove the process: request, review, payment, account continues. A modest amount is less likely to run into a consistency query, less likely to be held for review and leaves a healthier account afterwards.
Can I increase position size after the pass?
You can, and it is the most common way funded accounts are lost. A static floor makes the account safer as you win; it does not make a single trade safer. Set risk per trade from the daily limit and keep it there for at least a quarter.
Does the daily loss limit still apply on a funded account?
Usually yes, in some form. The static floor caps total damage and the daily limit caps session damage, and the binding rule each morning is whichever is closer to current equity. Compute both before the first trade.
How do I get a larger account?
Through a record of completed payouts, not a single large month. Firms typically scale on a payout history, so the fastest route to a bigger balance is a sequence of modest, on-time withdrawals with no conduct breaches. Two or three clean cycles is usually the currency.
Can I run several funded accounts at once?
Check the terms first: correlated positions across accounts are often treated as a single exposure, and some programs prohibit it outright. The legitimate version is several accounts traded at different times or in different instruments, and even then the rules come before the strategy.
What if I hit the daily limit on a funded account?
The session ends and the account continues with a fresh daily budget against the same floor. Reopening a position after the limit is a breach in itself, and it is the most common way a recoverable day becomes a closed account.
Do I need to keep records for tax?
Yes, and the treatment varies by country and by how the activity is classified. Keep a trade log, a payout log with fees withheld and payment dates, and a dated copy of the terms. Ask a local accountant about the classification early rather than reconstructing everything later.
Is the funded stage easier than the evaluation?
The trading is often easier because the floor stops trailing, and the pressure is different because there is no deadline. The consistency gate and the day count make the payout harder to reach than a target, which is why the first withdrawal often takes longer than expected.
Can a passing service cover the funded stage too?
Most services, including ours, cover the evaluation. The funded account should be in your name with payouts to you, and the firm's rules govern it from then on. Anything else puts the account at risk at the exact moment it starts producing income.
What is the one number to write down first?
The daily profit cap, expressed as a fraction of the payout threshold that satisfies the consistency share. It is the only number that protects both the payout gate and the account, and every other figure can be derived from it.
Where these rules come from
Firm figures on this page are read from the rulebooks below rather than from other comparison sites. Every link was opened and checked on . Firms revise targets and drawdown rules without notice, so confirm the figures on the plan you are buying before paying. How we check firm rules sets out what a checked date means, what we publish when a figure cannot be confirmed, and how corrections are handled.
- Apex Trader Funding — EOD evaluation parameters, intraday trailing drawdown, 50% consistency requirement
Still on the evaluation side?
Related reading
- Paying to have an evaluation passed
- Passing an Apex evaluation
- Apex trailing drawdown maths
- Apex vs Topstep: which is safer
- From funded account to first payout
- The consistency rule, worked out
- Profit and payout calculator
- The 2026 passing service review
- Recently passed evaluations
- Apex First Payout Timeline
- Apex Trader Funding evaluation: both drawdown models, one flat fee
Apex Trader Funding and other firms are named for identification only. ElitePropX is an independent service and is not affiliated with, endorsed by or sponsored by any proprietary trading firm. Activation conditions, payout thresholds and consistency rules change; verify them against the firm's current terms. Trading involves substantial risk of loss.